
Market Overview
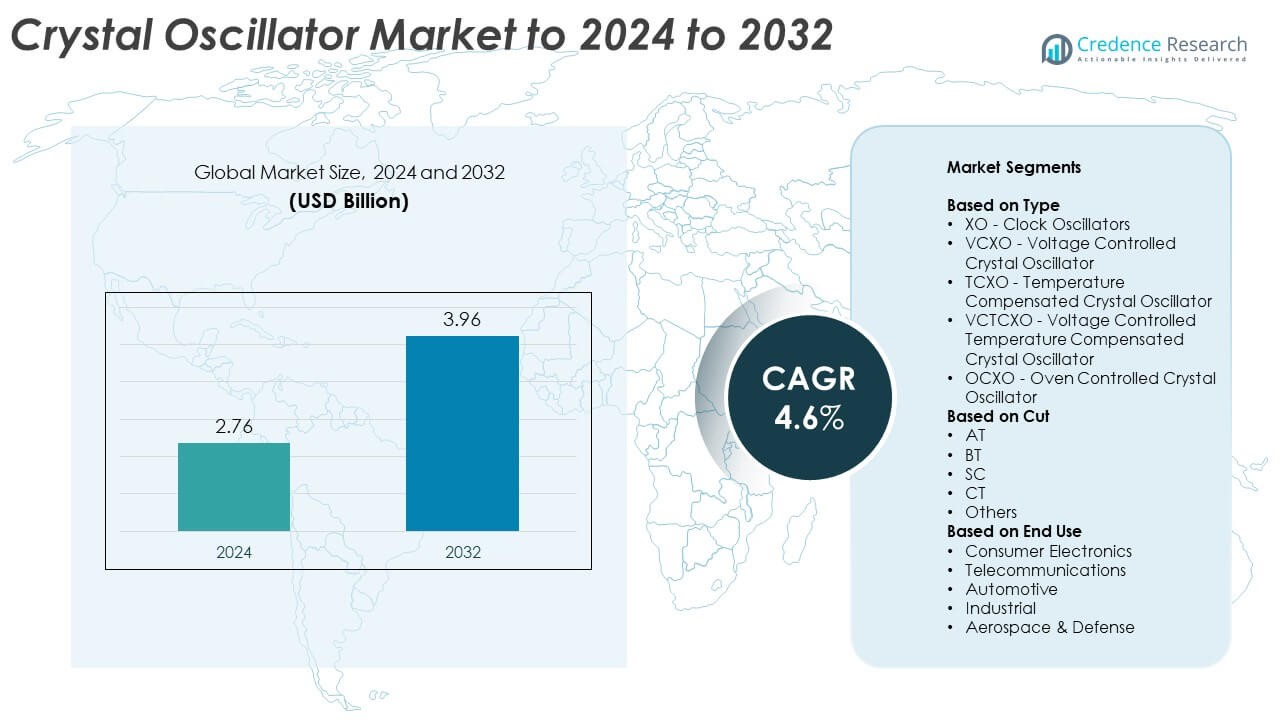
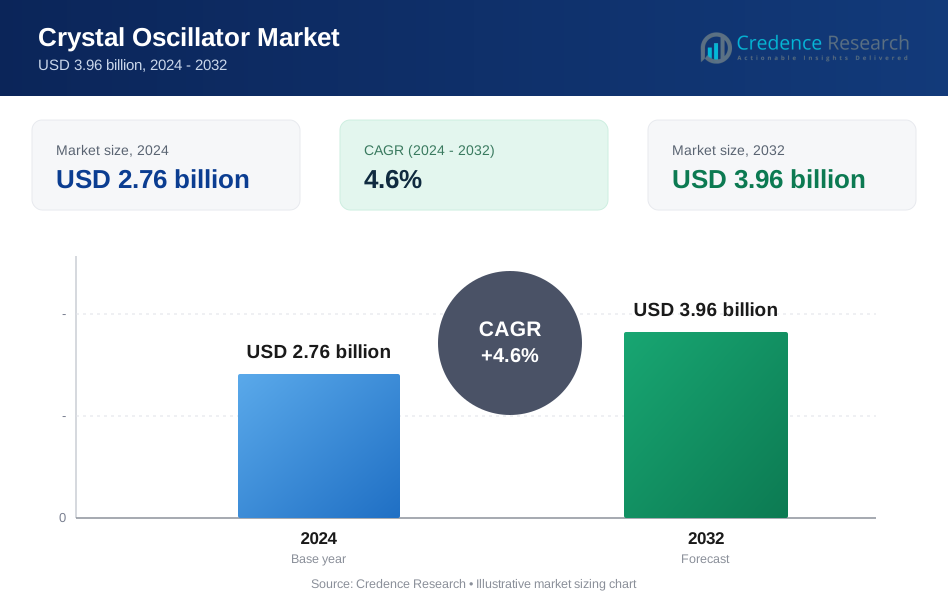
The Crystal Oscillator Market size was valued at USD 2.76 billion in 2024 and is anticipated to reach USD 3.96 billion by 2032, at a CAGR of 4.6% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Crystal Oscillator Market Size 2024 | USD 2.76 Billion |
| Crystal Oscillator Market, CAGR | 4.6% |
| Crystal Oscillator Market Size 2032 | USD 3.96 Billion |
The crystal oscillator market is highly competitive, with key players such as Seiko Epson Corporation, Murata Manufacturing Co. Ltd, Microchip Technology Inc., Nihon Dempa Kogyo (NDK) Co. Ltd, Daishinku Corp., TXC Corporation, Kyocera Corporation, Abracon, and SiTime driving technological innovation. These companies focus on developing compact, temperature-stable, and energy-efficient oscillators to meet rising demand across telecommunications, automotive, and consumer electronics industries. Asia Pacific emerged as the leading region in 2024, accounting for 34% of the global market share. The region’s dominance is supported by strong electronics manufacturing capabilities, rapid 5G deployment, and continuous investments in semiconductor production.
Market Insights
- The crystal oscillator market was valued at USD 2.76 billion in 2024 and is projected to reach USD 3.96 billion by 2032, growing at a CAGR of 4.6%.
- Rising demand for precision timing components in 5G networks, IoT devices, and automotive systems is driving market expansion.
- Miniaturization and adoption of temperature-compensated oscillators are key trends enhancing performance in compact and high-frequency applications.
- The market is moderately consolidated, with leading players focusing on product innovation, energy efficiency, and global manufacturing expansion.
- Asia Pacific led the market with a 34% share in 2024, followed by North America at 29% and Europe at 25%, while the XO segment accounted for 42% of total market share.
Market Segmentation Analysis:
By Type
The XO (Clock Oscillators) segment dominated the crystal oscillator market in 2024 with a 42% share. These oscillators are widely used in smartphones, routers, and IoT devices due to their cost efficiency and stable frequency output. Growing adoption of compact and low-power XO units in wearable electronics and data communication equipment further supports segment growth. Expanding 5G infrastructure and advancements in timing accuracy continue to drive demand, as manufacturers prioritize high-performance clock oscillators for network synchronization and signal processing applications.
- For instance, the Kyocera AVX KC2016K is a standard clock oscillator series with dimensions of 2.0 × 1.6 mm, a frequency range of 1.5 MHz to 80 MHz, and a frequency stability of ±50 ppm, which is used for applications like consumer, industrial, and wireless communication equipment.
By Cut
The AT-cut crystal segment led the market in 2024, accounting for 47% of the total share. AT-cut crystals are preferred for their excellent frequency stability across temperature ranges, making them ideal for telecom and industrial systems. Their high precision and lower production cost contribute to their wide use in oscillators for wireless devices and timing systems. Increasing deployment of AT-cut crystals in automotive electronics and GPS modules enhances their market dominance, supported by continued demand for stable frequency sources in high-reliability environments.
- For instance, Murata automotive crystals reach overall accuracy of ±40 ppm from −40 °C to +125 °C.
By End Use
The telecommunications segment held the largest market share of 38% in 2024. Telecom infrastructure, including 5G base stations and optical networks, relies heavily on crystal oscillators for precise timing control. Growing data traffic and the need for stable synchronization in communication equipment continue to propel segment expansion. Manufacturers focus on developing high-frequency oscillators with superior temperature compensation to support modern network standards, while the rollout of fiber-optic and satellite communication systems further strengthens the demand for reliable crystal oscillator components.
Key Growth Drivers
Rising Demand from Telecommunications Sector
The growing deployment of 5G networks is a key growth driver for the crystal oscillator market. Telecom base stations and network infrastructure require highly stable frequency components for synchronization and signal integrity. Increasing data transmission volumes and expanding fiber-optic networks have boosted demand for advanced oscillators with low phase noise and high precision. The push toward digital connectivity and network automation continues to strengthen the adoption of crystal oscillators across global telecommunication systems.
- For instance, SiTime offers different Super-TCXO families, each optimized for specific performance criteria. The company's ruggedized Endura family, including the SiT5543, features a maximum acceleration sensitivity as low as 0.01 ppb/g. Additionally, some of SiTime's low-noise Super-TCXOs can achieve a phase noise of -159 dBc/Hz at a 10 kHz offset for a 19.2 MHz carrier frequency
Expansion of Consumer Electronics Industry
The surge in production of smartphones, wearables, and IoT devices drives market growth. Crystal oscillators play a vital role in providing timing control and frequency stability in compact electronic systems. Manufacturers are developing smaller, energy-efficient oscillators to meet design needs for portable and connected devices. The rise in smart home devices and digital ecosystems is further accelerating oscillator demand, particularly in high-frequency and miniaturized configurations for next-generation electronics.
- For instance, NDK introduced 0.8×0.6 mm NX0806AA crystal units with low ESR for compact designs.
Increasing Automotive Electronics Integration
Automotive electronics have become a major application area for crystal oscillators. Modern vehicles depend on precision timing for safety systems, GPS navigation, and engine control modules. The expansion of electric and autonomous vehicles has amplified the need for durable, vibration-resistant oscillators. Continuous development of in-vehicle communication systems and advanced driver assistance features enhances market penetration, with manufacturers focusing on producing automotive-grade oscillators that can operate reliably under extreme environmental conditions.
Key Trends & Opportunities
Miniaturization and Low-Power Designs
One of the key trends shaping the market is miniaturization. Electronic devices are becoming smaller and more power-efficient, pushing manufacturers to develop miniature crystal oscillators that maintain high performance. Compact oscillators are gaining popularity in wearables, drones, and portable medical devices. The trend toward smaller form factors without compromising frequency stability offers opportunities for technological innovation and design optimization.
- For instance, Abracon TCXO lineup spans 5 ppm to 50 ppb stability with −40 °C to +105 °C options.
Adoption of Smart Manufacturing and IoT
Growing adoption of IoT-based production systems in industrial settings creates new opportunities. Smart factories rely on precise timing control for automation, sensors, and robotics. Crystal oscillators ensure synchronization in these connected systems. As industries adopt predictive maintenance and machine-to-machine communication, demand for oscillators supporting reliable data transfer and low-latency performance continues to rise. This trend is expected to drive innovation in industrial-grade oscillator technologies.
- For instance, TXC offers TCXOs with \(\pm 0.5\) ppm frequency stability in packages such as the 2.5x2.0 mm (7L Series) and the larger 5.0x3.2 mm (7P Series), which have a frequency range of 10–52 MHz, to support applications requiring high precision over temperature variations.
Advancements in Temperature-Compensated Oscillators
Temperature-compensated crystal oscillators (TCXO) are witnessing strong growth due to their stability in varying environmental conditions. These devices are crucial for outdoor telecom and defense applications. Innovations in temperature compensation methods and packaging materials have enhanced their precision. The development of ultra-low drift and low phase-noise TCXO models presents new opportunities for manufacturers to serve high-performance applications such as satellite communication and GPS modules.
Key Challenges
Rising Raw Material Costs
The fluctuation in prices of quartz and other raw materials used in oscillator manufacturing poses a major challenge. Higher material and processing costs increase production expenses, impacting overall profitability. Supply chain disruptions and geopolitical tensions have also added instability to sourcing. Manufacturers face pressure to balance cost control with maintaining quality and reliability standards, which can slow innovation and expansion in emerging markets.
Technological Substitution Risk
Emerging alternative technologies such as MEMS oscillators are creating competition for traditional crystal oscillators. MEMS-based solutions offer smaller size, lower power use, and improved resistance to mechanical shock. As electronics manufacturers explore these new options, crystal oscillator producers must invest in innovation to maintain market relevance. Continuous differentiation through improved frequency stability, temperature tolerance, and design flexibility is essential to address this ongoing challenge.
Regional Analysis
North America
North America held a 29% share of the crystal oscillator market in 2024, driven by strong demand across telecommunications, aerospace, and defense sectors. The region’s established electronics industry and growing adoption of 5G networks support market expansion. The United States leads production and innovation, with several key manufacturers focusing on high-stability oscillators for data centers and communication systems. Increasing investments in satellite communication and industrial automation further enhance market growth, while advancements in low-phase noise oscillator technologies continue to strengthen the region’s position in precision frequency applications.
Europe
Europe accounted for 25% of the global crystal oscillator market share in 2024. The region’s growth is supported by expanding automotive electronics and industrial automation sectors, particularly in Germany, France, and the United Kingdom. Demand for high-performance oscillators in defense communication and aerospace navigation systems remains strong. European manufacturers are increasingly investing in miniaturized and energy-efficient crystal oscillators to meet environmental and regulatory standards. The rising integration of advanced driver assistance systems and connected vehicle technologies also drives adoption across the region’s evolving automotive supply chain.
Asia Pacific
Asia Pacific dominated the crystal oscillator market with a 34% share in 2024, making it the largest regional segment. The region’s leadership is attributed to the presence of major electronics manufacturing hubs in China, Japan, South Korea, and Taiwan. Rapid expansion in consumer electronics, smartphones, and telecommunications infrastructure continues to fuel demand. Rising adoption of automation and digitalization across industries also supports market growth. In addition, strong government initiatives promoting semiconductor production and export-oriented manufacturing are enhancing Asia Pacific’s role as a key supplier of crystal oscillator components globally.
Latin America
Latin America represented a 7% share of the crystal oscillator market in 2024, supported by increasing investment in telecommunication networks and consumer electronics production. Countries like Brazil and Mexico are witnessing growing adoption of oscillators in automotive electronics and industrial monitoring systems. The region’s push toward digital transformation and IoT-based solutions in manufacturing is fostering moderate growth. Despite limited local manufacturing, imports from Asian suppliers continue to meet regional demand, while partnerships and technological upgrades in electronic component distribution strengthen market penetration.
Middle East & Africa
The Middle East & Africa region accounted for 5% of the global market share in 2024. Growth is driven by expanding defense modernization programs, aerospace projects, and industrial automation across the Gulf nations. Increasing investments in telecommunications and smart infrastructure development, particularly in the United Arab Emirates and Saudi Arabia, are supporting oscillator demand. The region’s focus on diversifying its manufacturing base beyond oil is encouraging adoption of advanced electronic components, including precision oscillators, for defense, industrial, and communication systems applications.
Market Segmentations:
By Type
- XO - Clock Oscillators
- VCXO - Voltage Controlled Crystal Oscillator
- TCXO - Temperature Compensated Crystal Oscillator
- VCTCXO - Voltage Controlled Temperature Compensated Crystal Oscillator
- OCXO - Oven Controlled Crystal Oscillator
By Cut
- AT
- BT
- SC
- CT
- Others
By End Use
- Consumer Electronics
- Telecommunications
- Automotive
- Industrial
- Aerospace & Defense
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The crystal oscillator market features strong competition among major players such as Seiko Epson Corporation, Murata Manufacturing Co. Ltd, Microchip Technology Inc., Nihon Dempa Kogyo (NDK) Co. Ltd, Daishinku Corp., TXC Corporation, Kyocera Corporation, Abracon, and SiTime. The competitive environment is driven by rapid technological innovation, with manufacturers focusing on improving frequency stability, miniaturization, and temperature tolerance. Companies are investing in advanced manufacturing techniques to support the growing demand for compact and energy-efficient oscillators across consumer electronics and automotive sectors. Strategic collaborations, product portfoio diversification, and expansion into emerging markets are key strategies shaping competition. The emphasis on low-phase noise oscillators for high-speed communication and precision applications continues to define the competitive differentiation among industry participants, while R&D efforts in MEMS-based and hybrid oscillator technologies are expected to strengthen long-term market positioning.
Key Player Analysis
- Seiko Epson Corporation
- Murata Manufacturing Co. Ltd
- Microchip Technology Inc.
- Nihon Dempa Kogyo (NDK) Co. Ltd
- Daishinku Corp.
- TXC Corporation
- Kyocera Corporation
- Abracon
- SiTime
Recent Developments
- In 2024, NDK launched a differential-output crystal oscillator series (NP2016SBE/NP2520SBE) for data centers and high-speed optical transceivers.
- In 2023, SiTime introduced its Epoch Platform, a MEMS-based oven-controlled oscillator (OCXO), to disrupt the quartz-based timing market.
- In 2023, SiTime acquired clock products and intellectual property (IP) from Aura Semiconductor, adding 20 new high-quality clocks to its portfolio.
- In 2023, Abracon launched the AS3115 Series, ultra-miniature crystal oscillators with a package footprint of just 1.6 mm x 0.8 mm.
Report Coverage
The research report offers an in-depth analysis based on Type, Cut, End-Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Rising adoption of 5G and next-generation communication systems will boost demand for high-frequency oscillators.
- Miniaturized and low-power oscillators will gain prominence in wearable and IoT devices.
- Automotive-grade oscillators will see growth with increasing electric and autonomous vehicle production.
- Advancements in temperature-compensated oscillators will enhance performance in harsh environments.
- Integration of crystal oscillators in aerospace and satellite communication will continue expanding.
- Development of smart factories and industrial IoT will drive industrial-grade oscillator demand.
- MEMS-based technologies may influence design innovation and competition within oscillator manufacturing.
- Asia Pacific will maintain its dominance due to large-scale electronics manufacturing capacity.
- Focus on energy-efficient and eco-friendly oscillator designs will increase among manufacturers.
- Strategic partnerships and R&D investments will shape future market competitiveness and product innovation.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Crystal Oscillator Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Crystal Oscillator Market projected to grow between 2025 and 2032?
Which Crystal Oscillator Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Crystal Oscillator Market?
Who are the leading companies in the Crystal Oscillator Market?
Which region commanded the largest share of the Crystal Oscillator Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Crystal Oscillator Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Crystal Oscillator Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 2.76 billion → 2032: USD 3.96 billion)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Crystal Oscillator Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Crystal Oscillator Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Crystal Oscillator Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Crystal Oscillator Market Drivers
- 3.3 Crystal Oscillator Market Restraints & Challenges
- 3.4 Crystal Oscillator Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Crystal Oscillator Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Crystal Oscillator Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Crystal Oscillator category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Crystal Oscillator Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Crystal Oscillator Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Crystal Oscillator market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Crystal Oscillator Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Crystal Oscillator Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Crystal Oscillator Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Crystal Oscillator (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Crystal Oscillator Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Crystal Oscillator Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Crystal Oscillator Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Crystal Oscillator Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Crystal Oscillator Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Crystal Oscillator Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Crystal Oscillator Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Crystal Oscillator Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Crystal Oscillator Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
