
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Laminated Tube Closure Market Size 2024 | USD 3088 Million |
| Laminated Tube Closure Market, CAGR | 5.4% |
| Laminated Tube Closure Market Size 2032 | USD 4703.2 Million |
Market Overview:
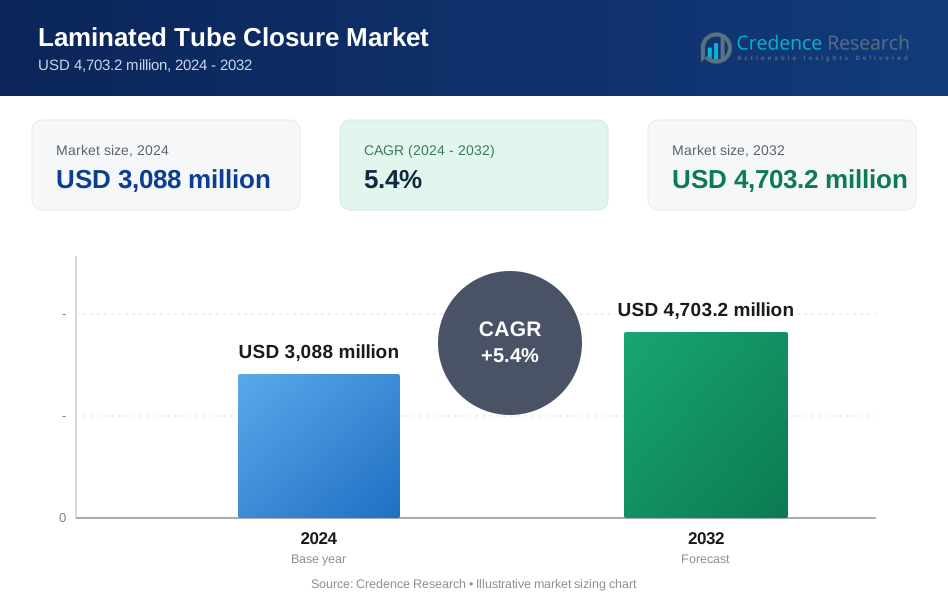
The Laminated Tube Closure Market is projected to grow from USD 3088 million in 2024 to an estimated USD 4703.2 million by 2032, with a compound annual growth rate (CAGR) of 5.4% from 2024 to 2032.
Key drivers fueling the laminated tube closure market include rising consumer demand for convenient and hygienic packaging, especially in personal care, beauty, and oral hygiene applications. These closures offer improved barrier properties, tamper-evidence, and user-friendliness, making them highly desirable in regulated sectors such as pharmaceuticals and food. Technological advancements in materials-such as recyclable plastics, biopolymers, and high-barrier laminates-are driving the development of more sustainable and functional closure designs. The integration of smart packaging features like anti-counterfeiting labels and QR codes is enhancing product authenticity and traceability. The booming e-commerce sector is also playing a pivotal role by increasing the need for durable, leak-proof, and lightweight closures that can withstand long-distance shipping. Furthermore, manufacturers are leveraging automation and custom molding technologies to reduce production costs while catering to branding needs. Together, these factors are accelerating the shift toward innovative, value-added closures that align with consumer expectations and environmental standards.
Regionally, Asia-Pacific dominates the laminated tube closure market and is expected to retain its lead over the forecast period. Rapid industrialization, urbanization, and rising disposable income in countries like China, India, and South Korea are driving demand for high-quality personal care and pharmaceutical products, which in turn boosts the need for reliable and safe packaging solutions. Japan and South Korea, in particular, are witnessing strong growth due to consumer preferences for premium cosmetics and stringent hygiene regulations. North America and Europe remain important markets, characterized by early adoption of sustainable materials, regulatory compliance, and high consumer awareness regarding packaging safety and recyclability. These regions continue to emphasize premium and customized solutions, making them attractive for innovation-led companies. Meanwhile, Latin America and the Middle East & Africa are emerging as potential growth regions, supported by expanding retail infrastructure and increasing consumption of packaged consumer goods. While these areas currently represent a smaller share of the global market, their growth rates are expected to outpace more mature regions due to a rising middle class and evolving lifestyle trends. Together, these regional dynamics reinforce a global outlook that is both optimistic and driven by strong fundamentals.
Market Insights:
- The laminated tube closure market is projected to grow from USD 3,088 million in 2024 to USD 4,703.2 million by 2032, registering a CAGR of 5.4%, driven by rising demand across personal care, pharmaceutical, and cosmetic sectors.
- Increasing consumer preference for convenient, hygienic, and user-friendly packaging is significantly influencing closure design, with a focus on tamper-evidence, airtight sealing, and controlled dispensing features.
- Manufacturers are accelerating innovation in materials, incorporating recyclable plastics, biopolymers, and lightweight composites to align with sustainability goals and meet evolving regulatory standards.
- The rise of e-commerce and the expansion of end-use industries are intensifying the need for leak-proof, durable, and visually appealing closures that maintain product integrity through extended distribution chains.
- Brands are integrating smart features into closures-such as anti-counterfeit technologies and QR codes-to enhance product security, traceability, and consumer engagement.
- Challenges such as material compatibility between closures and tubes, performance variability under diverse conditions, and the rising cost of sustainable materials are pressuring manufacturers to invest in R&D and testing.
- Asia-Pacific dominates the global laminated tube closure market due to rapid urbanization, industrial growth, and rising disposable income, while North America and Europe lead in sustainability-focused innovation and regulatory compliance.
Market Drivers:
Growing Demand for Convenient and Hygienic Packaging:
The laminated tube closure market is expanding due to increasing consumer demand for safe, clean, and user-friendly packaging. Personal care, oral hygiene, pharmaceutical, and cosmetic products rely on laminated tubes with advanced closures to ensure product integrity and ease of use. Consumers expect packaging to dispense accurately, reseal securely, and maintain hygiene throughout the usage cycle. This trend has amplified demand for closures that offer tamper-evidence, controlled dispensing, and air-tight sealing. Product convenience also influences brand loyalty, especially in travel-size and daily-use categories. The market benefits from consumer preference for packaging that supports an active, on-the-go lifestyle.
- For instance, Amcor’s trials confirmed that the lighter-weight tube maintained squeezability, high print quality, and leak-test performance, and that it is fully compatible with existing tube caps and shoulders.
Innovation in Materials and Functional Design:
Material innovation is a critical driver in the laminated tube closure market. Manufacturers are introducing closures made from recyclable plastics, bio-based polymers, and lightweight composites that reduce material consumption without compromising performance. These developments align with sustainability goals and address growing environmental concerns. Smart functional features-such as child-resistant caps, flip-top mechanisms, and one-handed operation-are enhancing product safety and user experience. Brands are also adopting closures that offer precise dosing or integrate anti-counterfeit technologies for product authenticity. It enables packaging producers to differentiate their offerings and respond to market needs more dynamically.
- For instance, Berry Global Inc. launched the Slimline range of lightweight tube closures in October 2023, which are among the lightest solutions currently available.
Expansion of End-Use Industries and E-commerce Channels:
Rapid growth in the personal care, pharmaceutical, and cosmetics industries supports strong demand in the laminated tube closure market. These sectors require durable, customizable, and visually appealing packaging that withstands transportation, storage, and regular handling. The global e-commerce boom has intensified this demand by placing higher expectations on packaging security and tamper resistance. Laminated tube closures play a vital role in ensuring that products arrive intact and retain quality during long shipping cycles. Brands are increasingly choosing premium closures to enhance shelf appeal and unboxing experiences. This shift reflects changing retail dynamics and evolving consumer expectations in both physical and digital markets.
Sustainability Goals and Regulatory Pressures:
Sustainability initiatives and tightening packaging regulations are shaping innovation in the laminated tube closure market. Governments and industry bodies are pushing manufacturers to reduce single-use plastics, adopt recyclable materials, and improve waste management practices. This regulatory landscape encourages investment in eco-friendly closure technologies that align with circular economy principles. Consumers are also supporting sustainable brands, prompting companies to emphasize closure designs that minimize environmental impact. The market is adapting by offering closures that reduce weight, use mono-material structures, or support closed-loop recycling systems. It reflects a broader industry shift toward responsible and compliant packaging solutions.
Market Trends:
Shift Toward Premiumization in Packaging Design:
The laminated tube closure market is witnessing a strong shift toward premiumization, driven by brand efforts to stand out in competitive retail environments. High-end closures with aesthetic finishes, metallic accents, and embossed logos are becoming more common in skincare, cosmetic, and wellness products. Companies are investing in visually appealing, tactilely enhanced closures to enhance consumer perception of quality and value. Closures now serve as branding tools rather than just functional components. This trend is especially prominent in luxury and niche segments, where packaging plays a key role in customer engagement. It is prompting closure manufacturers to adopt precision molding and high-end decoration techniques.
- For instance, Albéa Group officially began local production of Greenleaf™ plastic laminate web at its Brampton, Canada facility after installing a new state-of-the-art blown film line.
Adoption of Customization and Short-Run Production:
The market is embracing customization and short production runs to meet the rising demand for personalized packaging. Brands are launching limited-edition products or region-specific offerings that require uniquely designed closures in smaller batches. This shift supports marketing campaigns, seasonal releases, and influencer-led promotions. The laminated tube closure market is responding by streamlining tooling, digital printing integration, and modular mold technologies to enable quick turnarounds. Custom-fit closures tailored to tube size, application style, or product viscosity are becoming a strategic differentiator. It allows brands to align packaging with rapidly changing consumer preferences and product lines.
- For instance, Essel Propack Ltd. (EPL Limited) developed recyclable HDPE barrier tubes, including the Platina 250 and Green GML 300 Lamitubes, which have been recognized by the Association of Plastic Recyclers (APR) as meeting or exceeding strict APR HDPE critical guidance criteria.
Integration of Smart Features for User Engagement:
The integration of smart packaging elements is emerging as a key trend in the laminated tube closure market. Closures embedded with QR codes, NFC tags, or authentication seals are gaining traction across health, wellness, and cosmetic categories. These features connect physical products to digital platforms, enabling interactive experiences, usage tutorials, and brand storytelling. Brands are using closures to offer traceability, combat counterfeiting, and build direct consumer relationships. This trend supports omnichannel marketing strategies and enhances consumer trust. It is expanding the role of closures from being merely functional to becoming gateways to data-driven customer engagement.
Rising Preference for Matte, Soft-Touch, and Natural Textures:
Surface finish and texture are becoming critical design factors in laminated tube closures. Matte finishes, soft-touch coatings, and natural-look aesthetics are trending across personal care and organic product segments. These tactile qualities align with clean-label positioning and minimalist branding strategies. Consumers are responding positively to closures that reflect simplicity, purity, and sustainability in both look and feel. The laminated tube closure market is evolving to incorporate new coating technologies and materials that replicate woodgrain, stone, or ceramic-like finishes. It allows brands to elevate shelf presence while supporting eco-conscious narratives through visual and sensory appeal.
Market Challenges Analysis:
Material Compatibility and Performance Limitations:
One of the key challenges in the laminated tube closure market lies in ensuring material compatibility between closures and laminated tube bodies. Differences in thermal expansion, chemical resistance, and mechanical properties between materials can lead to performance issues such as leakage, deformation, or closure failure. Manufacturers must carefully select materials and adhesive systems that ensure a strong, reliable bond under varying environmental and usage conditions. This requirement often increases production complexity and limits design flexibility, especially for tubes containing aggressive or reactive formulations. It puts pressure on manufacturers to invest in advanced testing and quality control processes. The laminated tube closure market must address these issues to maintain consumer confidence and product integrity.
Cost Sensitivity and Supply Chain Constraints:
Cost competitiveness presents another significant challenge in the laminated tube closure market. Brands in mass-market segments often prioritize low-cost solutions, which can constrain manufacturers from adopting innovative or sustainable closure technologies. High-quality closures with specialized features or materials come with added expenses in tooling, raw materials, and production processes. The market also faces disruptions in raw material supply and logistics, particularly for plastics and specialty resins. These constraints can lead to delays, price volatility, and limited scalability for new product lines. It forces closure producers to strike a balance between performance, sustainability, and cost-efficiency in a highly price-sensitive environment.
Market Opportunities:
Expansion in Sustainable and Eco-Friendly Closure Solutions:
The laminated tube closure market has a strong opportunity to grow by aligning with global sustainability goals. Demand is increasing for closures made from recyclable, biodegradable, or mono-material plastics that simplify recycling processes. Brands are actively seeking suppliers who can deliver eco-conscious solutions without compromising on performance or aesthetics. This shift opens doors for innovation in material science and sustainable manufacturing practices. It allows closure producers to differentiate themselves through green certifications and lifecycle transparency. Companies that invest in environmentally responsible designs will likely gain a competitive advantage in both developed and emerging markets.
Emerging Demand in Pharmaceutical and Clinical Applications:
Healthcare and pharmaceutical packaging present a promising opportunity for the laminated tube closure market. Growth in topical medications, oral care treatments, and dermal therapies is fueling demand for closures that meet strict safety and hygiene standards. Closures with tamper-evidence, child resistance, and metered dispensing are increasingly favored in clinical environments. It enables manufacturers to expand their presence in regulated, high-value applications. The growing global focus on preventive care and personalized medicine further drives need for functional, secure packaging formats. By catering to these needs, the market can tap into a stable and expanding segment with long-term potential.
Market Segmentation Analysis:
By Material Type
The laminated tube closure market primarily uses plastic due to its lightweight nature, cost-effectiveness, and compatibility with various tube laminates. Aluminum is favored for its premium appeal and barrier properties, especially in pharmaceutical and high-end cosmetic applications. Glass sees limited use but holds relevance in specialized and niche segments. Other materials include hybrid compositions targeting sustainable and recyclable formats.
- For instance, Berry Global’s Slimline closures can be manufactured in virgin PE/PP or with food-safe rPE/rPP, supporting mono-material packaging for ease of recycling.
By Closure Type / Product Type
Flip-top closures dominate the market, offering convenience, resealability, and hygiene, particularly in personal care and oral care applications. Child resistance closures are growing in demand due to regulatory safety requirements in pharmaceuticals and household chemicals. Nozzle closures, including stand-up and conical designs, support precision dispensing and suit food and medicinal gels. Screw-on closures remain a staple for traditional packaging. Specialty closures serve tailored needs across industrial and cosmetic sectors.
- For instance, IntraPac International’s 2024 closure portfolio includes a patented child-resistant flip-top cap that passes ASTM D3475-20 safety standards and can be produced in diameters ranging from 19 mm to 50 mm, supporting both standard and custom tube sizes.
By Application / End-User Industry
Personal & home care and cosmetics & oral care lead in laminated tube closure consumption, driven by the popularity of creams, lotions, gels, and toothpaste. Pharmaceuticals represent a fast-growing segment, requiring closures with tamper-evidence and dosing control. Food & beverage and industrial applications are smaller but expanding through customized formats.
By Diameter (for closures)
Closures in the 35–50 mm range dominate flip-top formats, while 22–40 mm closures are standard for stand-up tubes. The 19–25 mm diameter is typical for child-resistant designs. Other variants support specialized product categories.
By Packaging Type
Laminated tubes with barrier films provide protection against moisture, UV, and oxygen, supporting sensitive formulations. Multi-layer laminate tubes offer strength and flexibility, catering to high-volume consumer products.
Segmentation:
By Material Type
- Aluminum
- Plastic
- Glass
- Others
By Closure Type / Product Type
- Flip-top closures
- Child resistance closures
- Nozzle closures (including stand-up and conical)
- Screw-on closures
- Other specialty closures
By Application / End-User Industry
- Personal & Home Care (creams, lotions, shampoos, gels)
- Cosmetics & Oral Care (toothpaste, beauty creams)
- Food & Beverage (condiments, edible gels)
- Pharmaceuticals (ointments, gels, medicinal creams)
- Others (household, industrial, specialty uses)
By Diameter (for closures)
- 22–40 mm (stand-up closures)
- 19–25 mm (child resistance closures)
- 35–50 mm (flip-top closures)
- Others
By Packaging Type
- Laminated tube with barrier film (for moisture, UV, air protection)
- Multi-layer laminate tubes
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
Asia-Pacific Leads with Strong Manufacturing and Consumer Demand
Asia-Pacific holds the largest share of the laminated tube closure market, accounting for approximately 38% of global revenue. Rapid urbanization, rising disposable incomes, and the growth of the personal care and pharmaceutical industries in countries like China, India, Japan, and South Korea continue to drive demand. Local manufacturers are expanding laminated tube production capacities to meet rising needs for affordable, high-volume packaging. Consumer preferences for hygiene, convenience, and aesthetic appeal are influencing demand for innovative closures across product categories. South Korea and Japan are leading in premium cosmetic closures, while India and China are driving volume-based growth in oral care and pharmaceutical products. The region remains a key hub for both production and consumption.
Europe Maintains Market Leadership in Sustainable Innovation
Europe represents around 27% of the global laminated tube closure market, supported by its strong focus on regulatory compliance, sustainable packaging, and high-value product innovation. Countries like Germany, France, the UK, and Italy play a central role in driving demand for closures that meet stringent environmental and safety standards. European manufacturers are prioritizing recyclable and mono-material closures to align with the EU’s circular economy goals. The region’s mature personal care and cosmetics industries prefer premium, tamper-evident closures that complement brand identity. Innovation in materials, coupled with high consumer awareness, is reinforcing Europe’s leadership in sustainable laminated tube closure development. It remains a critical market for value-added, design-centric packaging solutions.
North America Driven by Brand Customization and E-commerce Growth
North America accounts for approximately 22% of the laminated tube closure market, with strong demand coming from the United States and Canada. The region emphasizes premiumization, custom branding, and e-commerce-ready packaging formats, particularly in skincare, health, and wellness products. Consumer expectations for convenience, sustainability, and product safety are pushing manufacturers toward advanced closures with smart features. The pharmaceutical sector in North America also contributes significantly, requiring closures that meet FDA and industry-specific safety standards. The rise of direct-to-consumer brands has elevated the need for tamper-resistant and visually distinctive closures. It is also driving investment in automation and short-run custom production for limited edition and personalized products.
Key Player Analysis:
- Amcor Plc
- Berry Global Inc.
- Albea Group
- CCL Industries Inc.
- Essel Propack Ltd. (EPL Limited)
- IntraPac International
- Kap Group
- Pirlo GmbH & Co. KG
- Abdos India
- Amtik Group
- Sibo Group
- Winpak Ltd.
- Sonoco Products Company
- Huhtamaki Oyj
Competitive Analysis:
The laminated tube closure market is characterized by the presence of both global packaging leaders and regional specialists competing across product innovation, material sustainability, and customization capabilities. Companies like Amcor Plc, Berry Global Inc., and Albea Group hold significant market share due to their global reach, diversified portfolios, and advanced manufacturing capabilities. Essel Propack Ltd. (EPL Limited) and CCL Industries Inc. maintain strong positions through specialized laminated packaging and tube-to-closure integration. IntraPac International, Kap Group, and Pirlo GmbH focus on niche markets and offer tailored closure solutions. The market favors companies that invest in sustainable materials, smart closure technologies, and rapid product development cycles. It rewards innovation in design, barrier functionality, and ease of use, particularly in sectors such as cosmetics, pharmaceuticals, and personal care. Strategic partnerships, regional expansions, and M&A activities continue to shape the competitive landscape. The laminated tube closure market remains dynamic, with competition centered on performance, compliance, and cost-efficiency.
Recent Developments:
- In June 2025, Amcor Plc achieved a 16.67% reduction in the wall thickness of its 50mm diameter flexible tube sleeves for Bulldog skincare products in 100ml and 150ml sizes, resulting in an annual savings of approximately 8.5 metric tonnes of plastic. This innovation was accomplished through rigorous trials that maintained squeezability and high-print quality, and the lighter-weight tube remains fully compatible with existing closures. Additionally, Amcor increased the post-consumer recycled (PCR) plastic content in the complete tube to over 62%, further enhancing the sustainability profile of the packaging.
- In October 2024, Albéa Group expanded its North American production capabilities by installing a new blown film line at its Brampton, Ontario facility. This upgrade enables the local manufacturing of Greenleaf plastic laminate web, making recyclable HDPE tubes available for the North American market. The Greenleaf tubes are recycling-ready in HDPE streams, as certified by the Association of Plastic Recyclers, and are designed to replace aluminum-foil-containing tubes for toothpaste, personal care, cosmetics, and pharmaceutical products. The Brampton site specializes in extrusion lamination of multi-layer webs for both aluminum-barrier laminate (ABL) and all-plastic laminate tubes.
- In 2025, Berry Global Inc. continued to invest in sustainable solutions for the laminated tube closure market, focusing on the integration of recycled plastics and development of lightweight closure designs. The company is leveraging its global manufacturing footprint to expand its reach in the personal care and cosmetics sectors, with closures that offer tamper-evidence and improved recyclability
- In 2025, Essel Propack Ltd. (EPL Limited) advanced its sustainability agenda by increasing the use of post-consumer recycled (PCR) materials in its laminated tube closures and expanding its product portfolio to include biodegradable and eco-friendly closure options. The company’s strategic investments in R&D and manufacturing are aimed at meeting the growing demand for sustainable packaging in personal care and oral care markets.
Market Concentration & Characteristics:
The laminated tube closure market exhibits moderate market concentration, with a mix of global players and regional manufacturers shaping competition. Leading firms such as Amcor Plc, Berry Global Inc., and Albea Group command notable shares due to their scale, integrated capabilities, and global supply networks. The market features high product differentiation, driven by closure type, material innovation, and application-specific requirements. It prioritizes reliability, hygiene, and design flexibility, especially in regulated industries like pharmaceuticals and cosmetics. Barriers to entry are moderate, with capital investment, regulatory compliance, and material sourcing posing key challenges for new entrants. The laminated tube closure market values agility, sustainability, and customization, encouraging continuous development in smart and eco-friendly closure solutions.
Report Coverage:
The research report offers an in-depth analysis based on By Material Type, By Closure Type, By Application, By Diameter, By Packaging Type and By Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The laminated tube closure market is expected to maintain steady growth through 2032, supported by expanding demand in personal care and pharmaceutical sectors.
- Innovations in recyclable and bio-based materials will drive the development of more sustainable closure solutions.
- Smart closures with anti-counterfeit features and digital connectivity will gain wider adoption in premium and health-related products.
- Asia-Pacific will continue leading global market share, driven by high-volume production and increasing domestic consumption.
- E-commerce growth will boost demand for tamper-proof and durable closures that support long-distance shipping.
- Regulations targeting plastic waste will pressure manufacturers to adopt mono-material and low-impact designs.
- Customization and limited-edition product packaging will spur investment in flexible and short-run closure manufacturing.
- Technological advancements will enable faster, more precise production, reducing lead times and costs.
- Demand for child-resistant and metered dispensing closures will rise across pharmaceutical and healthcare applications.
- Strategic partnerships and regional expansions will shape competitive dynamics and support global scalability.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Demand for Convenient and Hygienic Packaging
Consumers increasingly expect packaging that is easy to use, tamper-evident, and maintains product hygiene, especially in personal care, oral care, and pharmaceutical applications. Laminated tube closures meet these needs by offering secure resealing, controlled dispensing, and protection against contamination.
Innovation in Sustainable Materials
Manufacturers are developing closures using recyclable plastics, biopolymers, and lightweight composites to address environmental concerns and comply with stricter regulations. This shift toward eco-friendly materials is attracting brands seeking to enhance their sustainability credentials and appeal to environmentally conscious consumers.
Growth of E-commerce and Extended Distribution Chains
The rise of online retail has increased the need for durable, leak-proof, and tamper-resistant closures that can withstand long-distance shipping and handling. Laminated tube closures are being designed to ensure product integrity and enhance the unboxing experience, supporting brand reputation in digital channels.
Expansion of Personal Care and Pharmaceutical Sectors
Rapid growth in personal care, cosmetics, and pharmaceutical industries - especially in emerging markets - drives demand for high-quality, functional closures. These sectors require closures that offer safety, dosing control, and compatibility with sensitive formulations, fueling market expansion.
Integration of Smart and Custom Features
Brands are adopting closures with anti-counterfeit technologies, QR codes, and customized designs to enhance product security, traceability, and consumer engagement. This trend supports premiumization and differentiation in competitive retail environments.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Laminated Tube Closure Market?
What factors are driving the growth of the Laminated Tube Closure Market?
What are the key segments within the Laminated Tube Closure Market?
What are some challenges faced by the Laminated Tube Closure Market?
Who are the major players in the Laminated Tube Closure Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Application
- 1.2.1 Personal & Home Care
- 1.2.2 Cosmetics & Oral Care
- 1.2.3 Pharmaceuticals
- 1.2.4 Food & Beverage
- 1.2.5 Others
- 1.3 By Closure Type
- 1.3.1 Flip-top closures
- 1.3.2 Child resistance closures
- 1.3.3 Nozzle closures
- 1.3.4 Screw-on closures
- 1.3.5 Other specialty closures
- 1.4 By Material Type
- 1.4.1 Plastic
- 1.4.2 Aluminum
- 1.4.3 Glass
- 1.4.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 3,088 million → 2032: USD 4,703.2 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Laminated Tube Closure Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Laminated Tube Closure Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Laminated Tube Closure Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Laminated Tube Closure Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Laminated Tube Closure Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Laminated Tube Closure Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Laminated Tube Closure Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Laminated Tube Closure Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 3,088 million → 2032: USD 4,703.2 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Laminated Tube Closure Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Application - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Personal & Home Care
- 12.3.7.2 Cosmetics & Oral Care
- 12.3.7.3 Pharmaceuticals
- 12.3.7.4 Food & Beverage
- 12.3.7.5 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Closure Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Flip-top closures
- 12.4.7.2 Child resistance closures
- 12.4.7.3 Nozzle closures
- 12.4.7.4 Screw-on closures
- 12.4.7.5 Other specialty closures
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Material Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Plastic
- 12.5.7.2 Aluminum
- 12.5.7.3 Glass
- 12.5.7.4 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Laminated Tube Closure End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Laminated Tube Closure Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Laminated Tube Closure Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Laminated Tube Closure Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Amcor Plc
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Berry Global Inc.
- 18.4 Albea Group
- 18.5 Essel Propack Ltd. (EPL Limited)
- 18.6 CCL Industries Inc.
- 18.7 IntraPac International
- 18.8 Pirlo GmbH & Co. KG
- 18.9 Sonoco Products Company
- 18.10 Huhtamaki Oyj
- 18.11 Winpak Ltd.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

