
Market Overview
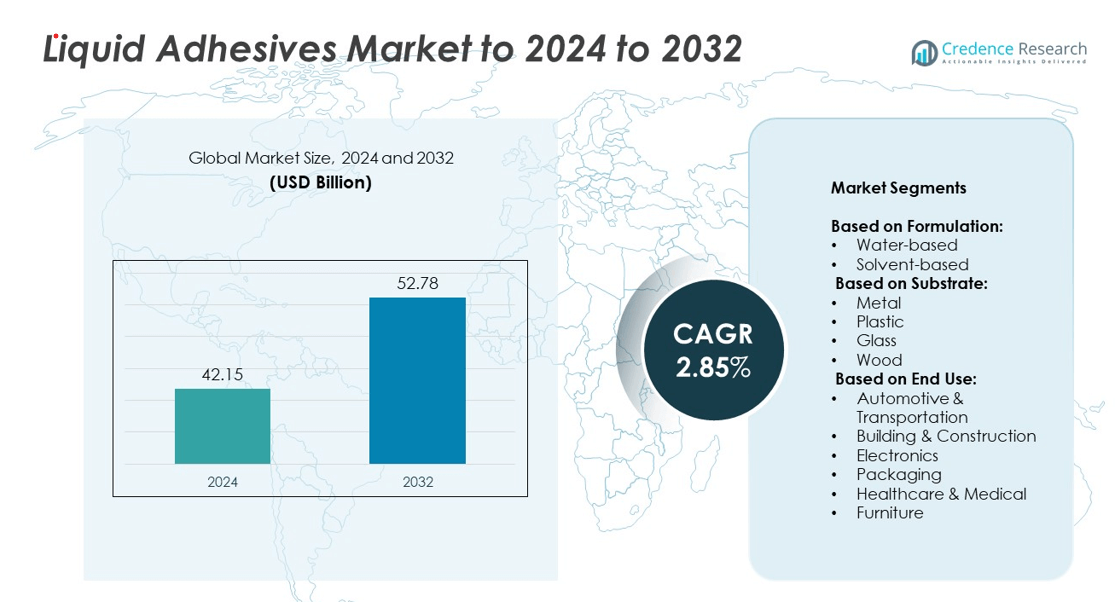
The Liquid Adhesives Market size was valued at USD 42.15 billion in 2024 and is anticipated to reach USD 52.78 billion by 2032, at a CAGR of 2.85% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Liquid Adhesives Market Size 2024 | USD 42.15 billion |
| Liquid Adhesives Market, CAGR | 2.85% |
| Liquid Adhesives Market Size 2032 | USD 52.78 billion |
The liquid adhesives market is shaped by leading companies such as 3M, Henkel AG & Co. KGaA, Dow Inc., H.B. Fuller Company, Bostik SA, Avery Dennison Corporation, and Huntsman Corporation, which maintain strong positions through innovation, product diversification, and global presence. These players emphasize eco-friendly formulations and advanced bonding technologies to cater to industries such as packaging, automotive, construction, and healthcare. Regionally, Asia Pacific leads the market with a 34% share in 2024, supported by rapid industrialization, rising packaging demand, and large-scale automotive production. North America follows with 28%, while Europe accounts for 24%, reflecting strong adoption in regulated and technology-driven industries.
Market Insights
- The liquid adhesives market size reached USD 42.15 billion in 2024 and will hit USD 52.78 billion by 2032, at a CAGR of 2.85%.
- Rising demand from the packaging sector, supported by e-commerce growth and consumer goods, is driving strong adoption.
- Water-based adhesives are trending as the preferred choice due to eco-friendly properties and strict VOC regulations.
- The market is moderately consolidated, with key players focusing on sustainable innovations, strategic acquisitions, and expansion in emerging markets.
- Asia Pacific led with 34% share in 2024, followed by North America at 28% and Europe at 24%, while packaging held over 35% of the global segment share.
Market Segmentation Analysis:
By Formulation
The liquid adhesives market by formulation is divided into water-based and solvent-based types. Water-based adhesives dominated the segment in 2024, holding over 58% of the market share. Their growth is driven by eco-friendly properties, low volatile organic compound (VOC) emissions, and compliance with strict environmental regulations. Industries favor water-based formulations for their safer handling and strong bonding performance across substrates like paper, wood, and textiles. Increasing demand in packaging, construction, and furniture applications continues to strengthen their dominance over solvent-based alternatives.
- For instance, Henkel: Technomelt Supra 130 Cool is now produced with a minimum 20% lower cradle-to-gate CO₂ per kg of adhesive, while keeping the same bonding performance for packaging lines.
By Substrate
Among substrates, plastics held the largest market share in 2024, accounting for nearly 42%. The rise of plastic components in automotive, packaging, and electronics sectors supports this dominance. Adhesives designed for plastics deliver durability, flexibility, and resistance to stress, making them vital in lightweight product manufacturing. With packaging shifting to flexible formats and automotive designs prioritizing lighter parts, plastic substrates remain the leading area for liquid adhesive usage. Continuous innovation in adhesive chemistries further expands compatibility with diverse plastic materials.
- For instance, 3M: Scotch-Weld DP8805NS reaches 7 MPa overlap shear strength in ~9 minutes and shows tested lap-shear on plastics such as PVC 1,800 psi, ABS 1,200 psi, Polycarbonate 850 psi per data sheet.
By End Use
The packaging industry emerged as the dominant end-use segment, securing over 35% of the market share in 2024. Strong growth in e-commerce, consumer goods, and food packaging has created consistent demand for reliable and cost-effective bonding solutions. Liquid adhesives are valued for fast curing, strong seals, and application versatility across cardboard, plastic, and laminates. Additionally, sustainability trends drive innovation in recyclable packaging adhesives. With increasing global packaging production and stricter performance standards, the segment continues to lead adoption across end-use industries such as automotive, electronics, and healthcare.
Key Growth Drivers
Rising Demand from Packaging Industry
The packaging industry is the leading growth driver for the liquid adhesives market. Expanding e-commerce, consumer goods, and food packaging segments create steady demand for high-performance adhesives. Their ability to provide durable bonds, fast curing, and compatibility with diverse substrates makes them essential. Sustainability trends, such as recyclable packaging, further boost adoption. With packaging accounting for the highest end-use share, this sector continues to anchor overall market expansion.
- For instance, Arkema / Bostik launched its Kizen™ LIME adhesive in 2024 comprising at least 80% renewable ingredients.
Increasing Adoption in Automotive and Transportation
Automotive and transportation industries rely heavily on liquid adhesives for lightweight materials and structural bonding. Adhesives replace mechanical fasteners, reducing vehicle weight while enhancing performance and fuel efficiency. Growth in electric vehicle production amplifies demand for adhesives with heat resistance and durability. As automakers prioritize efficiency and safety, liquid adhesives remain integral in both conventional and next-generation vehicle designs, strengthening this segment’s contribution to overall market growth.
- For instance, DuPont’s BETAMATE 73312/73313 structural adhesive achieves 12.4 MPa lap shear strength on aluminum and steel substrates.
Shift Toward Environmentally Friendly Formulations
The industry is witnessing a major shift toward water-based adhesives due to regulatory and sustainability pressures. Governments worldwide enforce stricter restrictions on solvent-based formulations with high VOC emissions. Water-based adhesives offer safer handling, compliance benefits, and strong bonding performance, ensuring their growing dominance. Consumer demand for eco-friendly solutions also accelerates adoption across industries. This transition to sustainable adhesive technologies represents a key driver shaping the future growth of the market.
Key Trends & Opportunities
Integration of Advanced Chemistries
Manufacturers are innovating liquid adhesives with advanced chemistries to enhance adhesion, flexibility, and durability. Formulations with improved heat and chemical resistance are increasingly used in electronics, medical devices, and automotive applications. These advancements allow adhesives to meet evolving industry standards, opening opportunities in high-performance applications. Such product innovations expand market reach and drive differentiation among suppliers.
- For instance, Baxter states that more than 4 million patients worldwide have received Seprafilm Adhesion Barrier, and randomized trials showed 51% adhesion-free rate in treated patients versus 6% in controls in abdominal surgery.
Expansion in Healthcare and Medical Applications
Healthcare has become a growing opportunity for liquid adhesives, driven by demand for medical devices and disposable products. Adhesives are used in wound care, surgical instruments, and wearable devices, offering strong bonding with biocompatible properties. Rising healthcare expenditure and expanding medical device production enhance adoption. This trend positions healthcare as a promising sector for market players seeking growth beyond traditional industries like packaging and construction.
- For instance, Bostik disclosed that Kizen™ LIME avoids almost 100% carbon footprint when accounting for biogenic carbon uptake.
Key Challenges
Volatility in Raw Material Prices
The market faces pressure from fluctuating prices of raw materials such as petrochemicals and resins. Rising costs directly affect adhesive manufacturers’ margins and limit price competitiveness. Dependence on global supply chains further amplifies the impact of market volatility. Companies must adopt strategic sourcing and develop alternative raw materials to mitigate these risks, but the challenge remains persistent.
Stringent Environmental Regulations
Regulatory restrictions on solvent-based adhesives present a significant challenge for manufacturers. Compliance with evolving global standards on VOC emissions and chemical usage increases production costs and limits product flexibility. Smaller firms often struggle to invest in sustainable formulations or meet certifications. While regulations push the industry toward eco-friendly innovations, they also create compliance burdens, particularly for cost-sensitive markets.
Regional Analysis
North America
North America accounted for 28% of the global liquid adhesives market share in 2024, driven by strong demand in packaging, automotive, and construction sectors. The region benefits from advanced manufacturing technologies, high adoption of eco-friendly formulations, and significant investment in research and development. The United States remains the largest contributor due to the scale of its automotive and healthcare industries. Growth in e-commerce further boosts packaging applications. Canada and Mexico also contribute steadily, with increasing industrial and infrastructure activities supporting market expansion across the region.
Europe
Europe held 24% of the global liquid adhesives market share in 2024, supported by stringent environmental regulations that encourage the use of water-based adhesives. The region’s automotive, construction, and packaging industries represent major demand drivers. Germany, France, and the United Kingdom lead the adoption of advanced formulations for high-performance applications. The push toward sustainable materials, along with robust consumer goods demand, sustains market growth. Investments in healthcare and electronics further diversify opportunities, though regulatory compliance costs challenge smaller producers across the region.
Asia Pacific
Asia Pacific dominated the liquid adhesives market in 2024, securing 34% of the global share. Rapid industrialization, rising construction activities, and expanding automotive production fuel strong demand. China, India, and Japan remain key contributors, with packaging being the largest application segment. Growing e-commerce and consumer goods markets amplify usage in flexible packaging. Favorable government initiatives supporting manufacturing growth and infrastructure projects further enhance adoption. The region’s large-scale production capabilities also provide cost advantages, positioning Asia Pacific as the leading global hub for liquid adhesive demand and supply.
Latin America
Latin America accounted for 8% of the liquid adhesives market share in 2024, with Brazil and Mexico as the primary growth engines. The market benefits from rising packaging demand, particularly in food and beverages, and expanding automotive assembly operations. Construction projects across urban centers further contribute to market expansion. However, economic fluctuations and limited investment in advanced adhesive technologies slow adoption compared to developed regions. Despite these challenges, steady industrial growth and increasing e-commerce activity position Latin America as an emerging contributor to global market demand.
Middle East and Africa
The Middle East and Africa held 6% of the global liquid adhesives market share in 2024. Growth is primarily driven by building and construction activities supported by infrastructure development programs across the Gulf countries. Packaging demand in consumer goods and healthcare applications is also rising steadily. South Africa and the United Arab Emirates serve as key markets, while broader regional growth remains uneven due to economic and political instability. Nevertheless, expanding industrial sectors and government-led initiatives to diversify economies create new opportunities for adhesive manufacturers in this region.
Market Segmentations:
By Formulation:
- Water-based
- Solvent-based
By Substrate:
- Metal
- Plastic
- Glass
- Wood
By End Use:
- Automotive & Transportation
- Building & Construction
- Electronics
- Packaging
- Healthcare & Medical
- Furniture
By Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Competitive Landscape
The competitive landscape of the liquid adhesives market features leading players such as Beardow Adams, Huntsman Corporation, Avery Dennison Corporation, Henkel AG & Co. KGaA, Jowat SE, 3M Company, Pidilite Industries Ltd., Bostik SA, Mapei S.p.A., Dow Inc., DIC Corporation, and H.B. Fuller Company. The market is moderately consolidated, with global leaders maintaining a stronghold through diverse product portfolios and technological advancements. Companies focus on developing eco-friendly formulations to comply with environmental regulations and meet rising demand for sustainable solutions. Strategic initiatives such as acquisitions, regional expansions, and partnerships enhance global presence and customer reach. Innovation in water-based and high-performance adhesives tailored for industries like packaging, automotive, electronics, and healthcare drives competitiveness. Intense rivalry encourages continuous R&D investments, cost optimization, and product differentiation. The competition remains dynamic, shaped by shifting consumer needs, regulatory frameworks, and the growing emphasis on performance-driven, environmentally sustainable adhesive solutions.
Key Player Analysis
- Beardow Adams
- Huntsman Corporation
- Avery Dennison Corporation
- Henkel AG & Co. KGaA
- Jowat SE
- 3M Company
- Pidilite Industries Ltd.
- Bostik SA
- Mapei S.p.A.
- Dow Inc.
- DIC Corporation
- B. Fuller Company
Recent Developments
- In 2024, 3M continues to position its 3M™ Scotch-Weld™ structural liquid adhesives (Epoxy, Acrylic, and Urethane) as essential solutions across demanding industrial sectors.
- In 2023, H.B. Fuller Company introduced Swiftmelt 1515-I, a bio-compatible liquid hot melt adhesive (a type of liquid adhesive when applied) compliant for the IMEA region (India, Middle East, Africa), underscoring a commitment to bio-based and environmentally responsible solutions to meet growing consumer and regulatory demand.
- In 2023, Bostik SA (Arkema Group) did the acquisition of Polytec PT. This move immediately expanded Bostik's liquid adhesives portfolio to include highly specialized materials, such as thermally and electrically conductive liquid adhesives
Report Coverage
The research report offers an in-depth analysis based on Formulation, Substrate, End-Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will grow steadily with rising demand in packaging and construction.
- Water-based adhesives will continue to replace solvent-based products.
- Automotive and transportation will drive adoption through lightweight material bonding.
- Healthcare applications will expand due to rising medical device production.
- Asia Pacific will maintain leadership with strong industrial and consumer demand.
- Technological innovations will enhance performance in electronics and high-stress uses.
- E-commerce growth will strengthen packaging adhesive consumption worldwide.
- Regulatory support will accelerate eco-friendly adhesive adoption across regions.
- Volatile raw material prices will influence production and pricing strategies.
- Strategic partnerships and R&D investments will shape competitive positioning.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Demand from Packaging Industry
The surge in e-commerce and consumer goods sectors is fueling the need for reliable, fast-curing liquid adhesives, especially for flexible and recyclable packaging solutions. Packaging accounts for the largest end-use share, anchoring overall market expansion.
Shift Toward Eco-Friendly Formulations
Stricter global regulations on VOC emissions and consumer preference for sustainable products are accelerating the adoption of water-based adhesives. These formulations offer safer handling and compliance benefits, driving their dominance over solvent-based alternatives.
Growth in Automotive and Transportation
Automotive manufacturers are increasingly using liquid adhesives to bond lightweight materials, replacing mechanical fasteners to improve fuel efficiency and performance. The rise of electric vehicles further amplifies demand for advanced, heat-resistant adhesive solutions.
Expansion in Healthcare and Medical Applications
The growing production of medical devices, wound care products, and wearables is boosting the use of biocompatible liquid adhesives. Rising healthcare expenditure and innovation in medical adhesives are opening new growth avenues beyond traditional industrial uses.
Technological Advancements in Adhesive Chemistries
Continuous R&D is leading to the development of high-performance adhesives with enhanced durability, flexibility, and resistance to heat and chemicals. These innovations are expanding the applicability of liquid adhesives in demanding sectors like electronics and construction.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Liquid Adhesives Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Liquid Adhesives Market projected to grow between 2025 and 2032?
Which Liquid Adhesives Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Liquid Adhesives Market?
Who are the leading companies in the Liquid Adhesives Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End Use
- 1.2.1 Automotive & Transportation
- 1.2.2 Building & Construction
- 1.2.3 Electronics
- 1.2.4 Packaging
- 1.2.5 Healthcare & Medical
- 1.2.6 Furniture
- 1.3 By Substrate
- 1.3.1 Metal
- 1.3.2 Plastic
- 1.3.3 Glass
- 1.3.4 Wood
- 1.4 By Formulation
- 1.4.1 Water-based
- 1.4.2 Solvent-based
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 42.15 billion → 2032: USD 52.78 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Liquid Adhesives Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Liquid Adhesives Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Liquid Adhesives Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Liquid Adhesives Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Liquid Adhesives Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Liquid Adhesives Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Liquid Adhesives Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Liquid Adhesives Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 42.15 billion → 2032: USD 52.78 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Liquid Adhesives Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End Use - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Automotive & Transportation
- 12.3.7.2 Building & Construction
- 12.3.7.3 Electronics
- 12.3.7.4 Packaging
- 12.3.7.5 Healthcare & Medical
- 12.3.7.6 Furniture
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Substrate - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Metal
- 12.4.7.2 Plastic
- 12.4.7.3 Glass
- 12.4.7.4 Wood
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Formulation - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Water-based
- 12.5.7.2 Solvent-based
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Liquid Adhesives End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Liquid Adhesives Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Liquid Adhesives Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Liquid Adhesives Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 3M Company
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Henkel AG & Co. KGaA
- 18.4 Dow Inc.
- 18.5 H.B. Fuller Company
- 18.6 Bostik SA
- 18.7 Avery Dennison Corporation
- 18.8 Huntsman Corporation
- 18.9 Pidilite Industries Ltd.
- 18.10 DIC Corporation
- 18.11 Beardow Adams
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

