
Lithium ion Battery Electrolyte Solvent Market Overview:
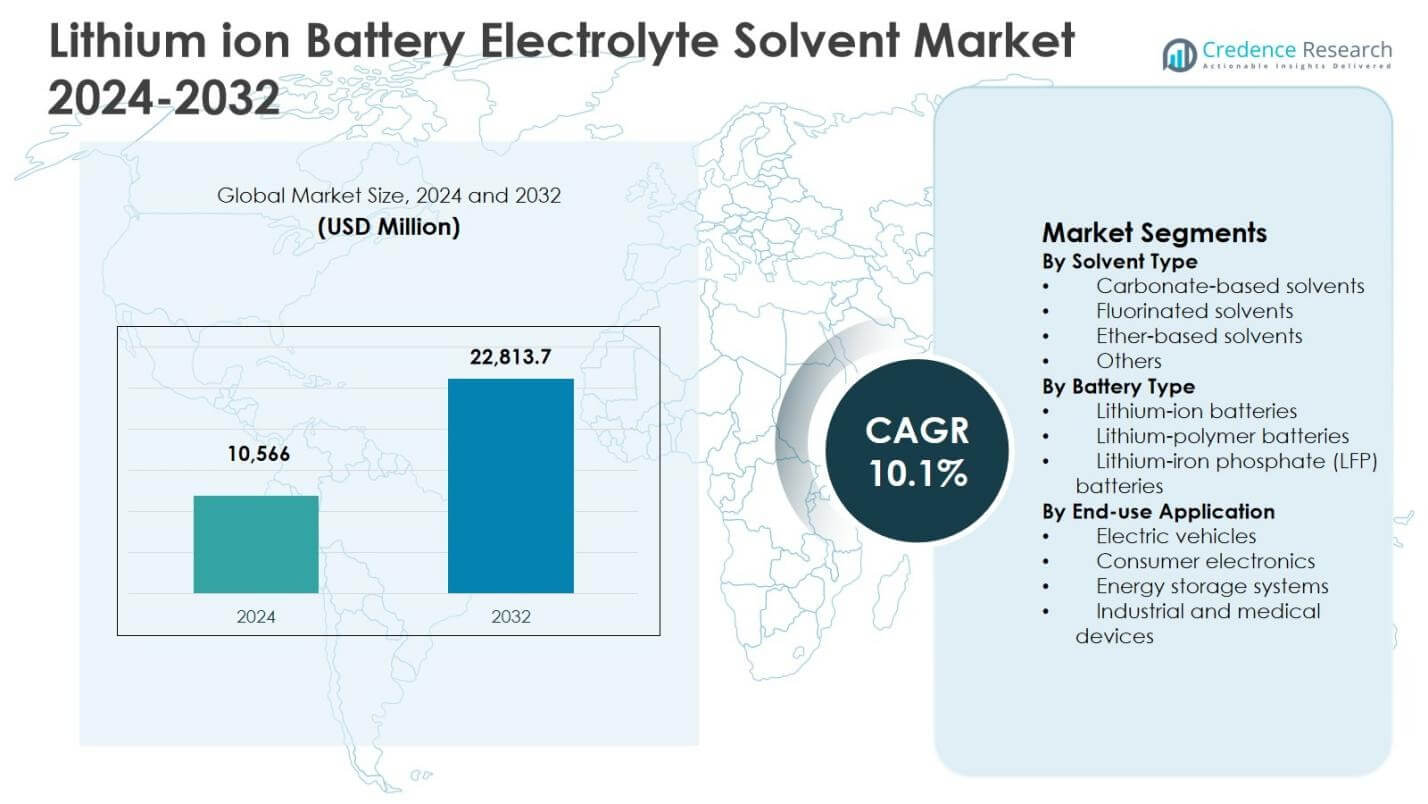
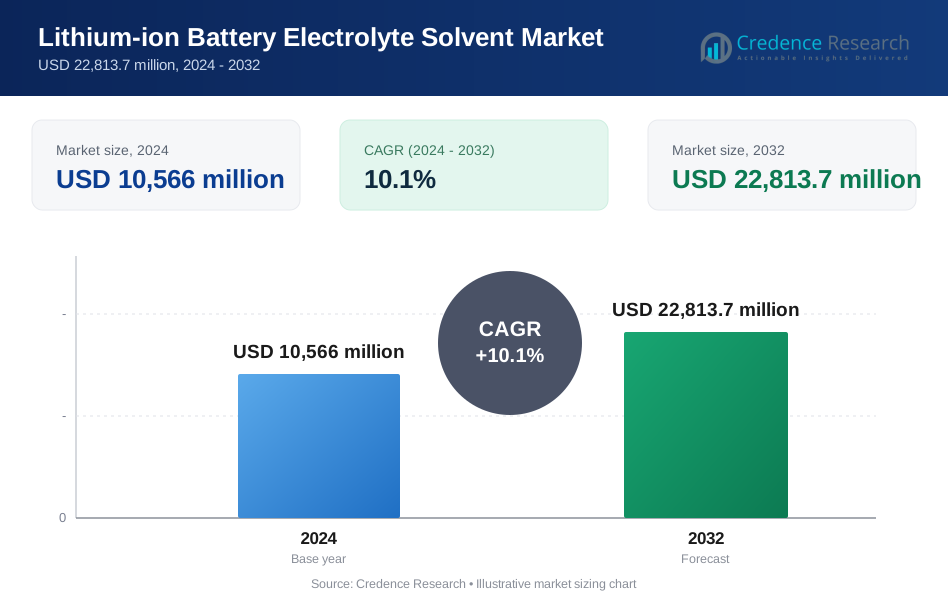
Lithium ion Battery Electrolyte Solvent Market size was valued at USD 10,566 million in 2024 and is anticipated to reach USD 22,813.7 million by 2032, growing at a CAGR of 10.1% during the forecast period.| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Lithium ion Battery Electrolyte Solvent Market Size 2024 | USD 10,566 million |
| Lithium ion Battery Electrolyte Solvent Market, CAGR | 10.1% |
| Lithium ion Battery Electrolyte Solvent Market Size 2032 | USD 22,813.7 million |
Lithium ion Battery Electrolyte Solvent Market Insights
- Market growth is driven by rapid electric vehicle adoption, expansion of battery gigafactories, and increasing installation of energy storage systems, which collectively raise demand for high-purity carbonate and specialty electrolyte solvents.
- Carbonate-based solvents dominated with 4% segment share in 2024, followed by fluorinated solvents at 18.9% and ether-based and others at 12.7%, reflecting strong preference for stable, high-conductivity solvent systems.
- Industry structure is shaped by emphasis on solvent purity, long-term supply contracts, and R&D focus on high-voltage and fast-charging electrolyte formulations to meet evolving battery performance requirements.
- Asia Pacific led with 6% regional share in 2024, followed by North America at 21.4%, Europe at 18.7%, Latin America at 7.4%, and Middle East & Africa at 4.9%, highlighting strong regional concentration of battery manufacturing.
Lithium ion Battery Electrolyte Solvent Market Segmentation Analysis:
By Solvent Type:
In the Lithium ion Battery Electrolyte Solvent Market, carbonate-based solvents dominated the segment, accounting for 68.4% market share in 2024, driven by their high dielectric constant, superior ionic conductivity, and stable electrochemical performance across a wide temperature range. Ethylene carbonate and dimethyl carbonate are extensively used due to their ability to enhance battery safety and energy density. Fluorinated solvents followed with 18.9% share, supported by demand for high-voltage and fast-charging batteries, while ether-based and other solvents collectively held 12.7% share, primarily used in niche and emerging battery chemistries.
- For instance, UBE Corporation manufactures dimethyl carbonate (DMC) using proprietary synthesis technology for its POWERLYTE electrolytes, enabling high conductivity in lithium-ion batteries for EVs and electronics.
By Battery Type:
By battery type, lithium-ion batteries held the dominant position with a 72.6% market share in 2024, supported by large-scale adoption in electric vehicles, consumer electronics, and stationary energy storage systems. The widespread commercial maturity, high energy density, and long cycle life of lithium-ion batteries continue to drive solvent demand. Lithium-iron phosphate batteries accounted for 19.3% share, benefiting from safety advantages and growing use in electric buses and grid storage, while lithium-polymer batteries captured the remaining 8.1% share, mainly in compact electronic devices.
- For instance, Shenzhen Grepow Battery produces lithium-polymer batteries for consumer electronics like drones and wearables, emphasizing high energy density and compact design.
By End-use Application:
Based on end-use application, electric vehicles emerged as the leading segment, capturing 44.8% market share in 2024, driven by accelerating EV penetration, battery capacity expansion, and government-led electrification initiatives. Consumer electronics followed with 29.6% share, supported by sustained demand for smartphones, laptops, and wearables requiring high-performance batteries. Energy storage systems accounted for 18.2% share, fueled by renewable integration and grid stabilization needs, while industrial and medical devices together contributed 7.4% share, reflecting steady but specialized demand patterns.
Key Growth Drivers
Rapid Expansion of Electric Vehicle Production
The accelerating adoption of electric vehicles remains a primary growth driver for the Lithium ion Battery Electrolyte Solvent Market. Rising EV production volumes directly increase demand for high-purity carbonate and fluorinated solvents used in lithium-ion batteries. Automakers continue to invest in higher-capacity battery packs to improve driving range, which raises electrolyte consumption per vehicle. Government incentives, emission-reduction mandates, and investments in EV charging infrastructure further support large-scale battery manufacturing. As battery energy density and fast-charging requirements intensify, solvent formulations with superior ionic conductivity and thermal stability are increasingly preferred, strengthening long-term market growth.
- For instance, Mitsubishi Chemical produces Sol-Rite™ electrolytes featuring ethylene carbonate and LiPF6 salts for EV lithium-ion batteries, incorporating additives that improve power output, lifetime, and safety by controlling solid electrolyte interfaces.
Growth of Energy Storage Systems
The expanding deployment of energy storage systems significantly drives demand in the Lithium ion Battery Electrolyte Solvent Market. Grid-scale storage projects supporting renewable energy integration require large battery installations, increasing electrolyte solvent consumption. Utility companies and commercial users are investing in lithium-ion storage to manage peak demand, stabilize grids, and enhance energy security. These applications demand solvents that ensure long cycle life and stable electrochemical performance under continuous operation. The steady expansion of residential, commercial, and utility-scale storage systems is reinforcing consistent solvent demand across both developed and emerging markets.
- For instance, LG Energy Solution Vertech secured contracts for 10 grid-scale lithium-ion battery storage projects totaling 10 GWh in the US in 2024, using their containerized LFP battery solutions integrated with AEROS software for grid stability.
Rising Demand from Consumer Electronics
Sustained demand for consumer electronics continues to support growth in the Lithium ion Battery Electrolyte Solvent Market. Smartphones, laptops, tablets, wearables, and smart home devices rely on compact, high-energy-density lithium-ion batteries that require reliable electrolyte solvents. Product innovation cycles remain short, driving continuous battery upgrades and solvent consumption. Manufacturers prioritize solvents that improve safety, charging speed, and device longevity. Increasing digitalization, remote working trends, and rising disposable income in developing economies further contribute to stable demand for electrolyte solvents in consumer electronics applications.
Key Trends & Opportunities
Development of High-Voltage and Fast-Charging Electrolytes
A key trend shaping the Lithium ion Battery Electrolyte Solvent Market is the development of advanced solvents for high-voltage and fast-charging batteries. Battery manufacturers are increasingly adopting fluorinated and specialty solvents to improve oxidation stability and reduce degradation at higher voltages. This trend creates opportunities for chemical producers to develop differentiated, high-margin solvent formulations. As fast-charging becomes a standard requirement in electric vehicles and portable electronics, demand for next-generation electrolyte solvents with enhanced safety and thermal performance is expected to expand significantly.
- For instance, Mitsubishi Chemical's Sol-Rite formulated electrolytes incorporate organic solvents and additives to optimize solid electrolyte interfaces on cathodes and anodes. These enable stable operation in lithium-ion batteries, enhancing performance and safety through patented technologies for high-voltage compatibility.
Shift Toward Safer and Sustainable Solvent Formulations
The growing focus on battery safety and sustainability presents strong opportunities in the Lithium ion Battery Electrolyte Solvent Market. Manufacturers are investing in low-flammability, high-purity solvents to reduce fire risks and improve environmental compliance. Regulatory pressure to minimize hazardous materials is encouraging innovation in greener solvent alternatives and improved recycling compatibility. Companies offering solvents with reduced toxicity and improved lifecycle performance can gain a competitive advantage, particularly as sustainability becomes a key purchasing criterion for battery and automotive manufacturers.
- For instance, Sepion Technologies developed an AI-driven non-flammable liquid electrolyte with a flash point exceeding 70°C and self-extinguishing time 25 times better than standard commercial lithium-ion electrolytes, reducing fire risks in EV batteries.
Key Challenges
Volatility in Raw Material Prices
Raw material price volatility remains a significant challenge for the Lithium ion Battery Electrolyte Solvent Market. Key solvent precursors are derived from petrochemical feedstocks, which are subject to fluctuations in crude oil prices and supply disruptions. Sudden cost increases directly impact production margins and pricing stability for solvent manufacturers. Long-term supply contracts and vertical integration can mitigate risks, but smaller players often face margin pressure. This volatility complicates cost forecasting and limits pricing flexibility in a highly competitive market environment.
Stringent Quality and Purity Requirements
Meeting stringent quality and purity standards poses another major challenge in the Lithium ion Battery Electrolyte Solvent Market. Even trace impurities can negatively affect battery performance, safety, and lifespan, requiring advanced purification processes and strict quality control. These requirements increase production complexity and capital investment. Compliance with evolving safety and regulatory standards across different regions further adds to operational costs. Manufacturers must continuously upgrade processing technologies to meet battery-grade specifications, which can limit entry for new players and constrain short-term profitability.
Regional Analysis
Asia Pacific
Asia Pacific dominated the Lithium ion Battery Electrolyte Solvent Market with a 47.6% market share in 2024, supported by large-scale lithium-ion battery manufacturing in China, Japan, and South Korea. The region benefits from a strong presence of battery cell producers, extensive EV production capacity, and government-backed electrification initiatives. Rising investments in gigafactories and energy storage projects further strengthen solvent demand. Additionally, rapid growth in consumer electronics manufacturing sustains high consumption of carbonate-based solvents, while ongoing R&D in advanced battery chemistries supports long-term regional market expansion.
North America
North America accounted for 21.4% market share in 2024, driven by expanding electric vehicle production, increasing battery manufacturing capacity, and strong investment in energy storage systems. The United States leads regional growth with rising adoption of EVs and grid-scale battery installations. Federal incentives supporting domestic battery supply chains are encouraging localized electrolyte solvent production. Demand is also supported by advanced research activities focused on high-performance and safer battery materials, reinforcing steady growth in solvent consumption across automotive and stationary storage applications.
Europe
Europe captured 18.7% market share in 2024, supported by stringent emission regulations, accelerating EV adoption, and strong policy support for renewable energy storage. Countries across the region are investing heavily in battery gigafactories to reduce reliance on imports, driving demand for high-purity electrolyte solvents. The market benefits from increasing focus on sustainability, recycling compatibility, and low-emission battery materials. Growth in electric mobility, coupled with rising renewable integration, continues to support consistent demand for advanced electrolyte solvent formulations across the region.
Latin America
Latin America held 7.4% market share in 2024, reflecting steady but developing demand for lithium-ion battery electrolyte solvents. Growth is primarily supported by gradual EV adoption, expanding renewable energy storage projects, and increasing use of consumer electronics. Countries such as Brazil and Chile are investing in energy transition initiatives, which indirectly support battery deployment. While battery manufacturing remains limited, rising imports of lithium-ion batteries and growing regional interest in localized production contribute to incremental solvent demand over the forecast period.
Middle East & Africa
The Middle East & Africa accounted for 4.9% market share in 2024, supported by emerging investments in renewable energy storage and gradual electrification initiatives. Utility-scale solar projects in the Middle East are increasingly paired with battery storage systems, driving electrolyte solvent demand. In Africa, growth is supported by expanding consumer electronics usage and pilot energy storage projects. Although the market remains at an early stage, government-led clean energy programs and infrastructure development are expected to support steady growth in battery-related solvent consumption.
Lithium ion Battery Electrolyte Solvent Market Segmentations:
By Solvent Type
- Carbonate-based solvents
- Fluorinated solvents
- Ether-based solvents
- Others
By Battery Type
- Lithium-ion batteries
- Lithium-polymer batteries
- Lithium-iron phosphate (LFP) batteries
By End-use Application
- Electric vehicles
- Consumer electronics
- Energy storage systems
- Industrial and medical devices
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Competitive landscape of the Lithium ion Battery Electrolyte Solvent Market is led by Mitsubishi Chemical Corporation, UBE INDUSTRIES LTD, LANXESS, Soulbrain Co., Ltd, and NEI Corporation. Competitive landscape analysis highlights a market characterized by strong emphasis on product purity, long-term supply agreements, and close collaboration with battery cell manufacturers. Leading players focus on expanding carbonate-based and fluorinated solvent portfolios to meet rising demand from electric vehicles and energy storage systems. Strategic investments in capacity expansion, backward integration, and advanced purification technologies are strengthening supply reliability and cost efficiency. Companies are also prioritizing R&D to develop high-voltage, fast-charging, and low-flammability solvent formulations to align with evolving battery performance requirements. Geographic expansion into Asia Pacific and North America, along with partnerships with gigafactory developers, continues to intensify competition while reinforcing long-term market positioning.
Key Player Analysis
- Cymbet (U.S.)
- LANXESS (Germany)
- Tracxn Technologies (India)
- Soulbrain Co., Ltd (South Korea)
- Beneq (Finland)
- Mitsubishi Chemical Corporation (Japan)
- NEI Corporation (U.S.)
- Statista Inc (Germany)
- Bureau van Dijk (Netherlands)
- UBE INDUSTRIES LTD (Japan)
Recent Developments
- In December 2025, Mitsubishi Chemical Corporation agreed to transfer its lithium-ion battery electrolyte manufacturing assets in the United States and the United Kingdom to Green E Origin SARL, marking a strategic shift in its Western operations and asset management in the electrolyte segment.
- In November 2025, Asahi Kasei licensed its novel acetonitrile-containing electrolyte technology to EAS Batteries for use in an ultra-high power lithium-ion battery cell, targeting marine, railway, and construction applications with a market launch planned by March 2026.
Report Coverage
The research report offers an in-depth analysis based on Solvent Type, Battery Type, End Use Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Lithium ion Battery Electrolyte Solvent Market will benefit from sustained growth in electric vehicle production and expanding battery manufacturing capacity.
- Increasing deployment of energy storage systems will continue to drive steady demand for high-purity electrolyte solvents.
- Carbonate-based solvents will remain dominant due to their proven performance and compatibility with mainstream lithium-ion chemistries.
- Adoption of fluorinated and specialty solvents will rise with the shift toward high-voltage and fast-charging batteries.
- Battery safety requirements will accelerate the development of low-flammability and thermally stable solvent formulations.
- Ongoing investments in battery gigafactories will strengthen long-term supply contracts for electrolyte solvent producers.
- Technological advancements in purification processes will improve product consistency and support premium-grade offerings.
- Regional supply chain localization will gain momentum to reduce dependency on imports and enhance resilience.
- Sustainability considerations will encourage innovation in environmentally compliant and recyclable solvent solutions.
- Strategic collaborations between chemical companies and battery manufacturers will shape product development and market positioning.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Lithium ion Battery Electrolyte Solvent Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Lithium ion Battery Electrolyte Solvent Market projected to grow between 2024 and 2032?
Which Lithium ion Battery Electrolyte Solvent Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Lithium ion Battery Electrolyte Solvent Market?
Who are the leading companies in the Lithium ion Battery Electrolyte Solvent Market?
Which region commanded the largest share of the Lithium ion Battery Electrolyte Solvent Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Lithium-ion Battery Electrolyte Solvent Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Lithium-ion Battery Electrolyte Solvent Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 10,566 million → 2032: USD 22,813.7 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Lithium-ion Battery Electrolyte Solvent Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Lithium-ion Battery Electrolyte Solvent Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Lithium-ion Battery Electrolyte Solvent Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Lithium-ion Battery Electrolyte Solvent Market Drivers
- 3.3 Lithium-ion Battery Electrolyte Solvent Market Restraints & Challenges
- 3.4 Lithium-ion Battery Electrolyte Solvent Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Lithium-ion Battery Electrolyte Solvent Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Lithium-ion Battery Electrolyte Solvent Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Lithium-ion Battery Electrolyte Solvent category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Lithium-ion Battery Electrolyte Solvent Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Lithium-ion Battery Electrolyte Solvent Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Lithium-ion Battery Electrolyte Solvent market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Lithium-ion Battery Electrolyte Solvent Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Lithium-ion Battery Electrolyte Solvent Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Lithium-ion Battery Electrolyte Solvent Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Lithium-ion Battery Electrolyte Solvent (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Lithium-ion Battery Electrolyte Solvent Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Lithium-ion Battery Electrolyte Solvent Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Lithium-ion Battery Electrolyte Solvent Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Lithium-ion Battery Electrolyte Solvent Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Lithium-ion Battery Electrolyte Solvent Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Lithium-ion Battery Electrolyte Solvent Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Lithium-ion Battery Electrolyte Solvent Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Lithium-ion Battery Electrolyte Solvent Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Lithium-ion Battery Electrolyte Solvent Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
