
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Low Power ASIC Design Market Size 2024 | USD 15,680.65 million |
| Low Power ASIC Design Market, CAGR | 9.77% |
| Low Power ASIC Design Market Size 2032 | USD 34,816.54 million |
Market Overview:
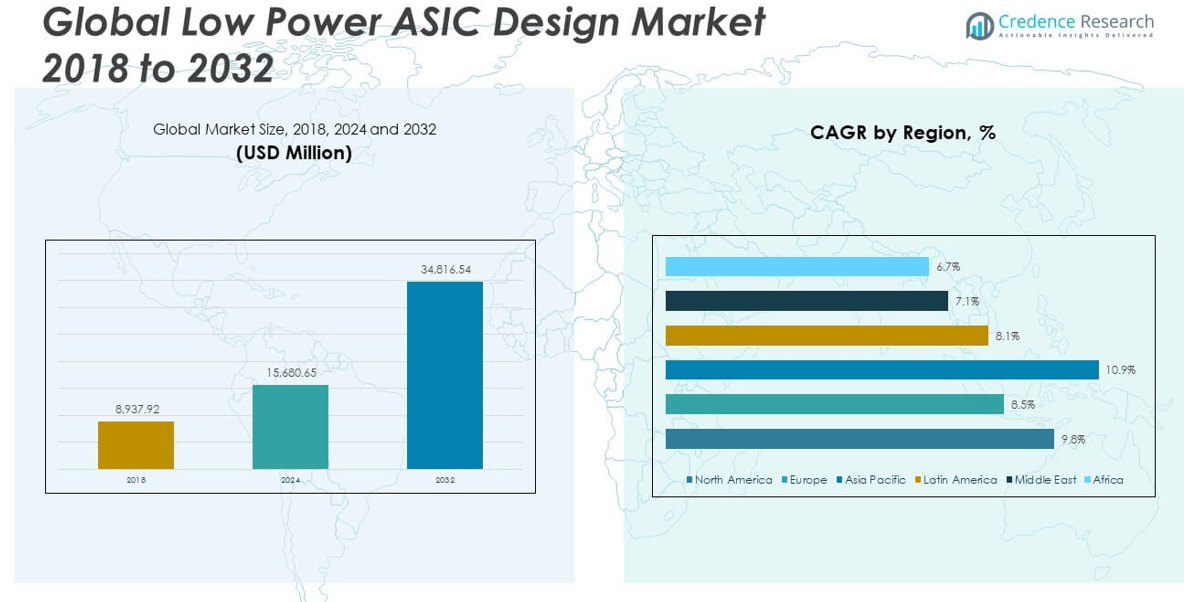
The Global Low Power ASIC Design Market size was valued at USD 8,937.92 million in 2018 to USD 15,680.65 million in 2024 and is anticipated to reach USD 34,816.54 million by 2032, at a CAGR of 9.77% during the forecast period.
Several key drivers are propelling the growth of the low power ASIC design market. The most prominent is the accelerating demand for energy-efficient electronics due to the proliferation of battery-powered and portable devices. As edge computing, wearables, and smart home technologies gain traction, manufacturers are turning to low power ASICs to optimize system performance while extending operational lifespans. Additionally, the deployment of 5G networks and AI-based workloads is increasing the need for specialized, power-efficient chips that can handle high-speed data processing with minimal energy draw. The transition toward advanced semiconductor nodes, such as 7nm and below, further enables designers to reduce power consumption at the transistor level. Moreover, advancements in electronic design automation (EDA) tools enhanced by AI are streamlining the low power design process, making it more accessible and cost-effective for companies to develop customized chips tailored to specific end-user applications.
Regionally, Asia Pacific dominates the global low power ASIC design market, capturing the largest share due to its strong electronics manufacturing base and significant investments in semiconductor fabrication. Countries like China, Taiwan, South Korea, and Japan lead in volume production, while India is emerging rapidly through initiatives such as the Semicon India Program, aimed at boosting domestic chip design capabilities. North America follows closely, driven by innovation-led demand and technological leadership from companies like Intel, Qualcomm, and Texas Instruments. Europe, although smaller in market share, is experiencing steady growth led by the automotive sector, industrial automation, and defense applications-particularly in Germany, the UK, and France. Meanwhile, Latin America and the Middle East & Africa represent emerging regions with growing demand for energy-efficient chips to support digital transformation in telecommunications, infrastructure, and manufacturing.
Market Insights:
- The Global Low Power ASIC Design Market was valued at USD 15,680.65 million in 2024 and is projected to reach USD 34,816.54 million by 2032, expanding at a CAGR of 9.77%.
- Increasing demand for energy-efficient electronics in consumer and industrial applications is accelerating adoption of low power ASICs, especially in smartphones, wearables, and smart appliances.
- The rapid expansion of IoT and edge computing is driving the need for customized ASICs with ultra-low power profiles, replacing traditional microcontrollers in distributed networks.
- AI and 5G deployment are creating a shift toward specialized architectures, where low power ASICs deliver concurrent high-speed processing with minimal thermal load.
- Advanced semiconductor nodes, such as 7nm and below, paired with AI-enhanced EDA tools, are helping designers reduce power at the transistor level while optimizing performance.
- Design complexity, high development costs, and limited access to advanced nodes remain key challenges, particularly for smaller firms and startups.
- Asia Pacific dominates the market with the highest share, followed by North America and Europe, while Latin America, the Middle East, and Africa are emerging with growing low power chip demand.
Market Drivers:
Rising Demand for Energy-Efficient Electronics Across Consumer and Industrial Applications
The increasing emphasis on energy efficiency in electronic devices is a core driver of the Global Low Power ASIC Design Market. Devices such as smartphones, wearables, and portable medical instruments require extended battery life, making low power consumption a critical design priority. The growth of the smart home ecosystem and personal electronics has accelerated the adoption of ASICs that deliver high performance without draining power. Manufacturers seek to minimize heat generation and energy usage to enhance user experience and meet regulatory energy standards. Industrial equipment also benefits from low power ASICs in remote monitoring and control systems where energy supply is limited. It has become essential for OEMs to integrate low power designs to remain competitive in a power-conscious global electronics market.
- For example, MegaChips Corporation has implemented fully depleted silicon-on-insulator (FD-SOI) technology in its ASICs, which suppresses leakage current and achieves significant power savings. Their FD-SOI-based ASICs are tailored for IoT and portable medical devices, delivering up to 50% reduction in static power consumption compared to conventional bulk CMOS designs, according to their product documentation.
Proliferation of IoT and Edge Devices Fueling Custom Low Power Chip Requirements
The exponential rise in IoT deployments across sectors such as healthcare, agriculture, and logistics has created strong demand for customized low power ASICs. Billions of connected devices operate in environments where energy efficiency and compact form factor are crucial. IoT sensors and edge computing modules rely on ASICs to execute tasks with minimal power draw, enabling longer deployment cycles and reduced maintenance. The Global Low Power ASIC Design Market continues to gain traction due to its ability to offer application-specific solutions for distributed and energy-constrained networks. These chips often replace generic microcontrollers, reducing system complexity while enhancing operational stability. Design service providers are expanding their portfolios to meet the growing preference for device-specific power-optimized silicon.
Emergence of AI and 5G Accelerating the Shift Toward Specialized Low Power Architectures
AI and 5G technologies are reshaping hardware requirements, pushing the Global Low Power ASIC Design Market toward more efficient and domain-specific architectures. AI accelerators in smartphones, surveillance devices, and autonomous vehicles require processing power that traditional general-purpose processors cannot deliver within a power budget. Low power ASICs meet this need by enabling concurrent, high-speed computations with controlled energy use. In 5G infrastructure, baseband and RF components demand compact and thermally efficient designs to handle constant data flow. It enables network equipment and devices to sustain peak operations without excessive power costs. The convergence of AI and connectivity is reinforcing the need for integrated, low power chipsets.
- For instance, Google’s Tensor Processing Unit (TPU), a custom ASIC, delivers 15–30 TOPS (Tera Operations Per Second) at under 10Wfor AI workloads, a significant improvement over general-purpose processor.
Advancements in Semiconductor Manufacturing and EDA Tools Supporting Low Power Innovation
Progress in semiconductor fabrication processes has enabled more compact and power-efficient chip designs, significantly benefiting the Global Low Power ASIC Design Market. Foundries now offer sub-7nm nodes that support higher transistor density with lower switching power. This advancement allows designers to reduce energy consumption while maintaining or improving computational throughput. Electronic design automation (EDA) tools have also evolved, incorporating machine learning algorithms that automate power optimization during early design stages. It reduces the time and cost associated with achieving low power goals in custom ASIC development. The synergy between cutting-edge process nodes and AI-enhanced EDA is strengthening the competitive edge of low power ASIC solutions.
Market Trends:
Increased Focus on Chiplet-Based Architectures for Modular Power Efficiency
Chiplet-based design is gaining momentum as a viable approach to improving power efficiency in complex ASIC systems. By breaking down monolithic system-on-chip (SoC) designs into smaller functional modules, manufacturers can optimize each chiplet for specific power and performance requirements. This trend allows designers to mix and match chiplets fabricated on different process nodes, enabling cost control while meeting power constraints. The Global Low Power ASIC Design Market is seeing greater interest in chiplet integration, particularly for applications that require flexible scalability and power segmentation. It improves thermal management by isolating high-power functions from critical low-power logic. Adoption is rising in AI servers, data center hardware, and advanced consumer devices.
- For example, Cadence reports that chiplet architectures enables reduction in power consumption compared to traditional monolithic SoC approaches, primarily by allowing each chiplet to be optimized for its specific workload and fabricated on the most suitable process node.
Growing Use of Open-Source Hardware Platforms to Accelerate Low Power Innovation
Open-source hardware frameworks such as RISC-V are transforming ASIC design by enabling transparent collaboration and rapid customization. These platforms offer companies the freedom to develop low power processors without licensing constraints tied to proprietary architectures. The trend is lowering entry barriers for startups and mid-sized design firms seeking cost-efficient innovation in low power ASICs. It supports a growing ecosystem of design tools, IP libraries, and community-backed testing resources that shorten development cycles. The Global Low Power ASIC Design Market benefits from this shift by welcoming new entrants and expanding its innovation capacity. It helps promote diversity in design strategies focused on reducing power consumption across a wide range of applications.
- For example, companies like CSEM and SiFive have published detailed technical metrics on their RISC-V-based ASICs, demonstrating significant power savings. CSEM’s custom RISC-V core, implemented in a 22nm process, achieves 2.23 μW/MHz and 3.2 CoreMark/MHz, making it suitable for battery-powered, autonomously operated devices.
Integration of Security Features Directly into Low Power ASIC Fabric
Security is becoming an integral part of ASIC design, especially in low power environments where data integrity and system protection must coexist with energy efficiency. Designers are embedding lightweight encryption engines, secure boot protocols, and tamper-detection logic directly into ASICs to eliminate reliance on separate, power-hungry security chips. This trend addresses rising concerns over IoT vulnerabilities and edge computing threats. The Global Low Power ASIC Design Market is aligning with this demand by supporting integrated security features tailored to constrained power budgets. It helps protect connected devices without sacrificing battery life or performance. Chipmakers now consider power-aware security a critical differentiator in competitive markets.
Increased Collaboration Between Design Houses and Foundries for Power-Tuned Manufacturing
Close partnerships between ASIC design service providers and semiconductor foundries are reshaping manufacturing workflows to prioritize power optimization. These collaborations allow designers to access process-specific design kits and low power IP libraries tailored to the foundry’s latest nodes. The Global Low Power ASIC Design Market is benefiting from this alignment, which ensures that power targets are met consistently from design through fabrication. It enables early identification of leakage issues, switching inefficiencies, and layout-induced power anomalies. By involving foundries in the early stages of custom chip development, companies achieve better power-performance trade-offs. This trend supports faster time-to-market for complex, energy-sensitive devices.
Market Challenges Analysis:
High Design Complexity and Resource Constraints in Achieving Low Power Targets
The growing demand for custom ASICs with ultra-low power consumption introduces significant design complexity. Meeting power budgets while maintaining performance, area efficiency, and functional integrity requires advanced knowledge of architectural trade-offs and process-specific optimizations. The Global Low Power ASIC Design Market faces constant pressure to balance stringent energy goals with design feasibility and time-to-market expectations. It demands extensive simulation, verification, and iteration cycles, which increase design cost and delay product launches. Smaller companies and startups often struggle to access the necessary talent, tools, and IP blocks required for power-aware design. These constraints limit market participation and innovation despite rising end-user demand.
Limited Access to Advanced Nodes and High Costs of Fabrication
Advanced semiconductor nodes such as 5nm and 3nm offer substantial power efficiency gains but remain financially inaccessible to many design houses. Only a few global foundries support these cutting-edge processes, leading to bottlenecks and long lead times for fabrication. The Global Low Power ASIC Design Market encounters hurdles when companies must compromise between ideal power performance and practical manufacturing constraints. It often forces firms to work on legacy nodes with less efficient power characteristics, reducing competitive advantage. Intellectual property licensing, verification tools, and EDA software costs further raise barriers for low-budget ASIC projects. Without scalable access to affordable manufacturing and design infrastructure, the market risks slower adoption in critical verticals.
Market Opportunities:
Expanding Demand from Emerging Technologies and Untapped Industry Verticals
The increasing adoption of wearable devices, medical implants, and smart agriculture systems presents new opportunities for custom low power ASIC solutions. These applications require ultra-efficient chips that can operate reliably with limited energy sources. The Global Low Power ASIC Design Market can capture significant value by tailoring solutions to meet specific functional and power requirements in these underserved segments. It allows designers to differentiate products and support specialized use cases where off-the-shelf components fall short. Market potential is also growing in industrial automation and environmental monitoring, where devices must sustain long operation cycles without external power. These sectors create a strong foundation for long-term revenue expansion.
Government Incentives and Localization of Semiconductor Ecosystems
Supportive government policies promoting domestic semiconductor design and manufacturing offer a favorable environment for low power ASIC innovation. Initiatives across Asia, Europe, and North America aim to strengthen chip sovereignty and reduce supply chain dependencies. The Global Low Power ASIC Design Market can benefit from grants, subsidies, and public-private partnerships that lower development barriers. It encourages local design firms to enter the market with region-specific solutions. Such policies also stimulate collaboration between academia, industry, and foundries, accelerating the pace of innovation. Localized ecosystems create more accessible pathways to market for power-optimized ASICs in both commercial and defense applications.
Market Segmentation Analysis:
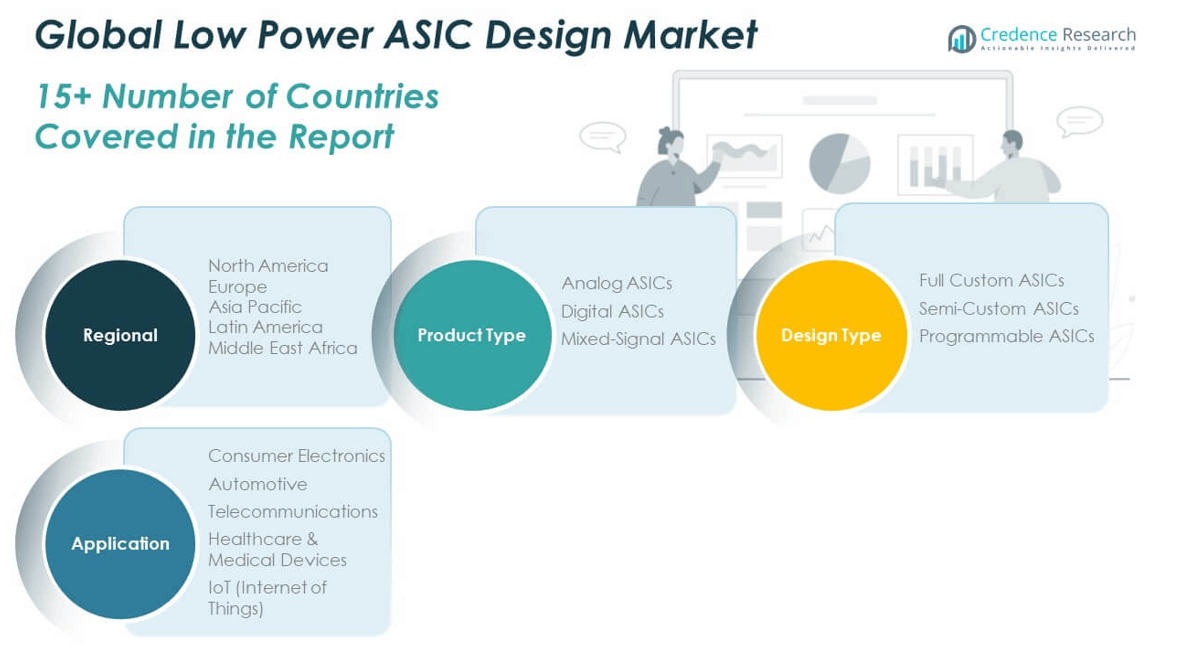
The Global Low Power ASIC Design Market is segmented by product type, design type, and application, each playing a vital role in driving market dynamics.
By product type, the market includes Analog ASICs, Digital ASICs, and Mixed-Signal ASICs. Digital ASICs dominate the segment due to their wide use in data processing, mobile devices, and AI applications, while Mixed-Signal ASICs are gaining traction in sensor integration and power management systems.
- For instance, Samsung’s Exynos 2100 SoC is a recent digital ASIC used in flagship smartphones, featuring an integrated AI engine capable of 26 TOPS (tera operations per second) while maintaining a 20% reduction in power consumption compared to the previous generation, as documented in Samsung’s technical release.
By design type, the market is classified into Full Custom ASICs, Semi-Custom ASICs, and Programmable ASICs. Full Custom ASICs offer high performance and low power consumption but require more design time, making them suitable for high-volume applications. Semi-Custom ASICs provide a balance between flexibility and efficiency, while Programmable ASICs serve low-volume, fast-turnaround needs.
By application, the Global Low Power ASIC Design Market serves Consumer Electronics, Automotive, Telecommunications, Healthcare & Medical Devices, Biotechnology, and IoT. Consumer Electronics remains the largest segment, followed by IoT and Automotive, reflecting the high demand for energy-efficient custom chips in smart and connected devices. It continues to evolve as each segment prioritizes lower power budgets and customized performance.
- For instance, NXP’s S32G2 automotive network processor is an ASIC designed for vehicle domain controllers. It features multiple Arm Cortex-A53 cores and dedicated accelerators for secure communication and safety, achieving up to 2.5x better performance-per-watt than previous generations, according to NXP’s product brief.
Segmentation:
By Product Type
- Analog ASICs
- Digital ASICs
- Mixed-Signal ASICs
By Design Type
- Full Custom ASICs
- Semi-Custom ASICs
- Programmable ASICs
By Application
- Consumer Electronics
- Automotive
- Telecommunications
- Healthcare & Medical Devices
- Biotechnology
- IoT (Internet of Things)
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America Low Power ASIC Design Market size was valued at USD 3,730.20 million in 2018 to USD 6,473.13 million in 2024 and is anticipated to reach USD 14,414.39 million by 2032, at a CAGR of 9.8% during the forecast period. North America accounts for the largest share of the Global Low Power ASIC Design Market, contributing approximately 25.8% of the global revenue in 2024. It benefits from strong demand for custom silicon in data centers, defense electronics, and advanced consumer technologies. Companies such as Intel, Qualcomm, and AMD continue to invest in low power design innovation across 5nm and sub-5nm nodes. Government funding and strategic partnerships are expanding the region’s R&D infrastructure and strengthening its competitive position. It remains a hub for AI accelerators, edge computing, and telecom hardware that rely on power-efficient ASIC architectures.
Europe
The Europe Low Power ASIC Design Market size was valued at USD 1,763.85 million in 2018 to USD 2,934.13 million in 2024 and is anticipated to reach USD 5,957.72 million by 2032, at a CAGR of 8.5% during the forecast period. Europe contributes nearly 11.7% to the Global Low Power ASIC Design Market and is steadily expanding due to the growth of automotive electronics and industrial IoT. Countries like Germany, France, and the Netherlands lead in designing power-optimized ASICs for electric vehicles, factory automation, and renewable energy systems. Regional initiatives under the European Chips Act support local semiconductor innovation, reducing dependence on foreign supply chains. It benefits from a well-established network of fabless design companies and academic institutions focused on low power technologies. The region continues to invest in secure, application-specific ASIC solutions with energy-saving features.
Asia Pacific
The Asia Pacific Low Power ASIC Design Market size was valued at USD 2,648.66 million in 2018 to USD 4,899.81 million in 2024 and is anticipated to reach USD 11,841.63 million by 2032, at a CAGR of 10.9% during the forecast period. Asia Pacific dominates the Global Low Power ASIC Design Market with a 39.1% share in 2024, driven by rapid industrialization and high-volume semiconductor manufacturing in China, Taiwan, South Korea, and Japan. The region is home to leading foundries such as TSMC and Samsung, which enable cutting-edge low power design capabilities. Consumer electronics, 5G infrastructure, and IoT device production remain key demand drivers. Governments are actively funding chip design programs and localizing supply chains to enhance design sovereignty. It plays a pivotal role in delivering high-performance, low-power ASICs to global OEMs.
Latin America
The Latin America Low Power ASIC Design Market size was valued at USD 431.11 million in 2018 to USD 747.13 million in 2024 and is anticipated to reach USD 1,472.28 million by 2032, at a CAGR of 8.1% during the forecast period. Latin America holds a 6.0% share in the Global Low Power ASIC Design Market and is gaining traction due to increasing digitization in smart city projects and industrial sectors. Brazil and Mexico lead the region with growing demand for power-efficient processors in telecom, automation, and surveillance applications. Government-backed tech incubators and academic partnerships support localized chip design efforts. It benefits from rising awareness around energy efficiency in electronics. Though still emerging, the region presents growth potential for ASIC vendors offering scalable, low power solutions.
Middle East
The Middle East Low Power ASIC Design Market size was valued at USD 225.54 million in 2018 to USD 357.95 million in 2024 and is anticipated to reach USD 655.51 million by 2032, at a CAGR of 7.1% during the forecast period. The Middle East represents a 1.4% share of the Global Low Power ASIC Design Market and shows promising signs of growth due to investments in digital infrastructure and smart energy projects. Countries like the UAE and Saudi Arabia are deploying IoT networks, automated grid systems, and surveillance platforms that require power-efficient silicon. Regional interest in data security and AI integration is also stimulating demand for custom ASICs. It is gradually building semiconductor design capabilities through strategic collaborations and foreign direct investment. Limited local fabrication facilities remain a challenge, but design service adoption is expanding.
Africa
The Africa Low Power ASIC Design Market size was valued at USD 138.56 million in 2018 to USD 268.50 million in 2024 and is anticipated to reach USD 475.00 million by 2032, at a CAGR of 6.7% during the forecast period. Africa contributes around 1.1% to the Global Low Power ASIC Design Market and is in the early stages of development. Countries such as South Africa, Nigeria, and Kenya are witnessing digital transformation across education, healthcare, and energy sectors. Growing demand for mobile connectivity and solar-powered IoT devices is increasing the need for energy-efficient semiconductors. It faces challenges such as limited semiconductor infrastructure and access to design talent. International partnerships and educational initiatives are helping nurture the region’s emerging ASIC ecosystem. Africa holds long-term potential for low power ASIC applications in off-grid and resource-constrained environments.
Key Player Analysis:
- TSMC (Taiwan Semiconductor Manufacturing Company)
- Intel Corporation
- Qualcomm Incorporated
- NVIDIA Corporation
- Broadcom Inc.
- Advanced Micro Devices (AMD)
- Analog Devices Inc.
- MediaTek Inc.
- STMicroelectronics
- Xilinx
Competitive Analysis:
The Global Low Power ASIC Design Market features a competitive landscape dominated by semiconductor giants and specialized design service providers. Leading players such as Intel Corporation, Qualcomm Technologies Inc., Taiwan Semiconductor Manufacturing Company (TSMC), Samsung Electronics, and Broadcom Inc. invest heavily in R&D to enhance performance while minimizing power consumption. It also includes fabless companies and IP providers like Arm Holdings and Synopsys, which support low power logic design through advanced toolchains and reusable core libraries. Startups and mid-sized firms focus on niche applications in wearables, IoT, and AI edge computing. Strategic partnerships between foundries and design houses are strengthening vertical integration and enabling faster time-to-market. It reflects a blend of global innovation leadership and regional design specialization, with competitive differentiation driven by power optimization capabilities, process node access, and cost-effective customization. The market continues to evolve as players prioritize energy efficiency and application-specific performance.
Recent Developments:
- In January 2025, MICROIP unveiled its Genio AI IoT platform and rapid design service at CES 2025. It showcased a new NFC controller chip capable of supporting payments, device pairing, and wireless charging. Developed in collaboration with MediaTek on TSMC’s 6 nm NPU node, the platform delivers low power consumption and swift time-to-market-transitioning from co-specification to production within 12 months.
- In February 2025, SEALSQ Corp entered into exclusive negotiations to acquire IC’ALPS SAS, a specialist in ASIC design and supply based in France. This strategic move is expected to combine IC’ALPS’ expertise in ultra-low power ASICs with SEALSQ’s security IP and supply chain capabilities, strengthening their position in the medical and automotive segments of the ASIC market.
- In July 2024, Avnet ASIC, a division of Avnet Silica, launched new ultra-low-power design services for TSMC’s 4nm and below process technologies. These services are tailored to help customers achieve outstanding power efficiency and performance for high-demand applications such as blockchain and edge AI computing. The offering includes advanced techniques for optimizing power, performance, and area trade-offs in ASIC design.
Market Concentration & Characteristics:
The Global Low Power ASIC Design Market exhibits moderate to high market concentration, with a few dominant players controlling a significant share of global revenues. It is characterized by high entry barriers due to the need for advanced design tools, skilled talent, and access to cutting-edge fabrication nodes. The market emphasizes customization, with companies focusing on application-specific solutions that balance performance and energy efficiency. It relies on long-term partnerships between design houses, IP vendors, and semiconductor foundries to streamline development and production. The industry favors firms capable of rapid prototyping, iterative design, and integration of low power features across diverse end-use sectors. Competitive advantage depends on innovation in architecture, access to proprietary design libraries, and efficient use of EDA software.
Report Coverage:
The research report offers an in-depth analysis based on product type, design type, and application. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising demand for edge AI and IoT devices will drive custom low power ASIC adoption across industrial and consumer applications.
- Advancements in sub-5nm and 3nm process nodes will enhance power efficiency and enable higher integration levels.
- Increased use of AI-powered EDA tools will streamline design workflows and reduce development time for energy-optimized chips.
- Chiplet-based architectures will gain traction, allowing modular low power solutions for complex systems.
- Open-source hardware platforms like RISC-V will lower entry barriers and support innovation in power-aware designs.
- Government incentives and semiconductor localization efforts will expand regional design capabilities.
- Integrated hardware-level security in ASICs will become standard in low power applications.
- Design outsourcing and foundry partnerships will grow, offering cost-effective access to advanced nodes.
- Demand from emerging sectors like wearable health tech and autonomous systems will expand use cases.
- Sustainability goals and energy regulations will further prioritize low power semiconductor strategies.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Demand for Energy-Efficient Electronics
The proliferation of battery-powered and portable devices, such as smartphones, wearables, and smart home appliances, is driving manufacturers to adopt low power ASICs to extend battery life and meet regulatory energy standards.
Expansion of IoT and Edge Computing
The rapid growth of IoT deployments and edge computing applications requires customized ASICs with ultra-low power profiles, replacing traditional microcontrollers and enabling longer device lifespans in distributed networks.
AI and 5G Deployment
The rollout of 5G networks and AI-based workloads is increasing the need for specialized, power-efficient chips that can handle high-speed data processing with minimal energy consumption, fueling demand for low power ASICs.
Advancements in Semiconductor Nodes and EDA Tools
The transition to advanced semiconductor nodes (7nm and below) and the integration of AI-enhanced electronic design automation (EDA) tools are enabling designers to achieve lower power consumption at the transistor level, making low power ASIC design more accessible and cost-effective.
Government Incentives and Localization Initiatives
Supportive government policies and programs aimed at boosting domestic semiconductor design and manufacturing are lowering barriers to entry, encouraging local innovation, and expanding the market for low power ASICs in various regions.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Global Low Power ASIC Design Market?
What are the key segments within the Global Low Power ASIC Design Market?
What are some challenges faced by the Global Low Power ASIC Design Market?
Who are the major players in the Global Low Power ASIC Design Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Application
- 1.2.1 Consumer Electronics
- 1.2.2 Automotive
- 1.2.3 Telecommunications
- 1.2.4 Healthcare & Medical Devices
- 1.2.5 Biotechnology
- 1.2.6 IoT (Internet of Things)
- 1.3 By Design Type
- 1.3.1 Full Custom ASICs
- 1.3.2 Semi-Custom ASICs
- 1.3.3 Programmable ASICs
- 1.4 By Product Type
- 1.4.1 Analog ASICs
- 1.4.2 Digital ASICs
- 1.4.3 Mixed-Signal ASICs
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 15,680.65 million → 2032: USD 34,816.54 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Low Power ASIC Design Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Low Power ASIC Design Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Low Power ASIC Design Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Low Power ASIC Design Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Low Power ASIC Design Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Low Power ASIC Design Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Low Power ASIC Design Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Low Power ASIC Design Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 15,680.65 million → 2032: USD 34,816.54 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Low Power ASIC Design Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Application - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Consumer Electronics
- 12.3.7.2 Automotive
- 12.3.7.3 Telecommunications
- 12.3.7.4 Healthcare & Medical Devices
- 12.3.7.5 Biotechnology
- 12.3.7.6 IoT (Internet of Things)
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Design Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Full Custom ASICs
- 12.4.7.2 Semi-Custom ASICs
- 12.4.7.3 Programmable ASICs
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Analog ASICs
- 12.5.7.2 Digital ASICs
- 12.5.7.3 Mixed-Signal ASICs
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Low Power ASIC Design End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Low Power ASIC Design Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Low Power ASIC Design Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Low Power ASIC Design Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 TSMC (Taiwan Semiconductor Manufacturing Company)
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Intel Corporation
- 18.4 Qualcomm Incorporated
- 18.5 NVIDIA Corporation
- 18.6 Broadcom Inc.
- 18.7 Advanced Micro Devices (AMD)
- 18.8 Analog Devices Inc.
- 18.9 MediaTek Inc.
- 18.10 STMicroelectronics
- 18.11 Xilinx
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

