
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
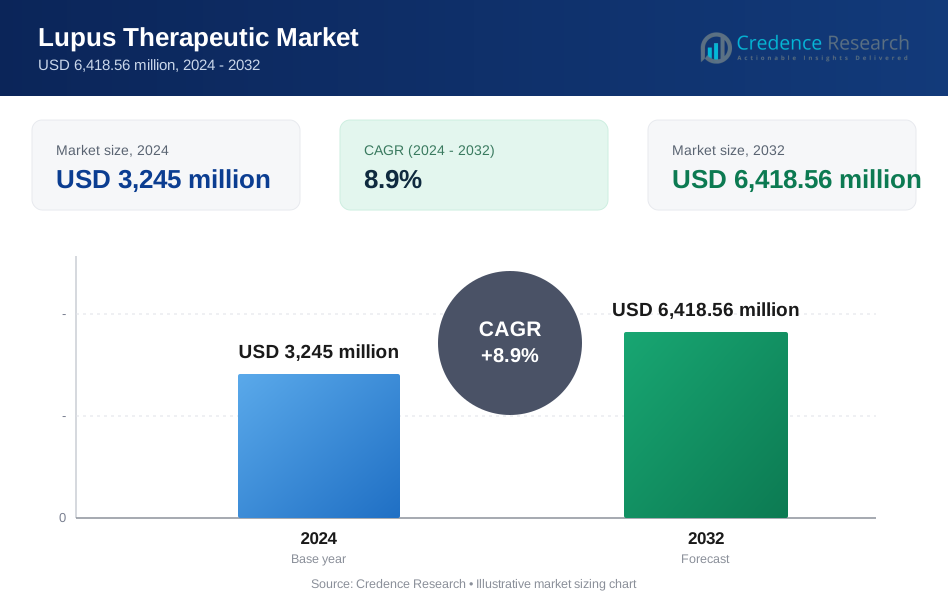
| Lupus Therapeutic Market Size 2024 | USD 3,245 Million |
| Lupus Therapeutic Market, CAGR | 8.9% |
| Lupus Therapeutic Market Size 2032 | USD 6,418.56 Million |
Market Overview:
The Lupus Therapeutic Market is poised for robust growth, projected to increase from USD 3,245 million in 2024 to USD 6,418.56 million by 2032, representing a compound annual growth rate (CAGR) of 8.9%. This expansion is largely driven by rising prevalence rates of systemic lupus erythematosus (SLE) and other lupus forms, coupled with growing awareness about the disease and its impacts. As the demand for more effective and targeted therapies rises, the market is expected to benefit from advancements in biotechnology and a broader focus on innovative treatment options, including biologics and immunosuppressive agents.
Several factors are driving the growth of the lupus therapeutic market. Increasing healthcare expenditures, alongside improved diagnostic techniques, have enabled earlier and more accurate diagnoses of lupus, leading to a greater need for effective treatments. Additionally, rising investment in research and development by pharmaceutical companies has led to a growing pipeline of potential lupus treatments, particularly in the biologics segment. Supportive government initiatives and collaborations between private and public sectors also play a significant role, as they provide essential funding and resources to accelerate the development and accessibility of advanced lupus treatments. Patient advocacy groups have further enhanced market growth by increasing public awareness and promoting clinical trials, which contribute to the introduction of innovative therapies.
Regionally, North America dominates the lupus therapeutic market, accounting for the largest share due to its advanced healthcare infrastructure, high disease prevalence, and strong investment in R&D. The United States, in particular, leads this growth, driven by a high incidence of lupus, widespread access to cutting-edge therapies, and an increasing number of clinical trials. Europe follows closely, with significant contributions from countries like the United Kingdom, Germany, and France, where the growing demand for targeted biologics is fostering market expansion. Meanwhile, the Asia-Pacific region is expected to witness the fastest growth, fueled by a large population base, rising healthcare spending, and improved healthcare access in countries such as China, India, and Japan. Overall, these regional dynamics reflect the increasing global focus on addressing the complexities of lupus and improving patient outcomes.
Market Drivers:
Rising Prevalence of Lupus and Autoimmune Diseases:
The increasing prevalence of lupus, particularly systemic lupus erythematosus (SLE), and other autoimmune diseases is a key driver of the lupus therapeutic market. For instance, According to the Centers for Disease Control and Prevention (CDC), approximately 200,000 to 300,000 individuals are affected by SLE in the United States alone, with most cases occurring in women of reproductive age. The Lupus Foundation of America reports that lupus disproportionately affects women, especially those of African, Hispanic, and Asian descent, who are two to three times more likely to develop the condition. As autoimmune diseases become more common globally, the demand for effective lupus treatments continues to grow.
Advancements in Biologic Therapies:
The development of biologic therapies has transformed the lupus treatment landscape, offering more targeted approaches to managing the disease. Biologics, such as Benlysta® (belimumab) by GlaxoSmithKline (GSK), have shown significant promise in reducing lupus flares and improving overall disease control. These treatments work by targeting specific components of the immune system, thereby minimizing inflammation and preventing tissue damage. Additionally, several pharmaceutical companies, including AstraZeneca and Roche, have launched clinical trials for new biologic agents designed to treat lupus, with some showing positive early-stage results. This trend highlights the ongoing commitment to developing more effective and personalized therapies for lupus patients.
Increased R&D Investments and Collaborations:
Pharmaceutical companies are heavily investing in research and development (R&D) to explore new therapeutic options for lupus. In recent years, the National Institutes of Health (NIH) has increased funding for lupus research, supporting studies aimed at understanding the disease's underlying mechanisms and identifying novel treatment targets. Collaboration between the private sector and research institutions also plays a vital role. For instance, Eli Lilly has partnered with various academic institutions to develop advanced therapies for lupus. Such collaborations not only accelerate the development of innovative treatments but also facilitate access to the latest scientific knowledge and resources.
Government Initiatives and Support for Patient Awareness:
Government initiatives focused on increasing awareness and improving the accessibility of lupus treatments are driving market growth. In the United States, programs like the Lupus Initiative by the Department of Health and Human Services (HHS) aim to educate both healthcare professionals and the public about lupus symptoms and management. Similarly, the European Medicines Agency (EMA) has expedited the approval process for orphan drugs, including those for lupus, which helps bring new therapies to market more quickly. Increased awareness efforts, coupled with patient advocacy group activities, encourage early diagnosis and treatment, thereby supporting the growth of the lupus therapeutic market.
Market Trends:
Growing Use of Combination Therapies:
The use of combination therapies is becoming increasingly popular in the lupus therapeutic market, as combining treatments can improve efficacy and provide better disease control. For example, studies have shown that a combination of hydroxychloroquine and corticosteroids can reduce lupus flare-ups more effectively than monotherapy. Pharmaceutical companies, including AstraZeneca, have been investigating the synergistic effects of combining their biologics with existing treatments to enhance therapeutic outcomes for lupus patients. This trend reflects a broader movement toward integrated treatment approaches, aiming to optimize patient care by addressing multiple aspects of the disease simultaneously.
Emphasis on Precision Medicine:
Precision medicine is gaining traction in the lupus therapeutic market, with efforts focused on developing treatments tailored to individual patient profiles. According to the National Institutes of Health (NIH), advancements in genomics and biomarker research are enabling a better understanding of lupus subtypes and their varying responses to treatment. For instance, GlaxoSmithKline (GSK) has been exploring the use of biomarkers to predict which patients will respond best to its lupus biologic, Benlysta®. This trend not only aligns with the broader healthcare shift towards personalized medicine but also offers hope for more targeted and effective therapies for lupus patients.
Rising Interest in Stem Cell Therapy:
Stem cell therapy is emerging as a promising treatment option for lupus, as research has shown that it has the potential to reset the immune system and reduce lupus symptoms. Clinical trials in the U.S. and Europe have demonstrated that mesenchymal stem cells (MSCs) can help decrease inflammation and improve overall immune function in lupus patients. For instance, Mesoblast Ltd has conducted studies suggesting that stem cell therapy could lead to prolonged remission in severe lupus cases. As interest grows, more companies are investing in clinical trials to explore stem cells as a viable alternative to traditional therapies, highlighting an innovative direction for lupus treatment.
Focus on Improving Quality of Life:
Alongside the development of medical treatments, there is a growing focus on enhancing the overall quality of life for lupus patients. Many healthcare providers now prioritize managing symptoms that affect daily functioning, such as fatigue, joint pain, and mental health issues. Organizations like the Lupus Foundation of America have emphasized holistic care, advocating for therapies that not only reduce disease activity but also address lifestyle factors and emotional well-being. As part of this trend, pharmaceutical companies are increasingly exploring drugs that mitigate specific symptoms to help patients maintain a more balanced, active life, reflecting a shift towards patient-centered care in the lupus therapeutic market.
Market Challenges Analysis:
High Cost of Advanced Therapeutics:
One of the primary challenges in the Lupus Therapeutic Market is the high cost associated with advanced biologics and other targeted therapies. Biologic treatments, such as Benlysta® by GlaxoSmithKline, are often more expensive than traditional medications, making them financially inaccessible for many patients. This is particularly burdensome in countries with limited healthcare reimbursement systems. In the United States, the Centers for Medicare and Medicaid Services (CMS) offers some assistance, but coverage remains inconsistent across regions and types of insurance plans, limiting patient access to innovative treatments.
Stringent Regulatory Approval Process:
The regulatory approval process for new lupus treatments is complex and time-consuming, posing a significant hurdle for pharmaceutical companies. Agencies like the U.S. Food and Drug Administration (FDA) and the European Medicines Agency (EMA) enforce rigorous clinical trial requirements to ensure the safety and efficacy of lupus therapies. These regulatory bodies often require extensive testing due to the immune-modulating nature of lupus drugs, which can delay approvals and increase development costs. For example, stem cell therapies face particularly high regulatory scrutiny, limiting the pace at which these promising treatments can reach the market. This regulatory burden not only extends the time to market but also elevates the financial risk for companies investing in lupus research.
Limited Awareness and Diagnosis Rates:
Despite increased public awareness efforts, many patients and healthcare providers are still unaware of lupus's early signs and symptoms, leading to delays in diagnosis and treatment. The World Health Organization (WHO) has noted that lupus can be challenging to diagnose due to its varied symptoms, which mimic those of other diseases. This lack of awareness and early diagnosis significantly hinders timely treatment, particularly in underserved regions with limited access to healthcare resources. Furthermore, the absence of a single, standardized diagnostic test adds to the challenge, contributing to underdiagnosis and delayed intervention.
Challenges in Managing Side Effects:
Treating lupus often involves immunosuppressive therapies that can lead to severe side effects, including increased infection risk, cardiovascular issues, and bone density loss. Managing these side effects is challenging for healthcare providers, as these complications can reduce patient adherence to prescribed treatments. The National Institutes of Health (NIH) emphasizes the need for therapies that minimize side effects to improve patient quality of life and compliance. Consequently, the balancing act between treatment efficacy and tolerability remains a central challenge in the lupus therapeutic market.
Market Segmentation Analysis:
By Type, the market is divided into biologics, corticosteroids, NSAIDs, antimalarials, and immunosuppressants. Biologics represent a significant portion of the market due to their targeted approach in modulating the immune system, reducing lupus flares, and improving patient outcomes. Biologics like Benlysta® are particularly prominent, as they offer advanced therapeutic options for patients with systemic lupus erythematosus. Immunosuppressants and corticosteroids also play a key role, especially for patients requiring comprehensive symptom management.
By Technology, the market is categorized into stem cell therapy, monoclonal antibodies, small molecules, and others. Monoclonal antibody technology, utilized in biologics, is a primary focus as it enables more specific targeting of disease pathways, which reduces the overall burden of lupus symptoms. Stem cell therapy, though still emerging, has shown promise in clinical trials, providing a potential alternative to traditional medications by offering long-term remission benefits.
By End User, the market is segmented into hospitals, specialty clinics, and home care settings. Hospitals constitute the largest end-user segment, as they offer advanced facilities for administering biologics and stem cell therapies that often require specialized care. Specialty clinics also hold a notable market share, given their role in providing targeted and long-term care for chronic lupus management. Meanwhile, home care settings are increasingly relevant, as patients look for convenient and accessible options to manage ongoing treatment needs, especially through orally administered immunosuppressants and other easily accessible therapies.
Segmentations:
By Disease Type:- Systemic Lupus Erythematosus (SLE)
- Cutaneous Lupus Erythematosus
- Drug-Induced Lupus Erythematosus
- Neonatal Lupus
- Non-Steroidal Anti-Inflammatory Drugs (NSAIDS)
- Biologics
- Antimalarial Drugs
- Corticosteroids
- Others
- Oral
- Subcutaneous
- Intravenous
- Others
- Hospital Pharmacies
- Medical Stores
- Others
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds a significant share of the Lupus Therapeutic Market, accounting for around 40% of the global market. The United States leads this region, driven by a high prevalence of lupus and robust healthcare infrastructure. The Centers for Disease Control and Prevention (CDC) reports that lupus is most common among women of childbearing age and affects approximately 200,000 to 300,000 Americans. The presence of major pharmaceutical companies, such as GlaxoSmithKline (GSK) and Eli Lilly, supports market growth through extensive R&D and the development of advanced biologics. Additionally, patient advocacy groups like the Lupus Foundation of America enhance awareness and facilitate clinical trials, further promoting market expansion.
Europe
Europe holds around 25% of the global lupus therapeutic market. The region is characterized by strong government support and advanced healthcare systems, particularly in Germany, the United Kingdom, and France. The European Medicines Agency (EMA) has implemented streamlined approval processes for orphan drugs, including lupus treatments, facilitating faster market entry. Additionally, the European Union funds research initiatives that support autoimmune disease treatment advancements, helping increase the availability of cutting-edge therapies. Key pharmaceutical markets in Europe emphasize the adoption of biologics and combination therapies to address diverse lupus symptoms, reflecting the region’s commitment to improving patient outcomes.
Asia-Pacific
The Asia-Pacific region is anticipated to experience the fastest growth, holding approximately 20% of the global market share. Countries like China, Japan, and India drive growth due to large population bases, rising healthcare expenditures, and improved healthcare access. Japan has a mature pharmaceutical market, with high awareness of lupus and access to advanced treatments, contributing significantly to regional growth. The region benefits from increasing investments by both local and international pharmaceutical companies, as well as government initiatives that prioritize treatment accessibility. As awareness of lupus expands and healthcare infrastructure strengthens, the demand for advanced therapies in Asia-Pacific is expected to surge.
Latin America
Latin America represents about 10% of the global lupus therapeutic market, with Brazil and Mexico as key contributors. The region has seen an increase in public awareness and access to healthcare services, which has boosted lupus diagnoses and treatment adoption. In Brazil, for instance, the government supports healthcare initiatives aimed at managing chronic diseases, including lupus. Collaboration with international organizations such as the World Health Organization (WHO) has also helped improve patient access to new therapies, though financial constraints and limited healthcare infrastructure remain challenges in parts of the region.
Middle East & Africa
The Middle East & Africa account for the remaining 5% of the global market. In this region, countries like South Africa and Saudi Arabia are gradually adopting advanced lupus treatments as part of their broader healthcare development strategies. Support from international health organizations and partnerships with pharmaceutical companies are facilitating access to diagnostic tools and therapies in these markets. However, the market faces challenges related to limited infrastructure, financial constraints, and low awareness levels in certain areas. Despite these hurdles, rising healthcare investments and increasing awareness are expected to drive steady growth in the Middle East & Africa over the coming years.
Key Player Analysis:
- GlaxoSmithKline (GSK)
- Eli Lilly and Company
- AstraZeneca
- Bristol-Myers Squibb
- Roche Holding AG
- Pfizer Inc.
- Sanofi S.A.
- Merck & Co., Inc.
- Biogen Inc.
- Johnson & Johnson
Competitive Analysis:
The Lupus Therapeutic Market is highly competitive, with key players such as GlaxoSmithKline (GSK), Eli Lilly, and AstraZeneca leading the way through substantial investments in research and development. These companies focus on biologics and other advanced therapeutics to address lupus's complex and multifaceted symptoms. Each major player strives to enhance its market position by expanding its product portfolio and engaging in clinical trials to validate new treatments. Collaborations and partnerships are also common, with companies like Roche and Sanofi joining forces with research institutions to accelerate drug development and leverage scientific advancements. Smaller biotech firms are entering the market as well, contributing innovative therapies and creating additional competition. Overall, the market's competitive landscape is characterized by a continuous drive for innovation and the quest to meet the growing demand for more effective and targeted lupus treatments.
Recent Developments:
- AstraZeneca received regulatory approval in the European Union for Saphnelo (anifrolumab) in 2022. This therapy, an add-on for adult patients with moderate to severe systemic lupus erythematosus (SLE), targets the type I interferon receptor, helping to reduce disease activity in patients who have not fully responded to standard treatments. The approval reflects AstraZeneca's commitment to expanding treatment options for lupus across different regions.
- In 2023, GlaxoSmithKline (GSK) expanded the reach of Benlysta (belimumab) to China, receiving approval from the National Medical Products Administration (NMPA) for its use in treating adult patients with active lupus nephritis, a severe form of lupus affecting the kidneys. This expansion aligns with GSK's focus on addressing lupus globally, especially in markets with high unmet medical needs.
- Eli Lilly has continued to invest in its lupus pipeline by advancing baricitinib, an oral JAK inhibitor, in late-stage trials. Baricitinib is designed to reduce inflammation in autoimmune diseases and has shown promising results in patients with systemic lupus erythematosus. This expansion of their pipeline underlines Lilly's commitment to providing new therapeutic options for autoimmune disorders.
- Roche is currently conducting Phase II trials for mosunetuzumab, a multispecific antibody targeting CD20, which has shown potential in treating patients with systemic lupus erythematosus. Roche's focus on multispecific antibodies reflects its strategy to develop innovative immunotherapies that offer more targeted treatment options for lupus patients, aiming to improve efficacy and safety profiles compared to conventional therapies.
Market Concentration & Characteristics:
The Lupus Therapeutic Market is moderately concentrated, with a few key players, including GlaxoSmithKline (GSK), AstraZeneca, Eli Lilly, and Roche, dominating due to their extensive research and development capabilities and established product portfolios. These companies hold significant market shares, supported by investments in innovative therapies like biologics and targeted treatments. The market is characterized by high entry barriers, given the substantial costs and stringent regulatory requirements associated with developing new lupus treatments. Despite this concentration, the competitive landscape is dynamic, with both major pharmaceutical firms and smaller biotech companies advancing their pipelines to capture growing demand. Furthermore, increasing collaborations between companies and research institutions are accelerating the development of more effective, patient-centric therapies. This focus on innovation, combined with regulatory support for orphan drugs, underscores the market's progression toward addressing the complex needs of lupus patients.
Report Coverage:
The research report offers an in-depth analysis based on Disease Type, Treatment Type, Route of Administration, and Distribution Channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The lupus therapeutic market will see increased development of biologics and monoclonal antibodies, which provide more targeted treatment options for lupus patients, reducing side effects and improving outcomes.
- Precision medicine will become more prominent, with therapies tailored to individual genetic profiles and disease subtypes.
- The market will benefit from rising government support and accelerated approval processes for orphan drugs, which will enable faster access to innovative treatments.
- Stem cell therapies and other regenerative medicine approaches will continue to gain traction as alternative options for severe cases of lupus.
- Combination therapies will expand as more research supports the efficacy of multi-drug regimens, enhancing patient outcomes and reducing the frequency of lupus flares.
- Increased patient advocacy and awareness campaigns will promote earlier diagnosis and treatment, driving demand for accessible lupus therapies.
- Emerging markets in Asia-Pacific and Latin America will contribute significantly to market growth, driven by improved healthcare infrastructure and rising lupus awareness.
- Digital health tools and AI-driven diagnostics will be increasingly integrated, enabling better disease tracking and personalized treatment adjustments for lupus patients.
- Collaboration between pharmaceutical companies and research institutions will accelerate innovation.
- The industry will prioritize improving patient quality of life, with a growing focus on managing symptoms like fatigue and joint pain.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Lupus Therapeutic Market?
What factors are driving the growth of the Lupus Therapeutic Market?
What are some challenges faced by the Lupus Therapeutic Market?
Who are the major players in the Lupus Therapeutic Market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Lupus Therapeutic Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Lupus Therapeutic Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 3,245 million → 2032: USD 6,418.56 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Lupus Therapeutic Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Lupus Therapeutic Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Lupus Therapeutic Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Lupus Therapeutic Market Drivers
- 3.3 Lupus Therapeutic Market Restraints & Challenges
- 3.4 Lupus Therapeutic Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Lupus Therapeutic Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Lupus Therapeutic Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Lupus Therapeutic category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Lupus Therapeutic Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Lupus Therapeutic Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Lupus Therapeutic market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Lupus Therapeutic Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Lupus Therapeutic Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Lupus Therapeutic Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Lupus Therapeutic (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Lupus Therapeutic Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Lupus Therapeutic Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Lupus Therapeutic Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Lupus Therapeutic Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Lupus Therapeutic Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Lupus Therapeutic Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Lupus Therapeutic Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Lupus Therapeutic Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Lupus Therapeutic Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
