
Fiber-stage value shifts toward India and nonwoven grades
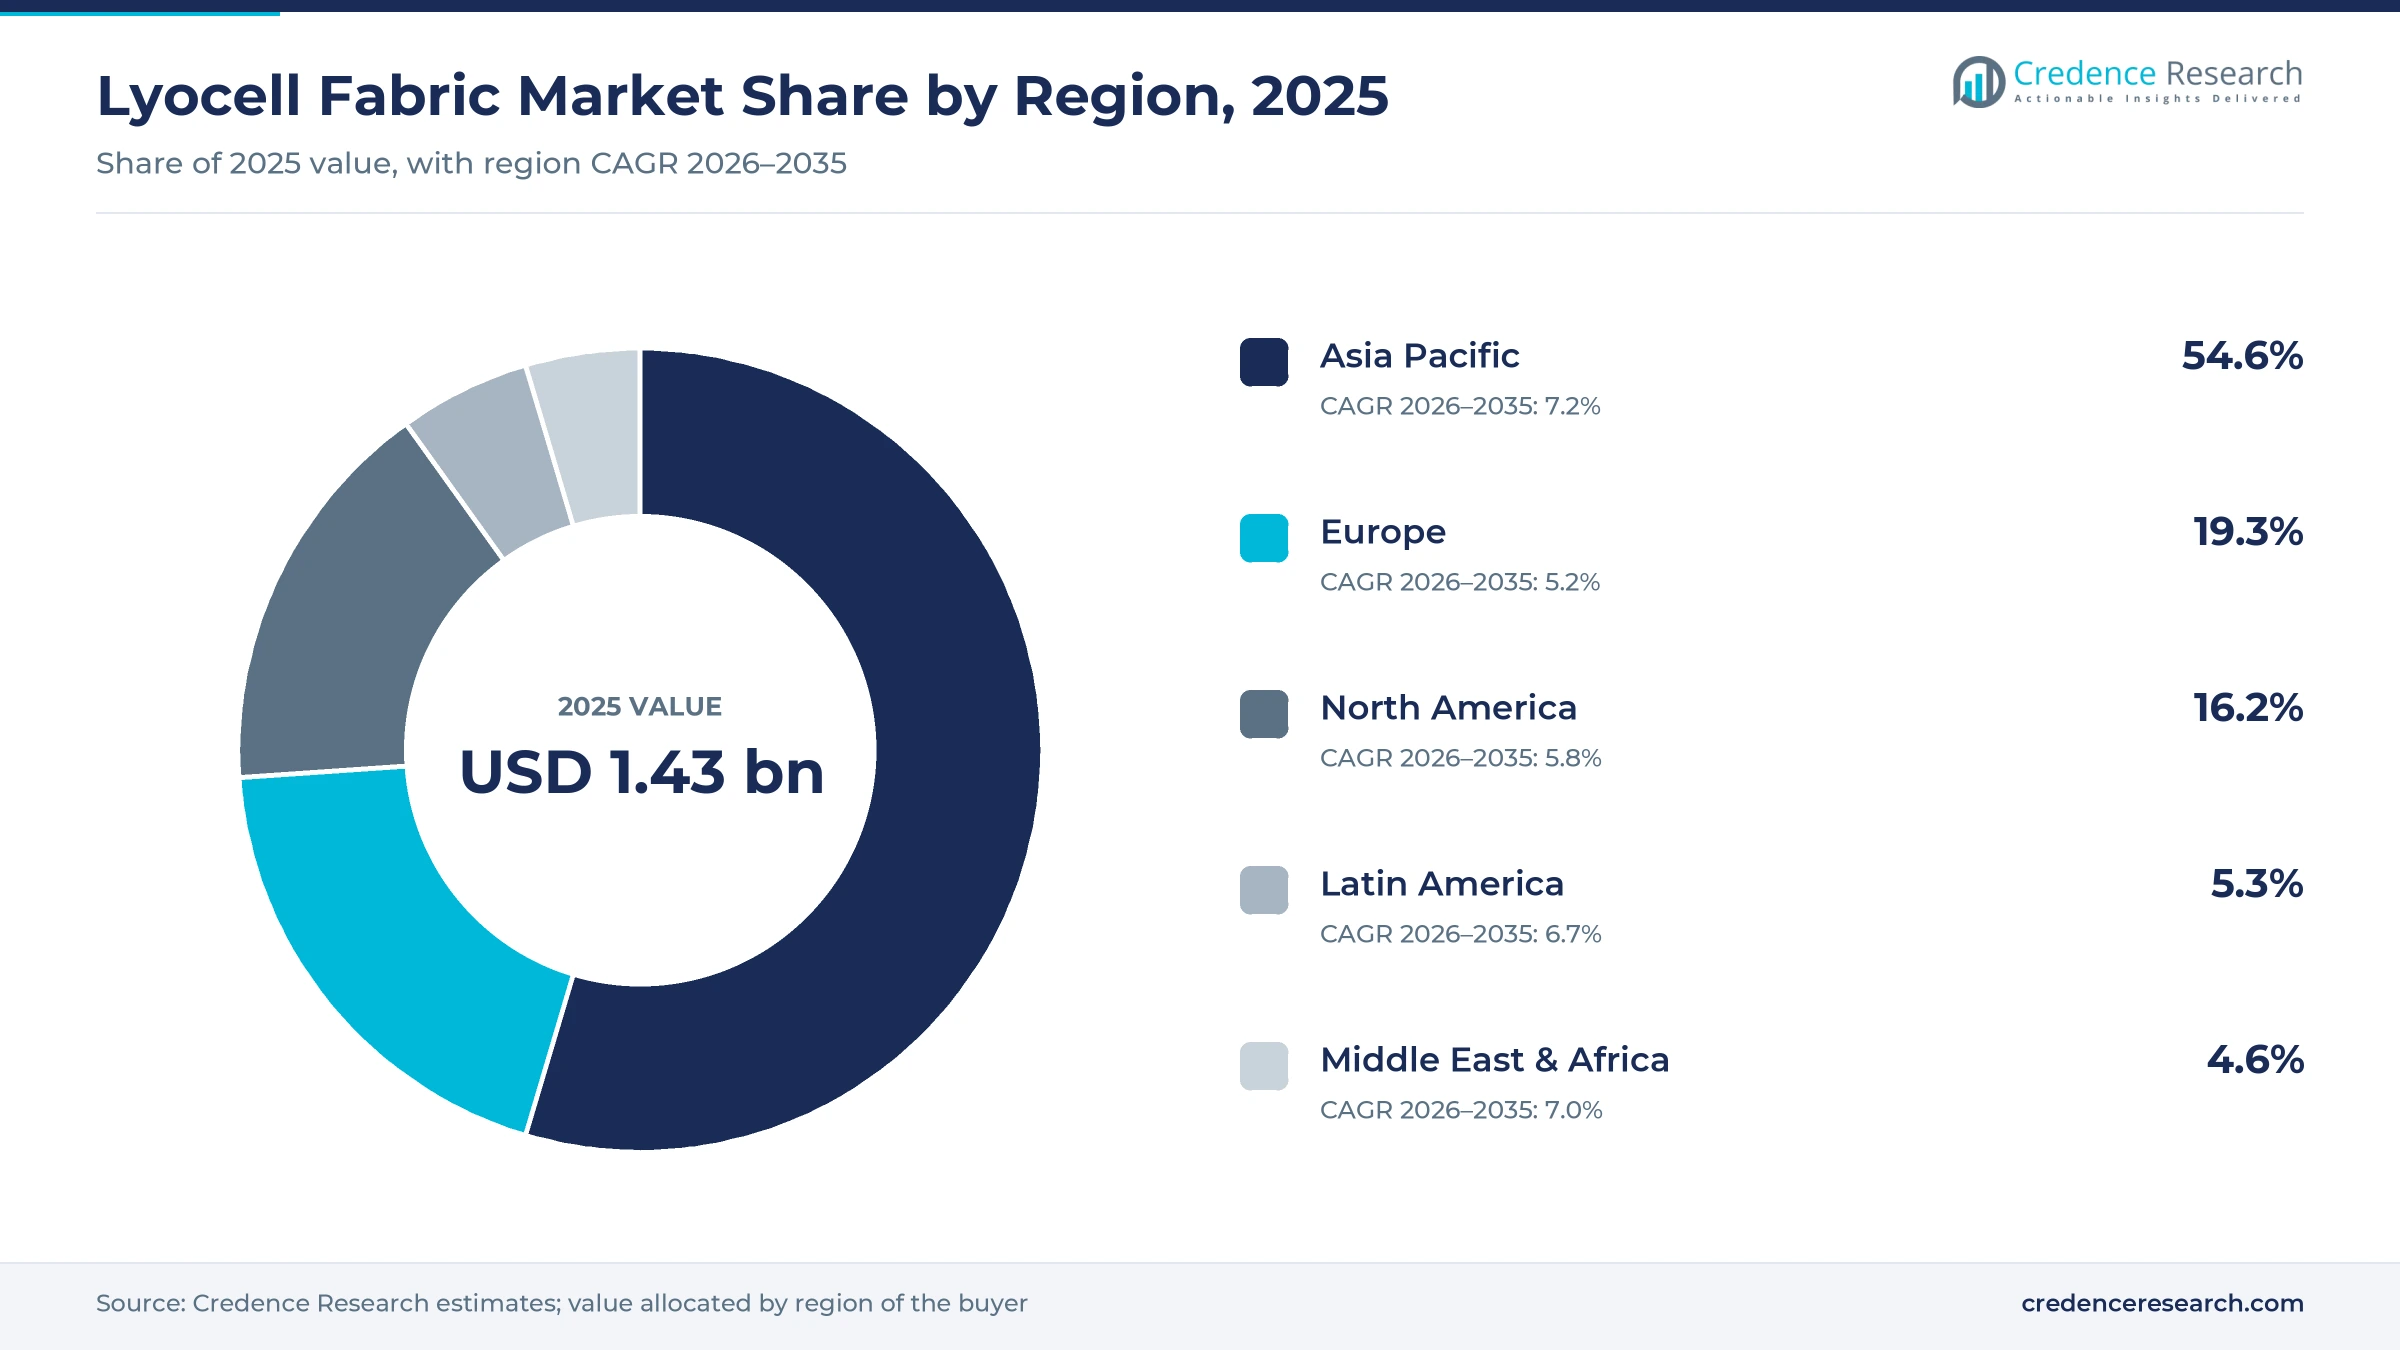
The global lyocell fabric market was valued at USD 1.43 billion in 2025 and is projected to increase from USD 1.53 billion in 2026 to USD 2.72 billion by 2035, registering a CAGR of 6.60% during 2026–2035. Apparel mills buy most of the fiber for denim, shirting, knitwear and cotton blends, while wipes converters, bedding makers and medical nonwoven producers form the next demand pools. Asia Pacific held the largest regional share, 54.6% in 2025, because spinning, weaving and knitting capacity in China, India, Bangladesh and Pakistan converts most of the world's lyocell. Asia Pacific is also the fastest-growing region at 7.2% a year, as Indian and Chinese producers add local lines close to those mills. The most important commercial change is the shift of the leading Western producer from commodity textile fiber toward nonwoven grades, with two European plant closures announced in 2026. Low Chinese selling prices are the main restraint, because they cap the premium that branded fiber can earn.
Where does lyocell value sit between the pulp mill and the garment?
The estimate counts lyocell staple fiber, short-cut fiber and filament yarn sold into woven, knitted and nonwoven fabric production, valued at the producer selling price. The fabric-type split allocates that fiber value by the woven, knitted or nonwoven cloth it is sold into. Valuing the material at the fiber stage avoids counting the same metric ton again when it is spun, woven, dyed and sewn into garments or bedding. Branded grades sell under producer trademarks with certification and traceability services, while unbranded Chinese fiber sells mainly on price to spinners.
Finished garments, the cotton or viscose content of blended cloth and the dissolving pulp that producers buy are excluded. The value chain runs from wood pulp through solvent spinning to spinners, weavers, knitters and nonwoven roll-goods makers. Margins are highest where a producer controls pulp, owns a recognized fiber brand and can supply special cuts for denim or wipes.

Lyocell Fabric Market Insights
- The market rises from USD 1.43 billion in 2025 to USD 2.72 billion by 2035, a 6.60% CAGR, as Indian capacity and nonwoven grades add volume while Chinese pricing limits value gains.
- Asia Pacific held 54.6% of 2025 value, because the mills that spin, weave and knit lyocell for denim, shirting and jersey are concentrated in China, India, Bangladesh and Pakistan.
- Apparel took 52.0% of 2025 value, as denim warp yarns, shirting and knit jersey absorb most of the staple fiber shipped by the large producers.
- Lenzing announced on July 27, 2026, that it will end fiber production at Heiligenkreuz by December 2026 and at Grimsby by the end of 2027.
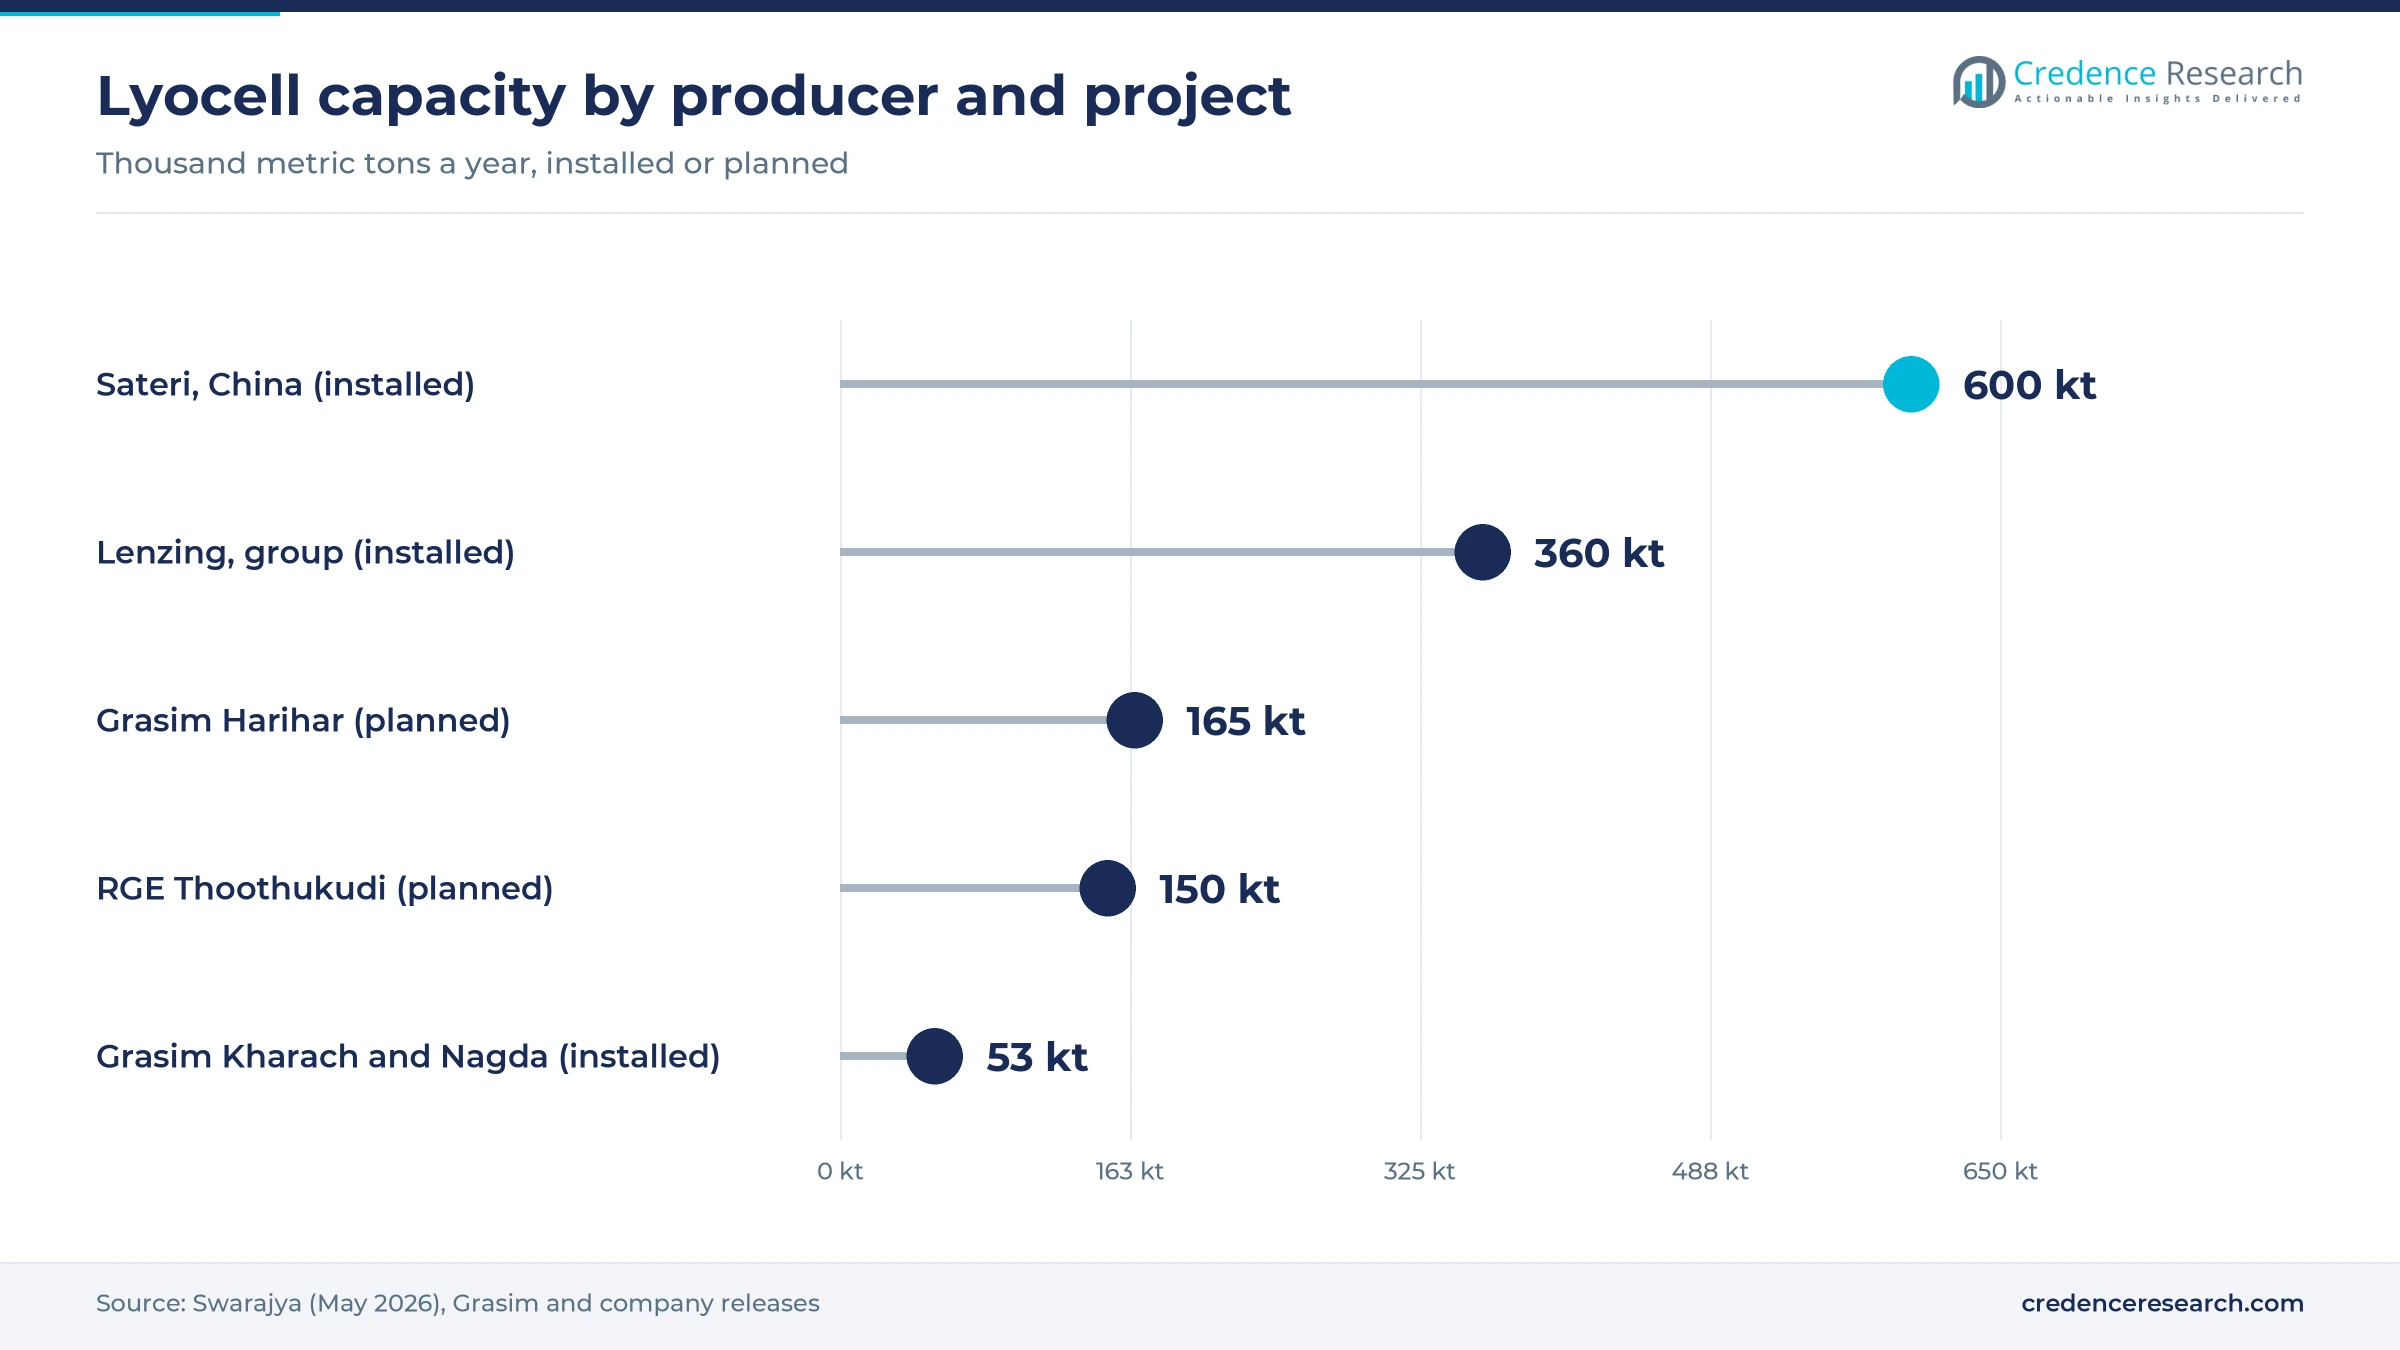
- Grasim expects its lyocell capacity to reach about 210,000 metric tons a year once the Harihar phases are complete, making India a second production base beside China.
Staple and apparel lead as hygiene grows fastest
Staple fiber dominates as filament scales slowly
Based on product type, the market is categorized into staple and filament. Staple led with 88.0% of 2025 value because cut fiber runs on the ring, open-end and airlaid lines that dominate denim, jersey and wipes production. Sateri alone reported about 600,000 metric tons of installed lyocell capacity across four Chinese sites, almost all of it staple, according to Swarajya in May 2026. Filament grows fastest at 7.5% a year, as Lenzing reported in March 2026 that it is scaling lyocell filament in the EU-funded CELLFIL project as an alternative to synthetic filament. Filament volumes remain small because spinning continuous yarn costs far more per kilogram.
Woven cloth leads while knitted jersey grows fastest
Based on fabric type, the market is categorized into woven, knitted and nonwoven fabrics. Woven fabrics led with 42.0% of 2025 value because denim, shirting and bottom-weight cloth take large volumes of staple in warp and weft yarns. Turkish denim maker ORTA said in October 2025 that lyocell warp fabric reacts to indigo dyeing and washing much like cotton, which lets mills swap fiber without new finishing routes. Knitted fabrics grow fastest at 7.3% a year, as wider use of circular knitting machines has significantly raised lyocell consumption in China, according to Chen Zongli, chairman of Nantong yarn maker Xinhuayuan, in April 2026.
Apparel leads as hygiene wipes grow fastest
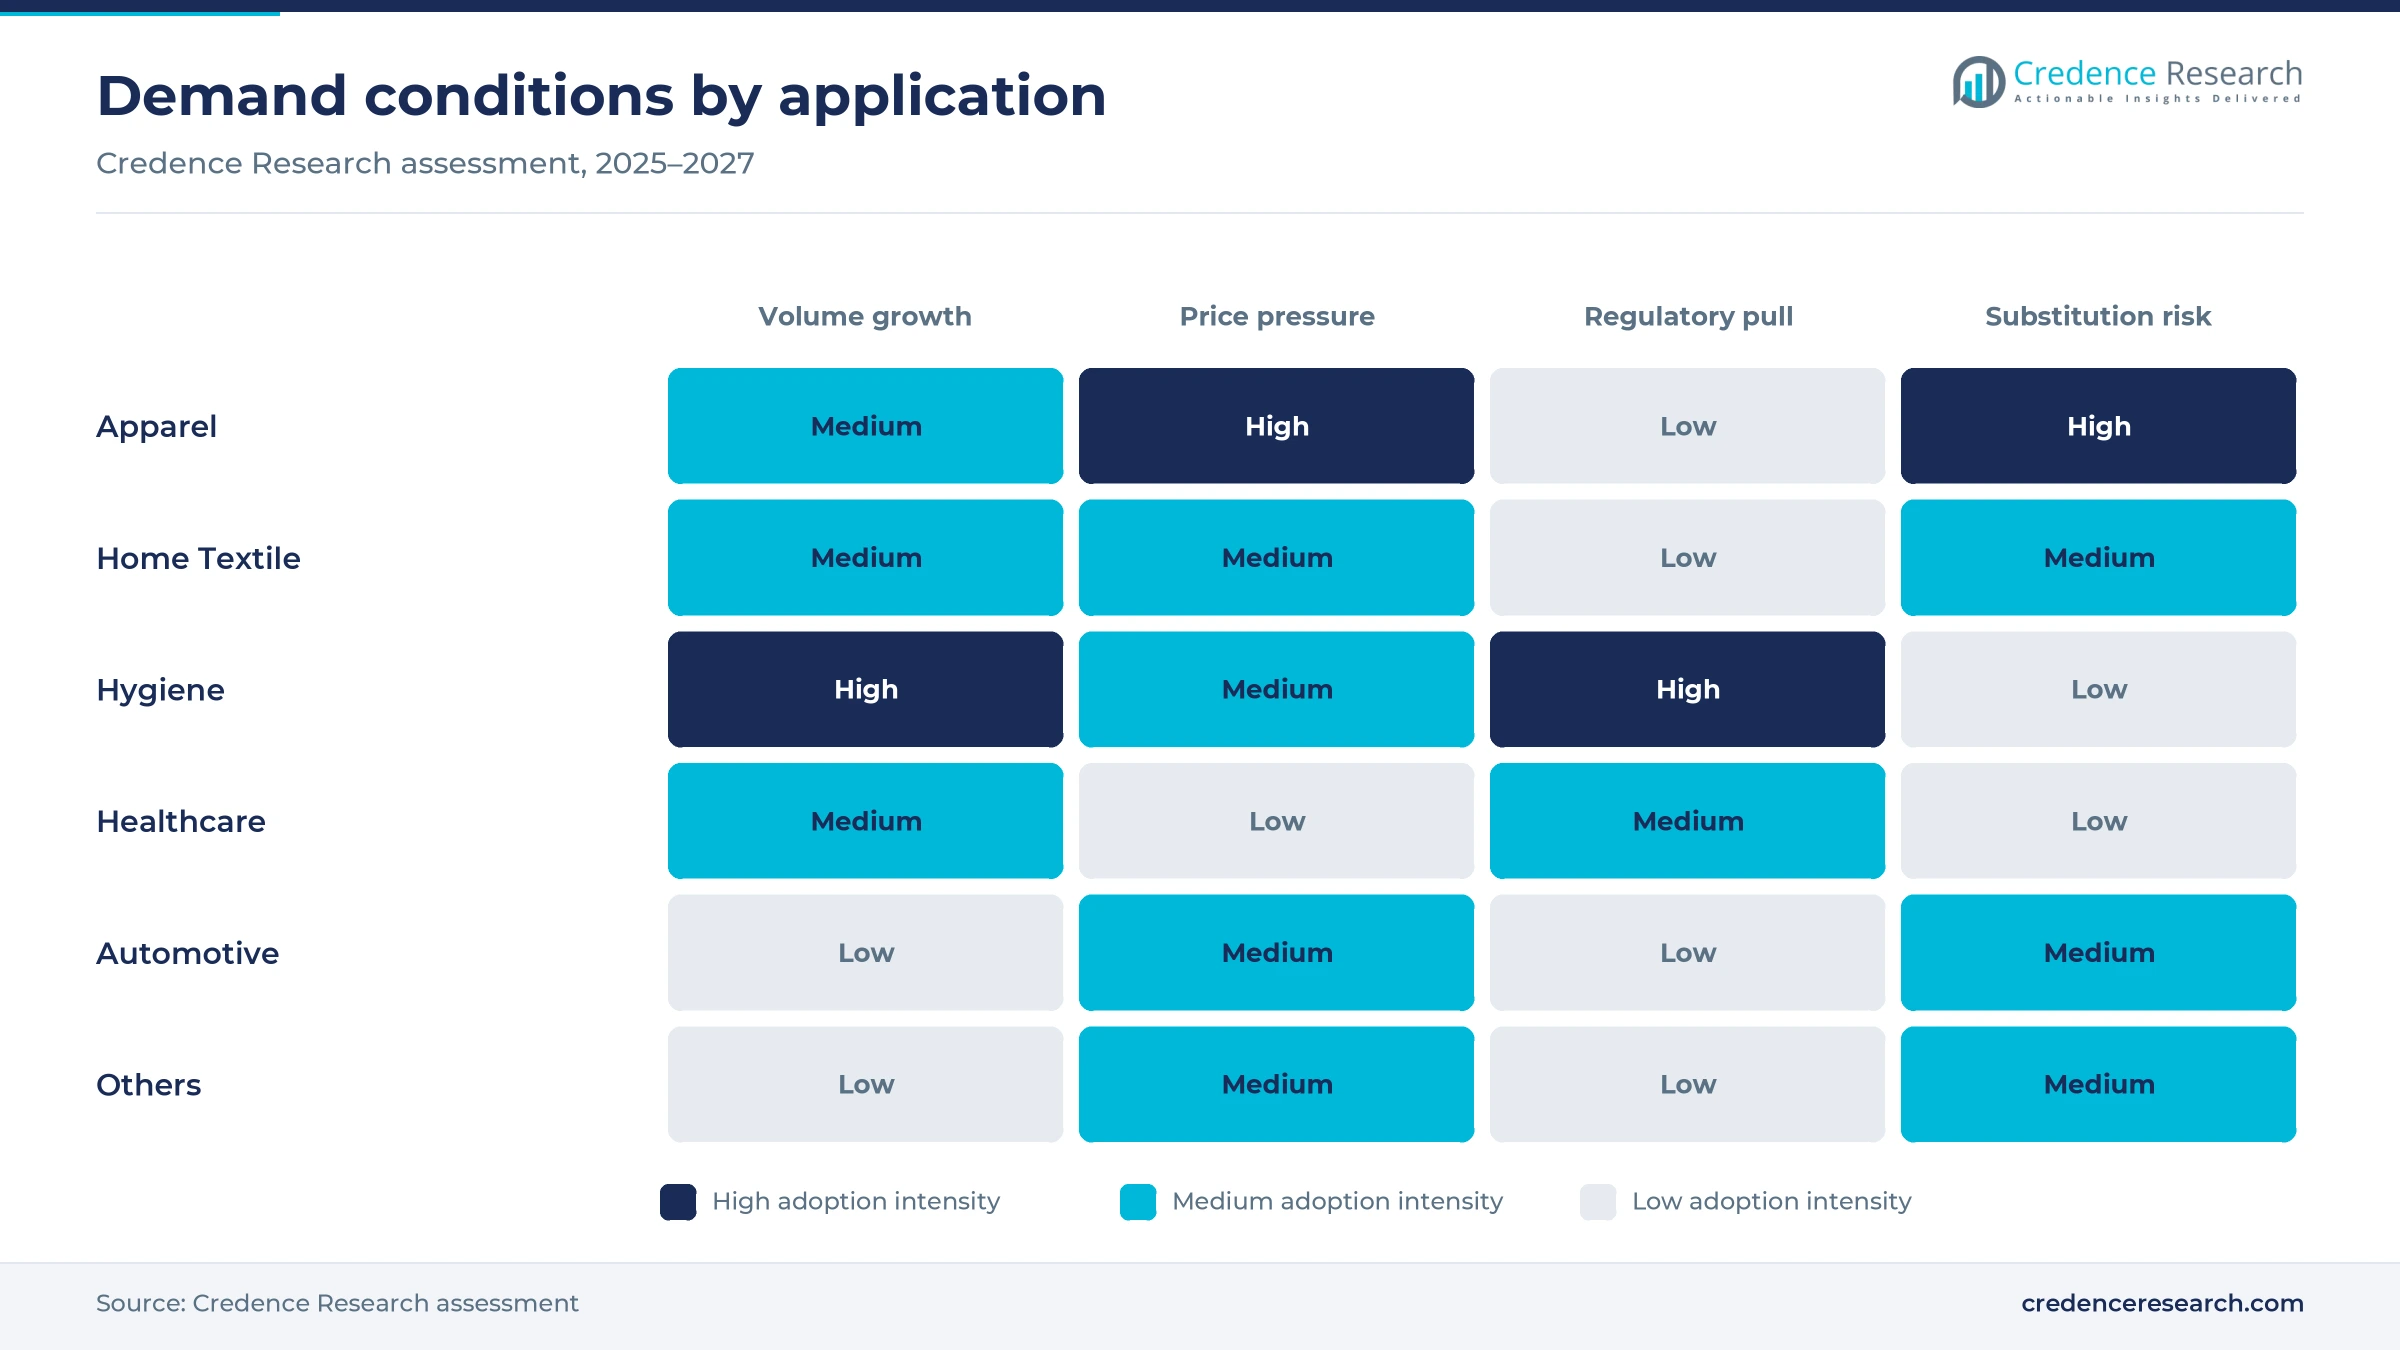
Based on application, the market is categorized into healthcare, hygiene, apparel, home textile, automotive and others such as filter tow. Apparel led with 52.0% of 2025 value because lyocell blends with cotton in denim, shirting and knitwear, and a Grasim executive told Textile Excellence that lyocell's share of the man-made cellulosic fiber basket should rise from about 10% in 2022 to nearly 20% by 2027. Hygiene grows fastest at 7.8% a year as wipes makers replace plastic fibers. Lenzing began producing nonwoven-grade lyocell in Asia for the first time on March 18, 2026, at its 100,000-metric-ton Prachinburi plant in Thailand, aiming at baby wipes and facial sheet masks.
| Segment Group | Leading Sub-segment | Share, 2025 | Fastest-growing Sub-segment | CAGR, 2026–2035 |
|---|---|---|---|---|
| By Product Type | Staple | 88.0% | Filament | 7.5% |
| By Fabric Type | Woven | 42.0% | Knitted | 7.3% |
| By Application | Apparel | 52.0% | Hygiene | 7.8% |
Commodity staple now trades close to viscose
Lyocell staple sells per metric ton under quarterly or annual contracts with spinners and nonwoven roll-goods makers, while branded grades add license, certification and traceability services on top. The price floor is set by Chinese commodity staple, which now trades near viscose levels. Grasim's results show the global average cellulosic staple price at USD 1.81 per kilogram in the April to June 2026 quarter, up 19% from a year earlier. Pulp, energy and solvent recovery move the cost side, while new Chinese lines move the selling side. Branded producers keep a clear premium only for special cuts, certified wood and nonwoven grades, so standard apparel fiber earns thin margins.
| Product or indicator | Typical price or fee | Basis |
|---|---|---|
| Chinese commodity lyocell staple, mid-2024 | About CNY 13,000 per metric ton (about USD 1.80/kg) | Swarajya, May 2026 |
| Branded lyocell staple for apparel | USD 2.6–3.6/kg | Credence Research estimate, 2025 |
| Nonwoven-grade and short-cut lyocell | USD 2.4–3.2/kg | Credence Research estimate, 2025 |
| Lyocell filament yarn | USD 8–14/kg | Credence Research estimate, 2025 |
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Wipes rules, Indian plants and cotton costs lift demand
Plastic-free wipes rules move converters to lyocell
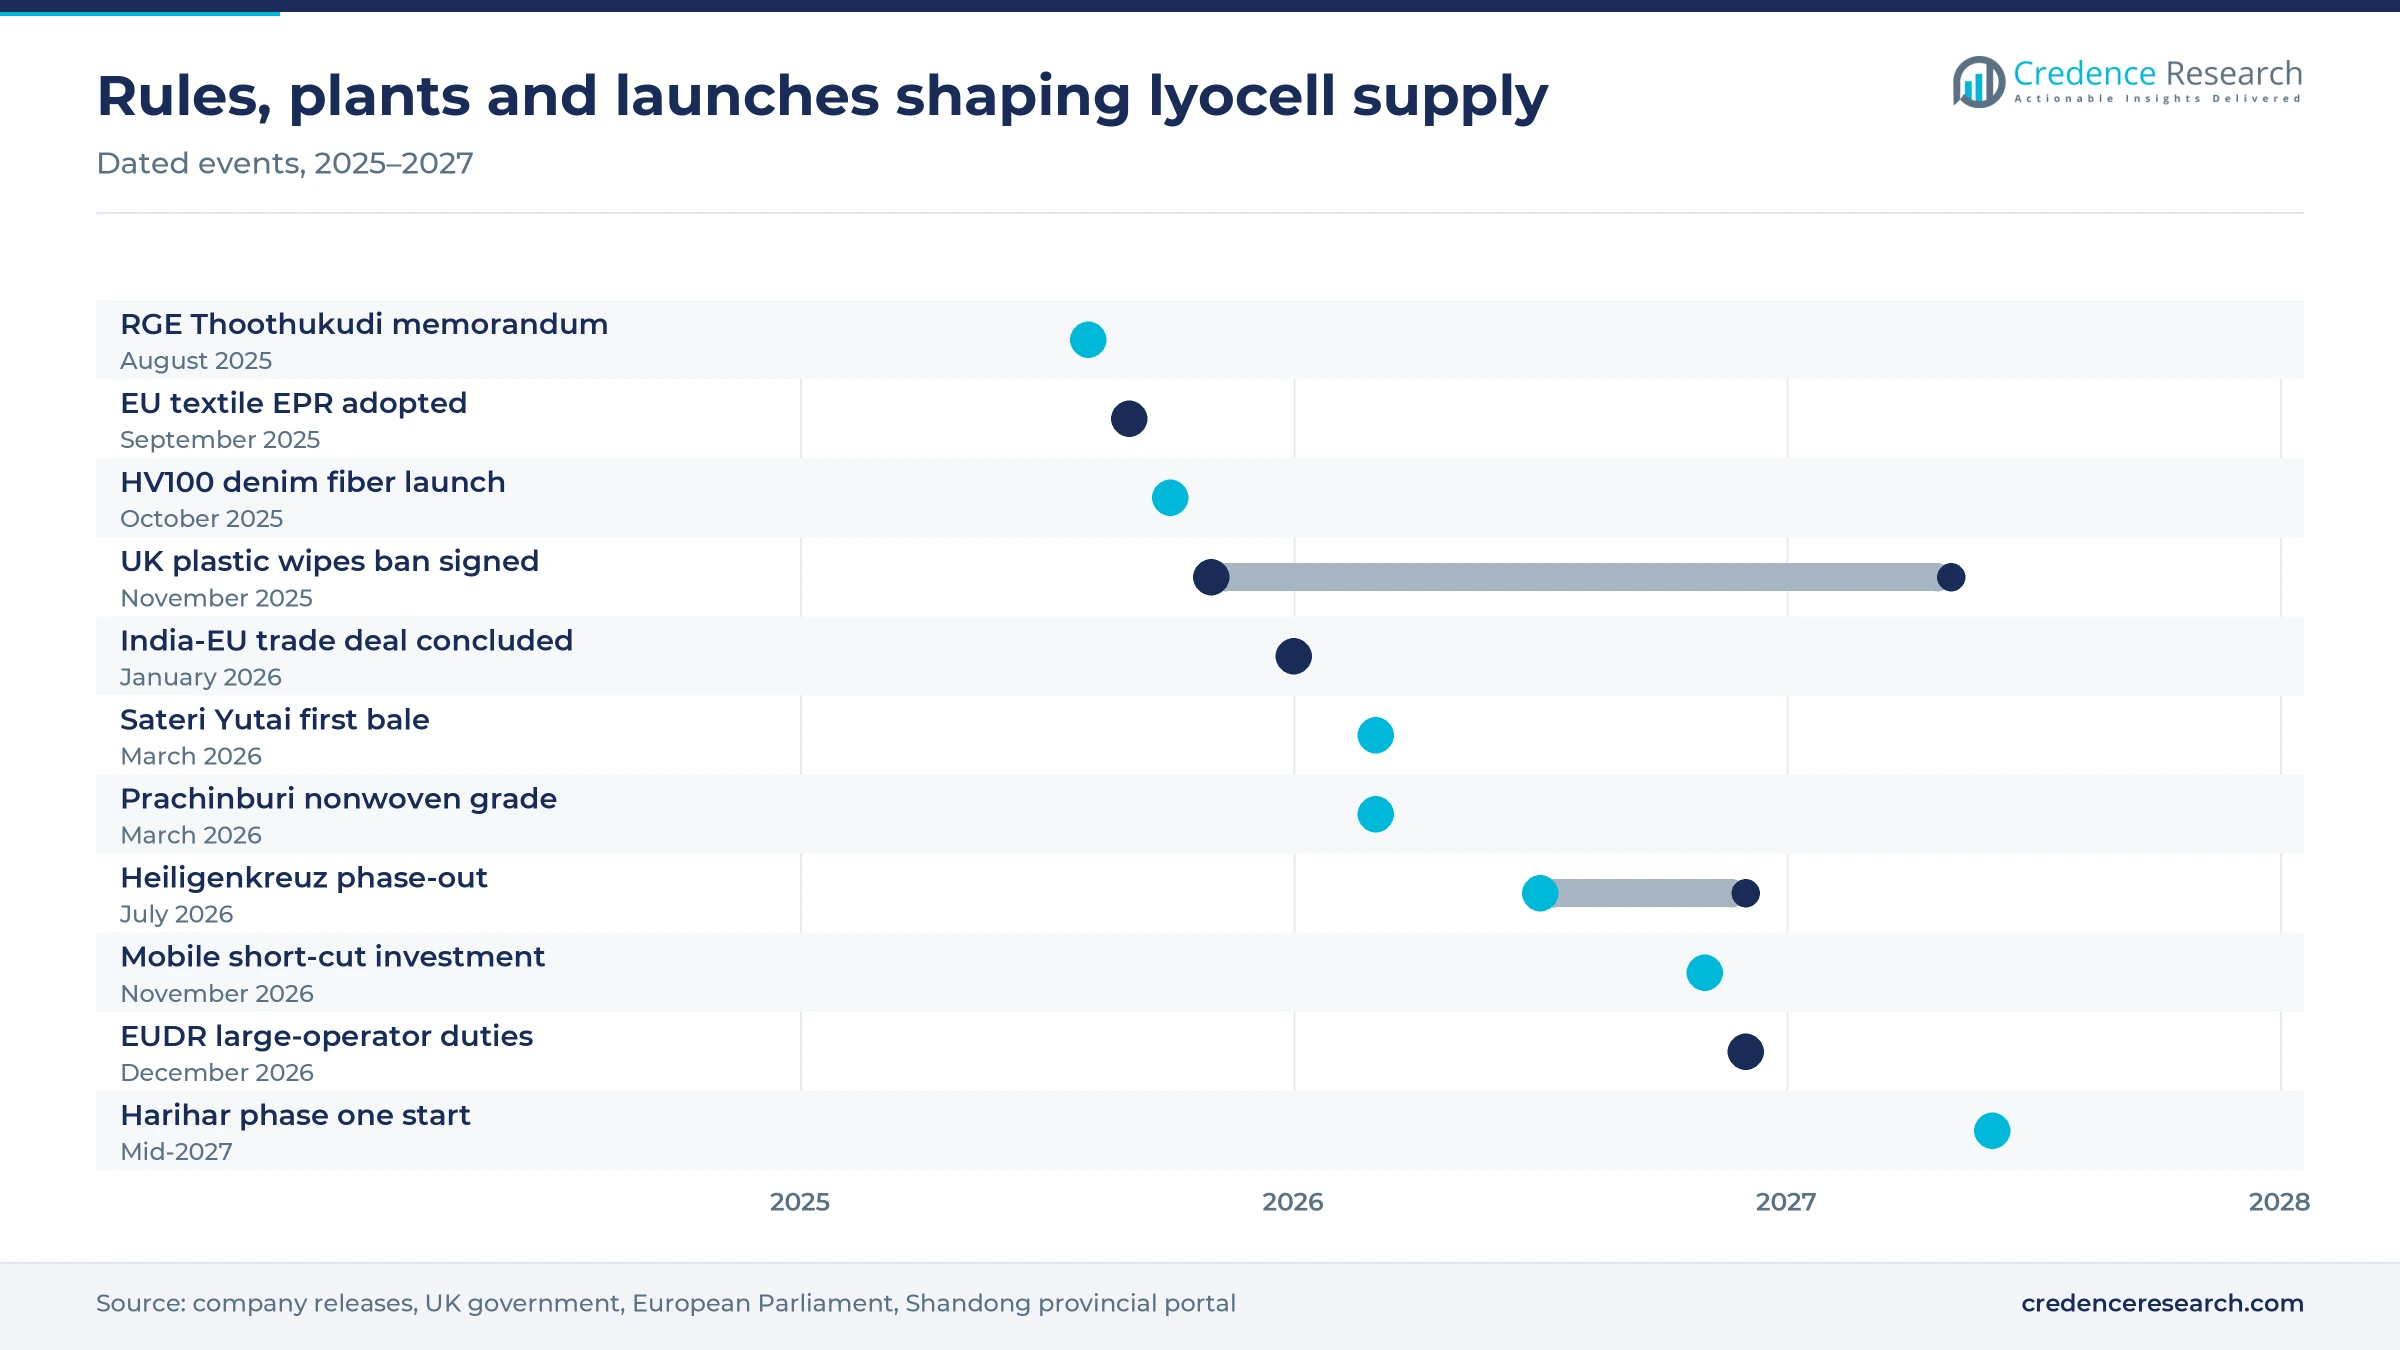
Rules against plastic in wipes push converters toward cellulosic fibers that break down after disposal, and lyocell offers the wet strength that cheaper viscose lacks. The U.K. government signed a ban into law on Nov. 18, 2025, on wet wipes containing plastic, effective in spring 2027, after U.K. Water Industry Research found that wipes contribute to 94% of sewer blockages. The European Commission lists wet wipes and sanitary items among the products targeted by its Single-Use Plastics Directive, and the nonwovens association EDANA says wet wipes must carry marking on plastic content and disposal. Lenzing announced a EUR 27 million investment in short-cut lyocell fiber for nonwovens at Mobile, Alabama, on Nov. 12, 2026. Producers with nonwoven grades gain a regulated demand pool that commodity textile fiber cannot serve.
Indian mills want domestic supply instead of imports
India is becoming a second demand center, because its spinners, weavers and knitters want domestic lyocell rather than imported Chinese fiber with long lead times. Industry projections cited by Asia Pacific Rayon put Indian lyocell demand growth above 15% a year over the next five years. Grasim approved an INR 3,094 crore second phase at Harihar, Karnataka, with two 55,000-metric-ton lines due in 2028 and 2030, after a first 55,000-metric-ton phase due by mid-2027. Royal Golden Eagle signed a memorandum on Aug. 4, 2025, for an INR 4,953 crore plant at Thoothukudi with 150,000 metric tons a year of lyocell, according to Swarajya. Local supply should shorten lead times and cut import dependence for Indian garment exporters.
Cotton shortages make cellulosic blends cheaper to justify
Cotton supply swings make lyocell blends easier to justify, because spinners can replace part of the cotton in a yarn without changing the hand of the finished cloth. India became a net cotton importer in 2025, and a deficit of 1,500 to 1,600 metric tons a day is projected by 2030, a Grasim executive told Textile Excellence. World cotton output slipped to about 24.5 million metric tons in 2024, or 19% of all fiber, according to Textile Exchange. Lenzing designed its HV100 fiber in 2025 for denim warp yarns that mimic cotton's irregular look. Spinners that qualify lyocell-cotton blends can therefore hedge cotton costs while keeping a natural appearance that polyester blends cannot match.
Traceability and EPR rules reward certified wood fiber
Brand sourcing rules reward fibers with traceable wood and closed-loop processing, and lyocell meets both tests better than most alternatives. The European Parliament adopted textile extended producer responsibility on Sept. 5, 2025, which makes producers pay for collection, sorting and recycling within 30 months, according to ERP. About 65% to 70% of man-made cellulosic feedstock is already FSC- or PEFC-certified, according to Textile Exchange data summarized on the EU Textiles Ecosystem Platform. Grasim says its closed-loop lyocell process recovers 99.7% of solvents and process gases. Large operators must also meet EU Deforestation Regulation due diligence from Dec. 30, 2026, which favors producers that already hold certified pulp chains.
Nonwoven pivots, recycled pulp and denim openings
Western producers are shifting from apparel to nonwovens
Lenzing is shifting toward nonwoven fibers to address low margins in commodity textile fiber, creating openings for Chinese and Indian producers in standard apparel grades. The company said on July 27, 2026, that fiber production at Heiligenkreuz will end by the close of 2026 and at Grimsby by the close of 2027, while it evaluates a sale or other options for both sites. Its fiber sales fell to about 904,000 metric tons in 2025 from 960,000 metric tons in 2024, according to its March 2026 results. It has also committed EUR 50 million to nonwoven capacity in Austria and the United States under its Grow Nonwovens, Reset Textiles strategy. European apparel mills that relied on nearby branded supply now face longer lead times or Asian substitutes.
Recycled pulp is entering lyocell staple supply
Producers are shifting toward recycled textile pulp in lyocell to meet brand targets for textile-to-textile content. Tangshan Sanyou signed a five-year agreement with U.S.-based Circ in July 2025 to make lyocell staple with 30% recycled content, using pulp from a Circ plant slated to operate by 2028. Recycled feedstock made up only about 1.1% of man-made cellulosic fiber in 2024, up from 0.7% in 2023, according to Textile Exchange's 2025 report. Adidas, Lenzing and Niederrhein University of Applied Sciences produced a sweater from recycled lyocell in a closed loop, a project Lenzing reported in March 2026. Recycled grades should command premiums once volume exists, although supply before 2028 stays small.
Denim mills offer a premium opening for staple suppliers
Denim mills offer a measurable opening for staple suppliers that can match cotton's appearance in warp yarns, which form the face of the cloth. Lenzing launched HV100 with 17 mill partners in five countries at Kingpins Amsterdam in October 2025, and the second release in April 2026 added 20 mills, according to Textile Excellence. The network spans nine countries, including Bangladesh, Cambodia, Mexico, Pakistan, Türkiye and Vietnam, and finished products reached retail in March 2026. Brands that sell denim jeans can cut cotton share without changing wash-down behavior, which gives mills a premium line in seasons when cotton prices swing. A third release with 10 more mills is lined up for later in 2026, which shows that bulk orders are spreading beyond the launch partners.
Indian exporters can use local fiber under the EU trade deal
Indian garment exporters gain an opening for lyocell blends once the India-EU free trade agreement concluded on Jan. 27, 2026, enters into force. Swarajya reports that the deal removes 8% to 12% duties on Indian textiles, although rules of origin require substantial transformation in India. Most of Grasim's existing 53,000 metric tons of lyocell capacity at Kharach and Nagda goes to nonwovens such as wipes, according to the same report, which leaves apparel exporters reliant on imported fiber today. New Harihar and Thoothukudi lines would let knitters and weavers meet origin rules with domestic fiber and sell traceable blends to European brands.
Chinese pricing and cost swings squeeze producers
Chinese capacity has pushed staple prices down
Chinese capacity growth has cut the price of standard staple. Chinese lyocell sold above CNY 20,000 per metric ton when international producers dominated but fell to about CNY 13,000 by mid-2024, according to Swarajya. Branded producers with European cost bases are most exposed, since their energy and labor costs do not fall with prices. Lenzing expects generic fiber prices to stay under pressure from further capacity additions, according to its March 2026 results. Prices have since firmed, as Grasim reported in August 2026 that global cellulosic staple prices rose for a third straight quarter while Chinese operating rates reached 93%.
Idle lines raise fixed costs for late entrants
Rapid Chinese additions created long periods of idle capacity, which raises fixed costs per metric ton for producers that entered late. Chinese lyocell operating rates were only 44% in 2022 before recovering to 85% in 2024, according to industry data cited by Swarajya. Sateri's Yutai site then produced its first commercial bale on March 13, 2026, adding a further large block of supply. Smaller producers without pulp integration or a brand are most exposed when new lines start faster than mill demand grows.
Energy and raw material costs remain volatile
Solvent spinning is energy-intensive, so fuel and pulp price swings feed straight into producer margins. Lenzing said in May 2026 that it expected the Middle East conflict to push energy and raw material prices up from the second quarter, and that a reliable forecast for 2026 was not possible. European plants with high gas costs are most exposed under these conditions. Producers in Asia with captive pulp and cheaper power absorb these swings better and can undercut contract prices.
Polyester still sets the cost benchmark for mass apparel
Polyester remains the default fiber for price-led apparel, which limits how far lyocell can spread beyond premium lines. Polyester accounted for about 78 million metric tons, or 59% of 2024 fiber output, while lyocell was about 0.4 million metric tons, according to Textile Exchange. Lyocell sellers that target fast-fashion buyers pricing per garment are most exposed. Gains in that segment depend on blends where lyocell adds comfort at a small cost per garment.
Asia Pacific leads on mills as Europe loses capacity
| Region | Value, 2025 (USD billion) | Share, 2025 | CAGR, 2026–2035 |
|---|---|---|---|
| Asia Pacific | 0.78 | 54.6% | 7.2% |
| Europe | 0.28 | 19.3% | 5.2% |
| North America | 0.23 | 16.2% | 5.8% |
| Latin America | 0.08 | 5.3% | 6.7% |
| Middle East & Africa | 0.07 | 4.6% | 7.0% |
Asia Pacific leads on mills and new fiber lines
Asia Pacific held 54.6% of 2025 value and grows fastest at 7.2% a year, because China hosts most production and the region's spinners convert most of the fiber. Yutai County in Shandong launched the first line of a new lyocell project on March 17, 2026, aimed at high-end apparel and home textiles, according to the Shandong provincial investment portal. India adds the Harihar and Thoothukudi capacity described in the drivers, and Lenzing's Thai plant now supplies both textile and nonwoven grades. Local integration lowers delivered cost but also intensifies price competition.
Europe grows slowest as local lyocell lines close
Europe held 19.3% of 2025 value and grows at 5.2% a year, the slowest rate, because local production is shrinking while brand demand stays. The Heiligenkreuz and Grimsby closures noted above remove two of the oldest lyocell lines in the world. Lenzing has instead invested EUR 23 million since November 2025 to expand nonwoven fiber output at its main Austrian site, mainly for hygiene uses. European weavers and knitters will import more fiber and yarn from Asia, while EPR fees keep buyers focused on certified grades.
North America shifts toward wipes and hygiene grades
North America held 16.2% of 2025 value and grows at 5.8% a year, with the United States accounting for most of it. The Mobile investment noted above turns Lenzing's Alabama site toward short-cut fiber for wet wipes and hygiene products. A 2018 plan to expand the same site with a USD 293 million investment was mothballed, according to Swarajya, so apparel mills in the region rely largely on imported fiber and fabric. Nonwoven converters are therefore the most dependable regional buyers of the fiber.
Latin America grows on denim and knit mills
Latin America held 5.3% of 2025 value and grows at 6.7% a year, with demand concentrated in Mexican and Brazilian denim and knit mills that supply North American brands. Mexico joined the HV100 denim network in April 2026, which ties part of regional demand to premium jeans programs. Evidence on regional lyocell volumes is thin, so this estimate rests mainly on denim capacity and import patterns rather than on published consumption figures.
Middle East & Africa gains from Turkish and Egyptian mills
Middle East & Africa held 4.6% of 2025 value and grows at 7.0% a year. Türkiye, which the Credence Research regional model groups with the Middle East, hosts denim mills such as ORTA, a launch partner for HV100 in October 2025. Egypt is among the overseas markets where demand for lyocell fiber and yarn is growing, the Xinhuayuan chairman said in April 2026. Published volume data for the region are scarce, so this estimate carries wider uncertainty than the others.
Plant closures, new lines and launches reset supply
| Development | Status and market relevance |
|---|---|
| In October 2025, Lenzing launched TENCEL Lyocell HV100 at Kingpins Amsterdam, a denim fiber with variable cut lengths developed with mill partners in five countries. | Commercial launch; bulk orders were secured and products reached retail in March 2026. |
| In March 2026, Sateri produced the first commercial bale at its Yutai site in Shandong, part of a planned four-line, 600,000-metric-ton lyocell complex. | Production start; it adds large staple volume to an already well-supplied Chinese market. |
| In March 2026, Lenzing started nonwoven-grade VEOCEL lyocell production at its 100,000-metric-ton Prachinburi plant in Thailand, the first such output in Asia. | Operational launch; it brings wipes-grade fiber closer to Asian converters. |
| In July 2026, Lenzing announced that fiber production will end at Heiligenkreuz, Austria, by December 2026 and at Grimsby, U.K., by the end of 2027, while it evaluates a sale of both sites. | Announced plan; it reduces European lyocell output and shifts volume to core sites. |
| In November 2026, Lenzing announced a EUR 27 million investment in short-cut lyocell fiber for nonwovens at Mobile, Alabama, part of a EUR 50 million nonwovens program. | Investment announcement; no start-up date was given. |
Solvent spinning and cut control shape fiber value
- Closed-loop solvent spinning dissolves wood pulp directly without a chemical derivative step and recovers almost all of the solvent, which keeps emissions and chemical cost per kilogram low.
- Variable cut technology varies staple length so lyocell yarn mimics the slub and matte look of cotton in denim warps while keeping clean indigo wash-downs.
- Short-cut fiber gives wipes and airlaid producers fiber lengths suited to wet-laid and hydroentangled nonwovens that must disperse after disposal.
- Continuous filament spinning produces smooth lyocell yarn for linings, scarves and fine wovens that compete directly with polyester and nylon filament.
- Recycled pulp feedstock blends dissolving pulp made from discarded cotton textiles into the spinning dope, raising recycled content on existing lines.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Three producers hold most capacity as brands compete
Competition turns on three assets, which are line scale, fiber brands and specialty cuts for denim and nonwovens. Lenzing sells TENCEL lyocell for textiles and VEOCEL lyocell for nonwovens, and it is moving capacity toward the latter. Sateri, part of Royal Golden Eagle, is the largest producer by installed capacity and sells mainly staple to Chinese and export spinners. Grasim's Birla Cellulose runs Indian plants focused on nonwovens today and is building apparel-oriented capacity at Harihar. Tangshan Sanyou and Baoding Swan are Chinese producers that compete mainly on price, while Sanyou is adding recycled-content grades. Acelon in Taiwan makes lyocell filament and lyocell nonwoven cloth at Changhua. Lyocell fabric buyers weigh price per kilogram, certification and consistency, so brands earn premiums only where mills need traceability or special cuts.
A few spinners hold most capacity while weaving stays fragmented
Fiber supply is concentrated among a few producers with large solvent-spinning lines, led by Sateri, Lenzing and Grasim. Smaller Chinese producers such as Baoding Swan, which commissioned China's first 15,000-metric-ton line in January 2014, compete mainly on price. Entry barriers are solvent recovery know-how, line cost and the long qualification trials that brands and mills require. Margins sit in branded, nonwoven and specialty grades, while the downstream weaving and knitting stage remains fragmented across thousands of mills in Asia.
Leading lyocell producers and their roles
| Company | Type | Role in the market |
|---|---|---|
| Lenzing AG | Integrated branded producer | TENCEL lyocell staple and filament and VEOCEL nonwoven lyocell fibers |
| Sateri (Royal Golden Eagle) | Large-scale producer | Lyocell staple from four Chinese sites for spinners and nonwovens |
| Grasim Industries (Birla Cellulose, Aditya Birla Group) | Integrated producer | Lyocell staple from Kharach and Nagda, with Harihar lines under construction |
| Tangshan Sanyou Chemical Fiber Co., Ltd. | Chinese producer | Lyocell staple, including planned recycled-content grades using Circ pulp |
| Baoding Swan Fiber Co., Ltd. | Chinese specialist | Yuansi lyocell staple from its Baoding plant in Hebei |
| Acelon Chemicals & Fiber Corporation | Filament specialist | Greencell lyocell filament and lyocell nonwoven cloth from Changhua, Taiwan |
Volume moves east while margins move to nonwovens
Credence Research's view is that lyocell volume is moving east while the best margins are moving to nonwovens. Chinese and Indian lines will supply most new apparel staple, which keeps commodity prices close to viscose. Lenzing's exit from two European plants shows that a high-cost producer cannot win that contest on volume alone. Producers with pulp integration, wipes-grade fiber and recognized brands should hold value, while mid-sized producers without either scale or specialty grades face the hardest decade. Fabric mills gain more supply options in Asia but should weigh rising concentration among the three largest producers.
Producer capacity and price ranges anchor the model
The report uses 2025 as the base year and forecasts to 2035. Market values come from the Credence Research model, which carries this report's earlier 2024 estimate forward with its stated growth rate and checks the result against world lyocell output and producer price ranges. Inputs include producer annual reports and press releases, Textile Exchange fiber data, government regulation and trade press. Segment and regional splits are Credence Research estimates from these inputs. No interviews or surveys were used to build the estimates.
Indian lines and wipes rules set the pace to 2035
Through 2035 lyocell fabric demand growth should come from Indian capacity, Chinese export mills and wipes converters responding to plastic-free rules, while European production keeps shrinking. Denim and knit blends will absorb most new staple, and recycled-content grades should become a regular contract option after 2028. For buyers of dissolving wood pulp and fiber, the main uncertainty is price rather than volume, because new lines can keep commodity staple near viscose levels even as volumes rise, a range the scenarios below quantify.
Pricing versus viscose decides the 2035 value
The range of outcomes depends mainly on whether lyocell can hold a premium over viscose once new Chinese and Indian lines run at full rates. Volume growth looks secure in wipes and blends, but value growth needs stable prices. Faster spread of plastic-free wipes rules and on-time Indian commissioning would lift the upside, while a long period of idle Chinese lines would hold the market near the downside path.
| Scenario | CAGR, 2026–2035 | Value, 2035 | What has to hold |
|---|---|---|---|
| Downside | 4.8% | USD 2.33 billion | Chinese overcapacity keeps staple prices near viscose and Indian lines slip past 2028 |
| Base | 6.60% | USD 2.72 billion | Harihar and Thoothukudi start close to schedule and wipes rules hold in Europe |
| Upside | 7.8% | USD 3.00 billion | More countries ban plastic wipes and EU EPR fees favor certified cellulosic fiber |
Frequently Asked Questions
How big is the lyocell fabric market?
What is the lyocell price trend in India?
How much lyocell capacity does India have?
How is lyocell produced?
What is lyocell used for?
Who are the leading lyocell fabric suppliers?
What is the outlook for the North America lyocell fiber market?
Is lyocell a sustainable fiber?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product Type
- 1.2.1 Staple
- 1.2.2 Filament
- 1.3 By Fabric Type
- 1.3.1 Woven
- 1.3.2 Knitted
- 1.3.3 Nonwoven
- 1.4 By Application
- 1.4.1 Apparel
- 1.4.2 Home Textile
- 1.4.3 Hygiene
- 1.4.4 Healthcare
- 1.4.5 Automotive
- 1.4.6 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2025: USD 1.43 billion → 2035: USD 2.72 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Historical Period: 2018-2025
- 2.6.2 Base Year: 2025
- 2.6.3 Forecast Period: 2025-2035
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2025
- 3.3 Forecast Market Size, 2035
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Lyocell Fabric Market Trends and Developments
- 4.1 Historical Industry Development, 2018-2025
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Lyocell Fabric Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis, 2018-2025
- 5.2 Demand Forecast, 2025-2035
- 5.3 Production and Output Trend, 2018-2025
- 5.4 Production and Output Forecast, 2025-2035
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Lyocell Fabric Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends, 2018-2025
- 6.3 Pricing Outlook, 2025-2035
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Lyocell Fabric Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Lyocell Fabric Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Lyocell Fabric Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Lyocell Fabric Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Lyocell Fabric Market Outlook, 2025-2035
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2025: USD 1.43 billion → 2035: USD 2.72 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size, 2018-2025
- 11.1.4 Base-Year Market Size, 2025
- 11.2 Market Forecast, 2025-2035
- 11.2.1 Revenue Forecast to 2035
- 11.2.2 Volume Forecast to 2035
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Lyocell Fabric Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2025
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product Type - Market Size and Forecast, 2025-2035
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size, 2018-2025
- 12.3.3 Revenue Forecast, 2025-2035
- 12.3.4 Volume Forecast, 2025-2035
- 12.3.5 Base-Year Market Share, 2025
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Staple
- 12.3.7.2 Filament
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Fabric Type - Market Size and Forecast, 2025-2035
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size, 2018-2025
- 12.4.3 Revenue Forecast, 2025-2035
- 12.4.4 Volume Forecast, 2025-2035
- 12.4.5 Base-Year Market Share, 2025
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Woven
- 12.4.7.2 Knitted
- 12.4.7.3 Nonwoven
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2025-2035
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size, 2018-2025
- 12.5.3 Revenue Forecast, 2025-2035
- 12.5.4 Volume Forecast, 2025-2035
- 12.5.5 Base-Year Market Share, 2025
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Apparel
- 12.5.7.2 Home Textile
- 12.5.7.3 Hygiene
- 12.5.7.4 Healthcare
- 12.5.7.5 Automotive
- 12.5.7.6 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Lyocell Fabric End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Lyocell Fabric Geographic Market Outlook, 2025-2035
- 14.1 Regional Market Size and Share, 2025
- 14.2 Regional Market Forecast, 2025-2035
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Lyocell Fabric Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2025-2035
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Lyocell Fabric Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2025
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2025-2035
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Lenzing AG
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Sateri (Royal Golden Eagle)
- 18.4 Grasim Industries (Birla Cellulose, Aditya Birla Group)
- 18.5 Tangshan Sanyou Chemical Fiber Co., Ltd.
- 18.6 Baoding Swan Fiber Co., Ltd.
- 18.7 Acelon Chemicals & Fiber Corporation
- 18.8 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

