
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Medical Health Screening Services Market Size 2024 | USD 26565 million |
| Medical Health Screening Services Market, CAGR | 6% |
| Medical Health Screening Services Market Size 2032 | USD 42339.77 million |
Market Overview:
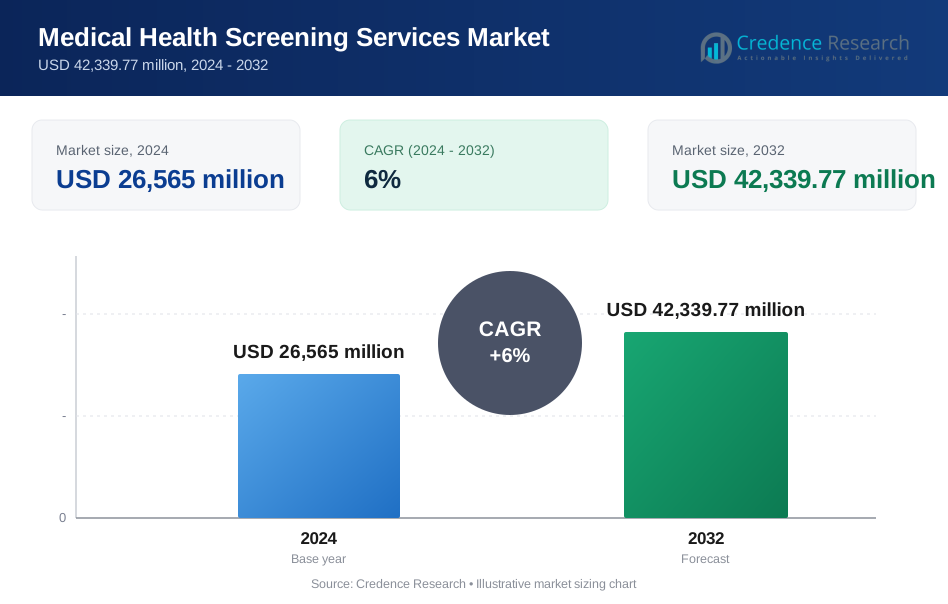
The Medical Health Screening Services Market is projected to grow from USD 26565 million in 2024 to an estimated USD 42339.77 million by 2032, with a compound annual growth rate (CAGR) of 6% from 2024 to 2032.
The growth of the medical health screening services market is driven by several factors, primarily the growing emphasis on preventive healthcare and early diagnosis. With the rise in chronic diseases such as diabetes, cancer, and cardiovascular diseases, early detection has become critical in improving patient outcomes. Governments and healthcare organizations worldwide are promoting regular health check-ups and screenings to reduce the burden of these diseases. Moreover, technological advancements in diagnostics, such as non-invasive and point-of-care testing, are making health screenings more accessible and efficient. The aging global population is another crucial driver, as elderly individuals are more susceptible to chronic conditions, leading to increased demand for health screening services. Additionally, the rise in corporate wellness programs and the growing popularity of personalized health screenings further contribute to market growth.
North America holds the largest share of the medical health screening services market, driven by the presence of advanced healthcare infrastructure, high awareness of preventive healthcare, and the widespread adoption of health screening services. The U.S., in particular, leads the region due to government initiatives that encourage routine health screenings and the high prevalence of chronic diseases. Europe follows closely, with countries like Germany, France, and the UK focusing on expanding preventive healthcare services to manage their aging populations. The Asia Pacific region is expected to witness the highest growth during the forecast period, fueled by rising healthcare awareness, increasing healthcare expenditure, and expanding access to screening services in countries such as China, Japan, and India. Latin America and the Middle East & Africa are also seeing gradual growth due to improving healthcare infrastructure and increased health awareness in these regions.
Market Drivers:
Rising Prevalence of Chronic Diseases:
One of the primary drivers of the medical health screening services market is the increasing prevalence of chronic diseases such as diabetes, cancer, cardiovascular diseases, and respiratory disorders. With lifestyle changes, poor dietary habits, and increased stress levels, these conditions are becoming more widespread, resulting in a growing need for early detection and preventive care. Health screenings play a crucial role in identifying risk factors and diagnosing diseases at an early stage, improving the chances of successful treatment and management. For instance, 133 million Americans – 45% of the population – have at least one chronic disease. As chronic diseases continue to rise globally, the demand for regular health screenings will likely increase, further propelling market growth.
Growing Awareness of Preventive Healthcare:
The growing awareness of the importance of preventive healthcare is another significant driver of the medical health screening services market. Governments, healthcare providers, and non-governmental organizations are launching awareness campaigns that encourage individuals to undergo regular health check-ups. These initiatives aim to educate the public about the benefits of early disease detection, especially for conditions that may remain asymptomatic in their early stages. Preventive healthcare also helps reduce healthcare costs in the long term by minimizing the need for expensive treatments through early interventions. As more people recognize the value of maintaining their health through regular screenings, the market for these services is expected to expand further.
Technological Advancements in Diagnostic Tools:
Advancements in diagnostic technologies are also playing a critical role in driving the medical health screening services market. New, innovative screening tools such as non-invasive testing, point-of-care diagnostics, and mobile health technologies have made health screenings more accessible, efficient, and accurate. These technological developments enable faster, more reliable results, allowing for timely interventions and improved patient outcomes. For example, Siemens Healthineers reported a revenue of $19 billion from diagnostics in 2021. The continuous innovation in diagnostic technologies is expected to significantly enhance the efficiency and reach of health screening services globally.
Aging Population and Increased Healthcare Spending:
The global aging population is another key factor fueling the growth of the medical health screening services market. Elderly individuals are at a higher risk of developing chronic diseases and are more likely to require regular health screenings to monitor their health conditions. As the proportion of the elderly population continues to rise, particularly in regions like North America, Europe, and Asia Pacific, the demand for screening services will likely increase. Furthermore, increased healthcare spending in both developed and developing countries is contributing to the market's growth. Governments and private healthcare providers are investing in the expansion of preventive healthcare services, including health screenings, to manage the growing burden of chronic diseases and aging populations. This shift toward preventive care is expected to drive further demand for medical health screening services globally.
Market Trends:
Increasing Adoption of Personalized Health Screening:
A growing trend in the medical health screening services market is the increasing adoption of personalized health screening programs. Consumers are becoming more interested in tailored healthcare solutions that address their specific needs and risk factors. Personalized screenings take into account an individual’s medical history, lifestyle, genetic predispositions, and other factors to provide customized recommendations for screenings and tests. This trend is particularly prominent among those looking to take a proactive approach to their health, and it allows for more targeted early detection and prevention of diseases. As healthcare providers and companies offer more personalized screening services, this trend is expected to drive further growth in the market.
Growth of Corporate Wellness Programs:
Corporate wellness programs are another emerging trend in the medical health screening services market. With growing awareness about employee health and well-being, companies are increasingly offering health screenings as part of their workplace wellness initiatives. These programs not only help detect health risks early but also promote a healthier workforce, leading to increased productivity and reduced absenteeism. For example, Johnson & Johnson implemented a wellness program that resulted in a reduction of 20,000 employee absentee days. The inclusion of regular health checks in corporate settings has become a key component of preventive healthcare strategies. Companies, particularly in regions such as North America and Europe, are investing in on-site and off-site screening services for their employees, contributing to the growing demand for health screening services.
Advancements in Telemedicine and Digital Health Tools:
The integration of telemedicine and digital health tools into health screening services is transforming how these services are delivered. Digital platforms are enabling patients to schedule, conduct, and review screening tests from the comfort of their homes. Telehealth consultations and the use of wearable devices that monitor key health indicators, such as heart rate, blood pressure, and glucose levels, are providing real-time data that can be used for regular health screening and monitoring. This trend has been further accelerated by the COVID-19 pandemic, as healthcare providers have increasingly turned to digital solutions to maintain patient engagement. The growing use of telemedicine is expected to continue expanding the reach and accessibility of health screening services globally.
Expansion of Screening Services in Emerging Markets:
Emerging markets, particularly in the Asia Pacific, Latin America, and Africa, are witnessing a growing demand for medical health screening services. Rising healthcare awareness, improving infrastructure, and increasing government efforts to promote preventive care are driving this trend. In countries such as China, India, and Brazil, the middle-class population is expanding, leading to greater demand for regular health check-ups. Governments in these regions are also investing in public health initiatives aimed at reducing the burden of chronic diseases through early detection. For example, Apollo Hospitals in India reported an increase of 30,000 health screenings conducted in the past year. As healthcare access improves in emerging economies, the demand for health screening services is projected to grow rapidly, creating new opportunities for providers in these regions.
Market Restraints and Challenges:
High Costs of Screening Services:
One of the key restraints in the medical health screening services market is the high cost associated with screening programs, particularly for advanced diagnostic tests. Many health screenings, especially those utilizing cutting-edge technologies such as genetic testing or comprehensive diagnostic imaging, can be expensive. For individuals without adequate insurance coverage, these costs can be prohibitive, limiting access to necessary screenings. Even in regions where public healthcare systems exist, budget constraints can prevent widespread availability of comprehensive screening services. This cost factor poses a significant challenge to the market's expansion, especially in lower-income populations and regions with less developed healthcare infrastructure.
Lack of Awareness and Accessibility:
Another significant challenge facing the medical health screening services market is the lack of awareness about the importance of regular health screenings, particularly in developing and rural areas. Many individuals are unaware of the benefits of early detection and preventive healthcare, resulting in underutilization of screening services. Additionally, in regions with poor healthcare infrastructure, access to screening services may be limited, further hindering the market's growth. In rural or remote areas, individuals often have to travel long distances to access healthcare facilities offering screening services, which can act as a deterrent to regular check-ups.
Privacy and Data Security Concerns:
With the increasing digitization of healthcare, privacy and data security concerns have emerged as challenges in the medical health screening services market. Health screenings involve sensitive personal and medical information, and any breaches in data security could lead to significant privacy risks. The fear of data misuse or unauthorized access can deter individuals from participating in screening programs, particularly as the use of digital health platforms and telemedicine grows. Ensuring robust data protection and maintaining patient trust is crucial to addressing this challenge and enabling the continued growth of the market.
Market Segmentation Analysis:
By Test type, the market includes routine tests, non-routine tests, cancer screening tests, specialty tests, and others. Routine tests, such as blood pressure and cholesterol checks, dominate the market due to their widespread use in preventive healthcare. Cancer screening tests, such as mammograms and colonoscopies, are also growing in demand as early detection becomes a priority.
By Setting type, hospitals and clinical laboratories hold a significant share of the market, as they are the primary locations for comprehensive health screening services. Workplaces and ambulatory care centers are also key settings, particularly with the rise of corporate wellness programs and convenient access to screenings outside traditional healthcare environments.
By Sample type, blood testing remains the most common, given its versatility in diagnosing various conditions. Urine and saliva tests are also widely used for specific screenings, with technological advancements enhancing their accuracy and convenience.
By End-users, with hospitals and clinics holding the largest share. Workplaces and diagnostic laboratories are also important players, as they increasingly offer health screenings to promote wellness and early disease detection. Research institutes, while a smaller segment, contribute to the market through specialized screenings and advanced diagnostic research.
Segmentation:
By Test Type
- Routine Tests
- Non-routine Tests
- Cancer Screening Tests
- Speciality Tests
- Others
By Setting Type
- Hospitals/Clinical Laboratories
- Workplaces
- Ambulatory Care Centers
- Multi-Speciality Clinics
- Diagnostic Imaging Centers
- Others
By Sample Type
- Blood
- Urine
- Saliva
- Others
By End-user
- Hospitals/Clinics Diagnostic Laboratories
- Workplaces
- Research Institutes
- Others
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds the largest market share in the global medical health screening services market, accounting for approximately 35% of the total market. The growth in this region is driven by several factors, including a well-established healthcare infrastructure, high awareness of preventive healthcare, and the widespread adoption of health screening services. The United States leads the region due to strong government initiatives promoting early disease detection, high healthcare spending, and a growing emphasis on corporate wellness programs. The prevalence of chronic diseases such as diabetes, cancer, and cardiovascular conditions further drives the demand for health screenings in this region. Canada also contributes significantly to the market, with increasing efforts to provide access to preventive healthcare services.
Europe
Europe follows North America, holding around 25% of the global market share. The region’s growth is supported by robust healthcare systems, widespread awareness of preventive health measures, and government-led health screening initiatives. Countries such as Germany, the UK, and France are at the forefront of adopting advanced screening technologies to combat the rising incidence of chronic diseases. The aging population in Europe is a key factor contributing to the demand for regular health screenings, particularly in detecting age-related conditions such as cancer and cardiovascular diseases. Additionally, European governments are emphasizing reducing healthcare costs through early diagnosis, further bolstering the market.
Asia Pacific
The Asia Pacific region is expected to witness the highest growth rate in the medical health screening services market, driven by rapid economic development, increasing healthcare spending, and rising awareness about preventive healthcare. The region currently holds about 20% of the market share. Countries like China, Japan, and India are experiencing increased demand for health screenings due to the growing prevalence of chronic diseases and the expansion of healthcare access. In China, the government’s focus on healthcare reform and the growing middle class are key drivers of market growth. Similarly, India’s increasing healthcare infrastructure and awareness of preventive care are contributing to the rising demand for screening services.
Latin America and Middle East & Africa
Latin America and the Middle East & Africa (MEA) together account for around 15% of the global market share. These regions are experiencing gradual growth, driven by improving healthcare infrastructure, increasing urbanization, and growing awareness of the importance of early disease detection. In Latin America, countries like Brazil and Mexico are seeing rising demand for health screening services due to the increasing prevalence of chronic diseases. In the Middle East & Africa, healthcare reforms and efforts to expand access to preventive care are supporting the market's growth, although these regions still face challenges such as limited healthcare access in rural areas and high costs associated with advanced screenings.
Key Player Analysis:
- ACM Medical Laboratory
- Clinical Reference Laboratory
- Eurofins Scientific
- Healthscope
- LabCorp
- LifeLabs
- Quest Diagnostics
- Sonic Healthcare
- SYNLAB International
- Unilabs
Competitive Analysis:
The medical health screening services market is highly competitive, with a mix of global and regional players offering a wide range of screening services. Key market players include large healthcare providers like Quest Diagnostics, LabCorp, and Siemens Healthineers, which dominate due to their extensive diagnostic capabilities, advanced technologies, and widespread network of laboratories. These companies offer comprehensive health screening services, from routine blood tests to specialized cancer screenings, enabling them to capture a significant portion of the market. In addition to these major players, smaller regional service providers and diagnostic centers also compete by offering tailored, cost-effective screening solutions. Corporate wellness companies are another growing segment, partnering with businesses to provide on-site health screenings for employees. Technological advancements, particularly in telehealth and digital health platforms, are also creating opportunities for new entrants, increasing competition as companies strive to offer more accessible, efficient, and personalized screening services to meet the growing demand for preventive healthcare.
Recent Developments:
- In July 2024, Truvian Health raised $74 million in funding to accelerate the development of its automated blood-testing platform. The company is also collaborating with Drug Mart in Canada to obtain FDA approval.
- In 2024, DELFI Diagnostics received an investment from the Merck Global Health Innovation Fund to further enhance their AI-driven cancer screening technology.
Market Concentration & Characteristics:
The medical health screening services market is moderately fragmented, with a mix of global corporations, specialized healthcare providers, and regional diagnostic centers. Major players such as Quest Diagnostics, LabCorp, and Siemens Healthineers hold a significant share due to their vast networks, advanced screening technologies, and comprehensive service offerings. These companies dominate the market by providing a wide range of tests, from routine screenings to advanced diagnostics, and leverage technological advancements to maintain a competitive edge. Despite the presence of large companies, numerous smaller and regional providers compete by offering localized, cost-effective services, often focusing on specific tests or patient groups. The market is also witnessing the rise of digital health platforms and telehealth services, which are enhancing accessibility and convenience for consumers. Overall, the market's concentration is shaped by technological innovation, corporate partnerships, and growing demand for preventive healthcare, creating both opportunities and competition across various service segments.
Report Coverage:
The research report offers an in-depth analysis based on By Test Type, By Setting Type, By Sample Type and By End-user. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The medical health screening services market is expected to grow steadily, driven by increasing demand for preventive healthcare.
- Rising awareness of chronic diseases will continue to fuel demand for early detection and screening services.
- Technological advancements in diagnostics, such as AI and telehealth, will enhance accessibility and accuracy.
- Corporate wellness programs will expand, increasing demand for workplace health screenings.
- Personalized screening services will gain popularity as consumers seek tailored healthcare solutions.
- Emerging markets, particularly in Asia Pacific, will experience rapid growth due to expanding healthcare infrastructure.
- The aging population will contribute to increased demand for screenings, particularly for age-related diseases.
- Non-invasive and point-of-care testing methods will become more widespread, enhancing patient convenience.
- Public-private partnerships will support the expansion of health screening initiatives in underserved regions.
- Digital health platforms will play a larger role in delivering remote and home-based screening services.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence of Chronic Diseases
The increasing incidence of chronic conditions such as diabetes, cancer, and cardiovascular diseases is driving demand for early detection and regular health screenings, as these services are critical for timely intervention and improved patient outcomes.
Growing Awareness of Preventive Healthcare
Government initiatives, public health campaigns, and employer-sponsored wellness programs are raising awareness about the benefits of preventive care, encouraging more individuals to undergo regular health screenings and boosting market growth.
Technological Advancements in Diagnostics
Innovations such as non-invasive testing, point-of-care diagnostics, and digital health platforms are making screening services more accessible, efficient, and accurate, thereby expanding the reach and appeal of medical health screening services.
Aging Global Population
As the proportion of elderly individuals increases worldwide, the demand for regular health screenings rises, since older adults are more susceptible to chronic diseases and require ongoing monitoring for early detection and management.
Expansion in Emerging Markets
Improving healthcare infrastructure, rising healthcare expenditure, and increasing health awareness in emerging economies - especially in Asia Pacific and Latin America - are creating new opportunities and driving rapid growth in the adoption of health screening services.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Medical Health Screening Services Market?
What factors are driving the growth of the Medical Health Screening Services Market?
What role does technology play in the Medical Health Screening Services Market?
What challenges does the Medical Health Screening Services Market face?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-user
- 1.2.1 Hospitals/Clinics Diagnostic Laboratories
- 1.2.2 Workplaces
- 1.2.3 Research Institutes
- 1.2.4 Others
- 1.3 By Test Type
- 1.3.1 Routine Tests
- 1.3.2 Non-routine Tests
- 1.3.3 Cancer Screening Tests
- 1.3.4 Speciality Tests
- 1.3.5 Others
- 1.4 By Sample Type
- 1.4.1 Blood
- 1.4.2 Urine
- 1.4.3 Saliva
- 1.4.4 Others
- 1.5 By Setting Type
- 1.5.1 Hospitals/Clinical Laboratories
- 1.5.2 Workplaces
- 1.5.3 Ambulatory Care Centers
- 1.5.4 Multi-Speciality Clinics
- 1.5.5 Diagnostic Imaging Centers
- 1.5.6 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 26,565 million → 2032: USD 42,339.77 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Medical Health Screening Services Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Medical Health Screening Services Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Medical Health Screening Services Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Medical Health Screening Services Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Medical Health Screening Services Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Medical Health Screening Services Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Medical Health Screening Services Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Medical Health Screening Services Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 26,565 million → 2032: USD 42,339.77 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Medical Health Screening Services Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-user - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Base-Year Market Share, 2024
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Hospitals/Clinics Diagnostic Laboratories
- 12.3.6.2 Workplaces
- 12.3.6.3 Research Institutes
- 12.3.6.4 Others
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Test Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Base-Year Market Share, 2024
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Routine Tests
- 12.4.6.2 Non-routine Tests
- 12.4.6.3 Cancer Screening Tests
- 12.4.6.4 Speciality Tests
- 12.4.6.5 Others
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Sample Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Base-Year Market Share, 2024
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Blood
- 12.5.6.2 Urine
- 12.5.6.3 Saliva
- 12.5.6.4 Others
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 By Setting Type - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Base-Year Market Share, 2024
- 12.6.5 Segment CAGR and Growth Drivers
- 12.6.6 Subsegment Market Size and Forecast
- 12.6.6.1 Hospitals/Clinical Laboratories
- 12.6.6.2 Workplaces
- 12.6.6.3 Ambulatory Care Centers
- 12.6.6.4 Multi-Speciality Clinics
- 12.6.6.5 Diagnostic Imaging Centers
- 12.6.6.6 Others
- 12.6.7 Subsegment Pricing and Adoption Trends
- 12.6.8 Leading Suppliers and Competition
- 12.6.9 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Medical Health Screening Services End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Medical Health Screening Services Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Medical Health Screening Services Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Energy Efficiency and Resource Management
- 15.7 Sustainability, Recycling and Circularity
- 15.8 Technology Roadmap, 2024-2032
- 15.9 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Medical Health Screening Services Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Quest Diagnostics
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 LabCorp
- 18.4 Siemens Healthineers
- 18.5 Eurofins Scientific
- 18.6 Sonic Healthcare
- 18.7 SYNLAB International
- 18.8 Unilabs
- 18.9 LifeLabs
- 18.10 Healthscope
- 18.11 ACM Medical Laboratory
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

