
Market Overview:
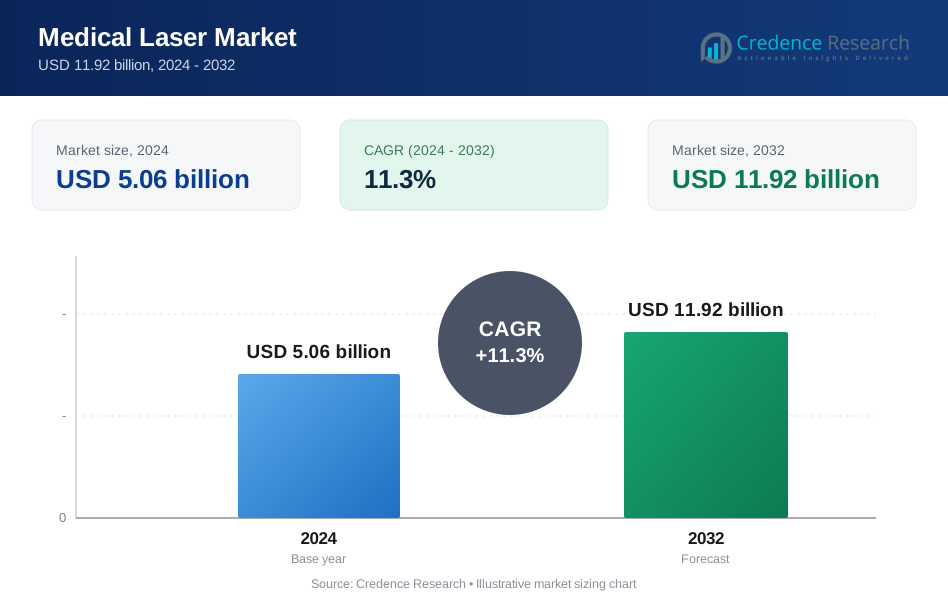
The medical laser market size was valued at USD 5.06 billion in 2024 and is anticipated to reach USD 11.92 billion by 2032, at a CAGR of 11.3 % during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Medical Laser Market Size 2024 | USD 5.06 billion |
| Medical Laser Market, CAGR | 11.3% |
| Medical Laser Market Size 2032 | USD 11.92 billion |
Key drivers shaping this market include the growing demand for non-invasive treatments in dermatology, ophthalmology, and cosmetic surgeries. Increasing prevalence of chronic diseases requiring precise surgical interventions further supports adoption. Technological innovations such as diode, solid-state, and fiber lasers enhance accuracy and patient outcomes, while the rising focus on aesthetics and anti-aging solutions expands consumer demand.
Regionally, North America leads the medical laser market due to advanced healthcare infrastructure, high adoption of innovative treatments, and favorable reimbursement policies. Europe follows closely, supported by a strong regulatory framework and growing use of laser-based therapies. Asia-Pacific is expected to record the fastest growth, fueled by expanding medical tourism, rising healthcare expenditure, and greater awareness of advanced procedures in countries like China, India, and South Korea. Meanwhile, Latin America and the Middle East & Africa show steady adoption, supported by growing investments in healthcare modernization.

Market Insights:
- The medical laser market was valued at USD 5.06 billion in 2024 and is projected to reach USD 11.92 billion by 2032, growing at a CAGR of 11.3% during 2024–2032.
- Rising demand for minimally invasive procedures is driving adoption in dermatology, ophthalmology, and dentistry due to shorter recovery times and reduced risks.
- The increasing prevalence of chronic and age-related diseases such as cancer, cardiovascular disorders, and eye conditions supports growing use of laser-based therapies.
- Technological innovations in diode, solid-state, and fiber lasers are enhancing treatment safety, portability, and clinical efficiency across multiple specialties.
- Expanding applications in aesthetics, including hair removal, skin resurfacing, and anti-aging solutions, are fueling demand in hospitals and specialty clinics.
- High costs, limited accessibility in developing regions, and stringent regulatory requirements remain significant challenges for manufacturers and providers.
- North America held 38% market share in 2024, Europe accounted for 29%, and Asia-Pacific captured 23%, with Asia-Pacific expected to grow fastest due to medical tourism and healthcare investments.
Market Drivers:
Growing Demand for Minimally Invasive Procedures:
The medical laser market is expanding due to the rising preference for minimally invasive treatments. Patients seek procedures with reduced recovery time, less pain, and lower risks compared to traditional surgery. Medical lasers provide precision, making them ideal for dermatology, ophthalmology, and dental applications. It is gaining traction in both hospital and outpatient settings, reflecting strong patient and physician acceptance.
- For instance, Lumenis' LightSheer Quattro laser platform offers a high-speed vacuum-assisted handpiece and ChillTip cooling technology, delivering permanent hair reduction with clinical studies showing significant efficacy sustained at 6, 9, and 12 months post-treatment, with typical sessions requiring 6 to 9 treatments spaced 4-6 weeks apart and minimal recovery time of just a few hours.
Rising Prevalence of Chronic and Age-Related Diseases:
Chronic conditions such as cardiovascular disorders, cancer, and eye diseases are driving demand for advanced treatment solutions. The medical laser market benefits from its ability to deliver accurate and targeted therapy. Aging populations across developed and emerging economies require laser-based interventions in ophthalmology and dermatology. It continues to gain importance as healthcare systems prioritize effective and less invasive care.
- For instance, Bausch + Lomb's TENEO excimer laser received FDA approval after a study involving over 300 eyes demonstrated stable refractive outcomes with a mean spherical equivalent of minus 0.04 maintained up to 9 months post-treatment in myopic LASIK procedures, marking a significant achievement in precision ophthalmic laser technology.
Technological Advancements and Innovation in Laser Systems:
Continuous improvements in diode, solid-state, and fiber laser technologies enhance treatment outcomes and safety. The medical laser market is witnessing innovation in compact, portable, and user-friendly devices. Integration with advanced imaging and robotic systems boosts surgical precision and efficiency. It is expected to drive broader adoption among healthcare providers seeking advanced tools for complex treatments.
Expanding Applications in Aesthetics and Cosmetic Procedures:
Aesthetic and cosmetic applications are contributing significantly to global demand. The medical laser market benefits from increasing interest in anti-aging, hair removal, skin resurfacing, and body contouring treatments. Rising disposable incomes and awareness of appearance-focused healthcare support this trend. It is creating opportunities for clinics, hospitals, and specialized centers to expand service offerings and attract new patient groups.
Market Trends:
Integration of Advanced Technologies and Expanding Clinical Applications:
The medical laser market is experiencing strong growth with the integration of advanced technologies into clinical practice. Innovations in diode, solid-state, and fiber lasers are enhancing precision, safety, and treatment versatility. It is also benefiting from the adoption of robotic-assisted systems and AI-based imaging tools, which improve accuracy in surgeries and diagnostics. Expanding applications in oncology, cardiology, and dentistry highlight the versatility of laser systems beyond traditional cosmetic and dermatology uses. Healthcare providers are increasingly adopting compact and portable devices, making treatments more accessible in clinics and ambulatory centers. The growing focus on patient-centered care is driving hospitals to invest in laser technologies that deliver better outcomes and shorter recovery times.
- For instance, ROHM pioneered the use of Molecular Beam Epitaxy (MBE) technology in laser diode manufacturing, establishing mass production technology by 1984 with stable laser output around 5mW, setting industry standards for quality and precision in laser devices.
Rising Focus on Aesthetics, Non-Invasive Care, and Emerging Markets :
Aesthetic and cosmetic treatments continue to play a central role in shaping industry trends. The medical laser market is gaining momentum from rising consumer demand for anti-aging procedures, tattoo removal, and skin resurfacing. It is also expanding rapidly in emerging economies, where rising healthcare investments and medical tourism are creating new opportunities. Demand for non-invasive and outpatient procedures is pushing clinics to diversify their offerings with advanced laser-based solutions. Rising awareness of personalized and preventive healthcare is further supporting the adoption of medical lasers across regions. Growing competition among key players is leading to increased R&D efforts, with companies launching innovative devices tailored to both clinical and cosmetic needs. This trend highlights the dual role of lasers in improving health outcomes and enhancing patient lifestyles.
- For Instance, Candela's PicoWay Resolve handpiece for the 730 nm wavelength delivers pulses as short as 250 picoseconds. These ultra-short pulses are designed to fragment tattoo ink more effectively while minimizing thermal damage to the surrounding skin, especially when compared to older laser technologies.
Market Challenges Analysis:
High Costs and Limited Accessibility in Developing Regions:
The medical laser market faces challenges due to the high cost of devices and maintenance. Advanced laser systems require significant investment, making them less accessible for smaller clinics and hospitals in developing regions. It also faces barriers from limited reimbursement policies, which restrict adoption for both cosmetic and medical procedures. Shortages of trained professionals further limit effective usage, particularly in rural and low-resource settings. Unequal distribution of healthcare infrastructure reduces the reach of advanced treatments, slowing market penetration in emerging economies. These factors create disparities in access and adoption worldwide.
Regulatory Complexities and Safety Concerns:
Strict regulatory standards and approval processes pose obstacles for manufacturers. The medical laser market must comply with varying rules across regions, which can delay product launches. It is also challenged by safety concerns related to misuse, device malfunction, or inadequate operator training. Reports of side effects in cosmetic procedures can reduce patient confidence and adoption rates. Intense competition pressures companies to innovate while ensuring compliance, which increases development costs. These regulatory and safety hurdles remain key concerns for manufacturers and healthcare providers.
Market Opportunities:
Expansion into Emerging Economies and Growing Medical Tourism:
The medical laser market holds strong opportunities in emerging economies where healthcare infrastructure is rapidly improving. Rising disposable incomes and expanding private healthcare networks are boosting demand for advanced treatments. It is benefiting from medical tourism, particularly in Asia-Pacific and Latin America, where cost-effective procedures attract international patients. Governments are investing in modern healthcare technologies, creating a favorable environment for adoption. Clinics and hospitals in these regions are increasingly adopting laser-based solutions to meet growing patient demand. This expansion offers manufacturers new revenue streams and long-term growth potential.
Innovation in Aesthetic and Therapeutic Applications:
Continuous innovation is unlocking new applications for medical lasers across aesthetic and therapeutic segments. The medical laser market is seeing rising demand for skin rejuvenation, tattoo removal, and hair removal services. It also benefits from breakthroughs in oncology, cardiology, and ophthalmology, where lasers improve precision and reduce recovery times. Portable and user-friendly devices are opening opportunities for smaller practices and outpatient centers. Rising awareness of preventive healthcare and lifestyle enhancement supports broader acceptance of laser-based solutions. These advancements position the industry to capture diverse consumer and clinical needs worldwide.
Market Segmentation Analysis:
By Type:
The medical laser market is segmented by type into diode lasers, solid-state lasers, gas lasers, and dye lasers. Diode lasers dominate due to their compact size, lower cost, and wide use in dermatology and dentistry. Solid-state lasers maintain strong demand in ophthalmology and oncology for their precision and stability. Gas lasers continue to hold relevance in surgical and therapeutic procedures requiring high-intensity beams. It is expected that diode and solid-state lasers will see the fastest adoption due to their versatility and efficiency.
- For instance, the DEKA SmartXide² TRIO integrates a 980 nm diode laser that provides surgeons with unmatched precision and flexibility during ENT and minimally invasive surgeries, improving control in delicate procedures with enhanced safety and efficiency
By Product:
Key product categories include surgical lasers, aesthetic lasers, and therapeutic lasers. Surgical lasers account for a significant portion, driven by applications in ophthalmology, oncology, and general surgery. Aesthetic lasers are gaining momentum due to rising demand for skin resurfacing, tattoo removal, and body contouring. Therapeutic lasers are expanding in physiotherapy, dentistry, and pain management applications. It is anticipated that aesthetic lasers will grow rapidly, supported by consumer focus on wellness and appearance.
- For instance, Alcon’s femtosecond laser used in ophthalmic surgery achieves a laser precision with a standard deviation of approximately 4 micrometers, enabling highly accurate corneal tissue removal critical for refractive surgery outcomes.
By End User:
Hospitals, specialty clinics, and ambulatory surgical centers represent the main end users. Hospitals lead due to advanced infrastructure and access to high-cost surgical systems. Specialty clinics are expanding their role, particularly in dermatology and cosmetic procedures. Ambulatory surgical centers are adopting portable devices, making care more accessible and cost-effective. It is clear that demand is shifting toward outpatient facilities due to growing preference for minimally invasive care.
Segmentations:
By Type:
- Diode Lasers
- Solid-State Lasers
- Gas Lasers
- Dye Lasers
By Product:
- Surgical Lasers
- Aesthetic Lasers
- Therapeutic Lasers
By End User:
- Hospitals
- Specialty Clinics
- Ambulatory Surgical Centers
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis:
North America:
North America accounted for 38% market share in 2024, making it the largest regional segment. The medical laser market in this region benefits from advanced healthcare infrastructure and early adoption of innovative technologies. It is supported by favorable reimbursement frameworks and high demand for minimally invasive procedures. Strong presence of key manufacturers and continuous product launches strengthen competitiveness. Growing interest in cosmetic treatments and aging demographics drive demand across hospitals and clinics. Expanding outpatient care centers further reinforce the adoption of medical laser solutions in the United States and Canada.
Europe:
Europe held 29% market share in 2024, supported by strict regulatory standards and high clinical adoption. The medical laser market in this region thrives on strong emphasis on patient safety and effective treatment outcomes. It is driven by advanced medical systems in countries such as Germany, France, and the United Kingdom. Rising demand for dermatology, ophthalmology, and dental procedures strengthens usage across both public and private healthcare settings. Government-led initiatives promoting non-invasive care foster wider adoption. Increasing investment in research and education ensures consistent growth in this regional market.
Asia-Pacific:
Asia-Pacific captured 23% market share in 2024, positioning it as the fastest-growing regional market. The medical laser market benefits from rapid healthcare modernization in China, India, South Korea, and Japan. It is supported by expanding medical tourism, increasing healthcare spending, and rising consumer awareness. Strong demand for cosmetic treatments drives adoption in both urban and semi-urban centers. Governments are investing in advanced medical technologies to enhance patient care and clinical capacity. Growing partnerships between global players and local providers fuel innovation and market expansion in this region.
Key Player Analysis:
- Lumenix
- Photomedex
- Philips Healthcare
- BIOLASE, Inc.
- IRIDEX Corporation
- BioForm Medical, Inc.
- biolitec AG
- Cutera
- Candela Corporation
- Cynosure
Competitive Analysis:
The medical laser market is highly competitive, shaped by global leaders and innovative specialists. Key players include Lumenix, Photomedex, Philips Healthcare, BIOLASE, Inc., IRIDEX Corporation, BioForm Medical, Inc., and biolitec AG. These companies focus on product innovation, strategic collaborations, and geographic expansion to strengthen their positions. It is characterized by continuous investment in research and development, driving advancements in precision, portability, and treatment versatility. Strong emphasis on aesthetic and surgical applications enables firms to tap into growing demand across hospitals and clinics. Competitive differentiation often relies on technology leadership, cost efficiency, and regulatory compliance, creating pressure on smaller players. The market remains dynamic, with companies seeking to expand into emerging economies and capitalize on medical tourism trends.
Recent Developments:
- In September 2025, Lumenix announced a multi-year collaboration agreement with McGill University Health Centre (MUHC) to deploy its Artificially Intelligent Monitoring System (AIMS) platform aimed at enhancing patient safety and supporting care staff through ambient perception AI technology.
- In June 2025, Philips Healthcare launched the Flash 5100 Point-of-Care (POC) Ultrasound system, designed to provide rapid and high-quality ultrasound imaging targeted for emergency, anesthesia, and critical care applications.
- In January 2025, Bridgefield Capital entered into a definitive agreement to acquire Philips Emergency Care Business, a global leader in emergency care solutions, with the transaction expected to finalize later in 2025.
Report Coverage:
The research report offers an in-depth analysis based on Type, Product, End User and Region. It details leading Market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current Market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven Market expansion in recent years. The report also explores Market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on Market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the Market.
Future Outlook:
- Rising demand for non-invasive and outpatient procedures will continue to drive adoption across specialties.
- Advancements in diode, solid-state, and fiber lasers will improve treatment efficiency and broaden clinical applications.
- Expanding use in oncology, cardiology, and ophthalmology will strengthen the role of lasers in complex therapies.
- Growing awareness of aesthetics and anti-aging treatments will boost demand in cosmetic and dermatology segments.
- Emerging economies with expanding healthcare infrastructure will provide significant growth opportunities for manufacturers.
- Portable and user-friendly devices will increase accessibility for smaller clinics and outpatient centers.
- Integration of AI, robotics, and imaging technologies will enhance precision and improve surgical outcomes.
- Medical tourism in Asia-Pacific and Latin America will support international demand for cost-effective laser procedures.
- Collaborations between global players and regional providers will accelerate innovation and product reach.
- Greater emphasis on patient safety and regulatory compliance will guide product development and clinical adoption.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Demand for Minimally Invasive Procedures
Patients and healthcare providers increasingly prefer minimally invasive treatments due to shorter recovery times, reduced pain, and lower risk compared to traditional surgery. Medical lasers enable precise interventions in dermatology, ophthalmology, and dentistry, driving adoption in both hospital and outpatient settings.
Rising Prevalence of Chronic and Age-Related Diseases
The increasing incidence of chronic conditions such as cancer, cardiovascular disorders, and eye diseases is fueling the need for advanced, targeted therapies. Medical lasers offer accurate and less invasive treatment options, particularly for aging populations in both developed and emerging markets.
Technological Advancements in Laser Systems
Continuous innovation in diode, solid-state, and fiber laser technologies is enhancing treatment safety, portability, and clinical efficiency. Integration with imaging and robotic systems is expanding the range of procedures that can be performed with lasers, making them more attractive to healthcare providers.
Expanding Applications in Aesthetics and Cosmetic Procedures
Rising consumer interest in anti-aging, hair removal, skin resurfacing, and body contouring is significantly boosting demand for medical lasers. Increased disposable incomes and awareness of appearance-focused healthcare are driving growth in hospitals, specialty clinics, and outpatient centers.
Healthcare Modernization and Medical Tourism in Emerging Markets
Rapid improvements in healthcare infrastructure, rising healthcare expenditure, and the growth of medical tourism - especially in Asia-Pacific and Latin America - are creating new opportunities for medical laser adoption. Governments and private providers are investing in advanced technologies to attract both local and international patients.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Medical Laser Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Medical Laser Market projected to grow between 2024 and 2032?
What are the primary factors fueling the growth of the Medical Laser Market?
Who are the leading companies in the Medical Laser Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Diode Lasers
- 1.2.2 Solid-State Lasers
- 1.2.3 Gas Lasers
- 1.2.4 Dye Lasers
- 1.3 By Product
- 1.3.1 Surgical Lasers
- 1.3.2 Aesthetic Lasers
- 1.3.3 Therapeutic Lasers
- 1.4 By End User
- 1.4.1 Hospitals
- 1.4.2 Specialty Clinics
- 1.4.3 Ambulatory Surgical Centers
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 5.06 billion → 2032: USD 11.92 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Medical Laser Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Medical Laser Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Medical Laser Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Medical Laser Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Medical Laser Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Medical Laser Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Medical Laser Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Medical Laser Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 5.06 billion → 2032: USD 11.92 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Medical Laser Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Diode Lasers
- 12.3.7.2 Solid-State Lasers
- 12.3.7.3 Gas Lasers
- 12.3.7.4 Dye Lasers
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Surgical Lasers
- 12.4.7.2 Aesthetic Lasers
- 12.4.7.3 Therapeutic Lasers
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End User - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Hospitals
- 12.5.7.2 Specialty Clinics
- 12.5.7.3 Ambulatory Surgical Centers
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Medical Laser End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Medical Laser Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Medical Laser Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Medical Laser Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Lumenix
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Photomedex
- 18.4 Philips Healthcare
- 18.5 BIOLASE, Inc.
- 18.6 IRIDEX Corporation
- 18.7 BioForm Medical, Inc.
- 18.8 biolitec AG
- 18.9 Cutera
- 18.10 Candela Corporation
- 18.11 Cynosure
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

