
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Metal Deactivator Additives Market Size 2024 | USD 244.2 million |
| Metal Deactivator Additives Market, CAGR | 5.40% |
| Metal Deactivator Additives Market Size 2032 | USD 371.9 million |
Market overview
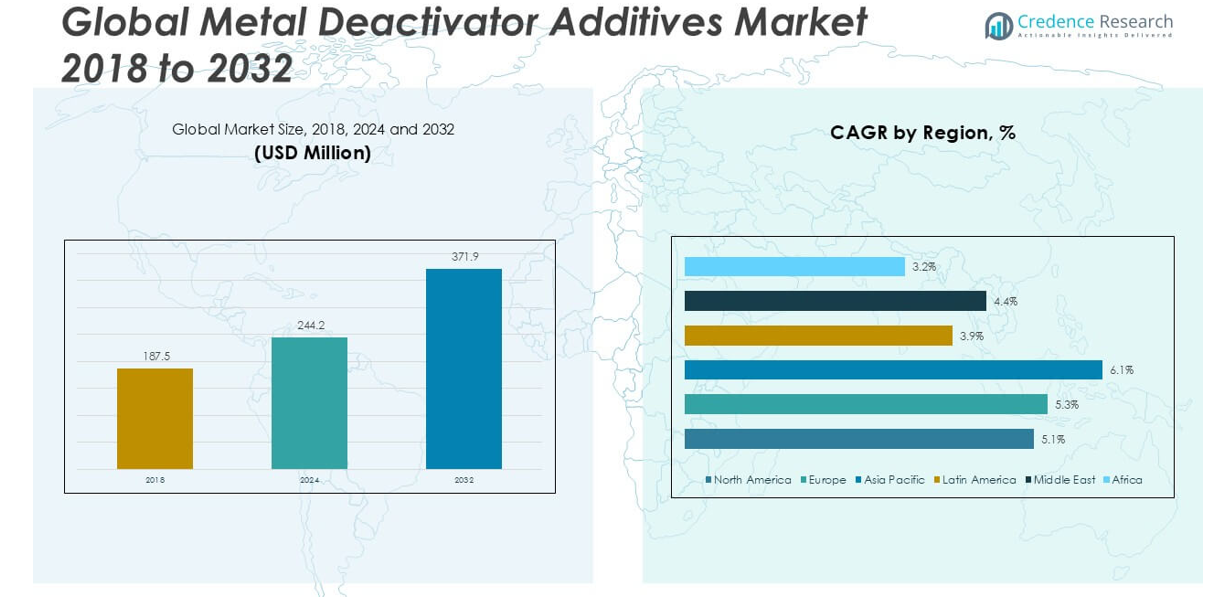
The Metal Deactivator Additives market size was valued at USD 187.5 million in 2018, increased to USD 244.2 million in 2024, and is anticipated to reach USD 371.9 million by 2032, at a CAGR of 5.40% during the forecast period.
The Metal Deactivator Additives market is shaped by key players such as Afton Chemical Corporation, The Lubrizol Corporation, BASF SE, Chevron Oronite Company LLC, Innospec Inc., and Dorf Ketal Chemicals, who actively drive innovation through advanced additive formulations and strategic regional expansions. These companies focus on enhancing additive performance to meet the growing demands of automotive, industrial, and polymer applications. Asia Pacific leads the global market, holding approximately 38% of the total market share in 2024, driven by rapid industrialization, expanding automotive production, and increasing consumption across manufacturing sectors. North America and Europe follow as significant contributors, supported by high-performance lubricant demand and stringent regulatory compliance. The market remains competitive, with a strong emphasis on sustainable, multi-functional solutions.
Market Insights
- The Metal Deactivator Additives market was valued at USD 187.5 million in 2018, reached USD 244.2 million in 2024, and is expected to attain USD 371.9 million by 2032, growing at a CAGR of 5.40% during the forecast period.
- Increasing demand from the automotive sector for enhanced fuel stability and engine longevity is a key driver, with the copper segment holding the largest market share due to its wide application in fuel systems.
- A strong market trend is the shift toward sustainable and multifunctional metal deactivator formulations, with leading companies focusing on environmentally friendly and high-performance additives.
- The market faces restraints such as stringent environmental regulations and raw material price volatility, which challenge manufacturers in product development and pricing stability.
- Asia Pacific dominates the global market with around 38% share in 2024, while the automotive end-use segment leads overall consumption across all regions.
Market Segmentation Analysis:
By Metal Type:
In the Metal Deactivator Additives market, the copper segment dominates, accounting for a significant market share due to its widespread use in fuels, lubricants, and polymers where copper ions accelerate oxidation and degradation. The high susceptibility of copper to catalytic degradation drives the demand for effective metal deactivators to improve product stability and longevity. Additionally, copper’s extensive applications in automotive radiators, electrical systems, and industrial machinery contribute to its leading position. The aluminum and alloy segments are also growing steadily, supported by rising demand in aviation and automotive sectors, though their market shares remain secondary to copper.
- For instance, Chevron Oronite Company LLC introduced OLOA® 49800, which reduced aluminum-induced oxidation by 2.5 mg of sludge formation in a 100-hour bench test.
By End Use Industry
The automotive segment holds the largest share in the Metal Deactivator Additives market, driven by the high requirement for additives in fuel systems and lubricants to prevent metal-catalyzed oxidation, which can compromise engine performance. Increasing global vehicle production and the growing focus on fuel efficiency and engine longevity support the dominance of this segment. The industrial segment also contributes significantly, with demand stemming from machinery and equipment maintenance. Meanwhile, the aviation, food & agriculture, and polymers sectors present moderate growth opportunities, supported by the need to enhance product stability and meet stringent performance standards in specialized applications.
- For instance, Innospec Inc. developed Trident™ 6200 specifically for polymer systems, which improved oxidative color retention by 6 Hunter Lab color units after accelerated aging tests.
Market Overview
Rising Demand from Automotive Industry
The automotive sector significantly drives the growth of the Metal Deactivator Additives market. Increasing vehicle production and the growing emphasis on enhancing fuel efficiency and engine life have accelerated the adoption of these additives. Metal deactivators prevent catalytic oxidation caused by metal ions, thereby improving fuel stability and lubricant performance. As manufacturers prioritize cleaner engines and longer service intervals, the demand for efficient metal deactivator formulations continues to grow, particularly in regions with strict emission and performance standards.
- For instance, Infineum International Limited’s Infineum P6130 achieved a reduction in deposit formation by 25 mg per 50 ml of oil in diesel engine bench tests conducted over 100 hours.
Expansion of Industrial Applications
Industrial machinery and equipment heavily rely on metal deactivator additives to maintain operational efficiency and minimize maintenance costs. The growing use of metal deactivators in various industrial lubricants and fluids helps prevent oxidation and sludge formation, enhancing the lifespan of machinery components. Increasing investments in manufacturing, mining, and heavy equipment sectors globally contribute to the rising consumption of these additives, creating consistent demand from industrial end users aiming to improve reliability and reduce downtime.
- For instance, LANXESS’s Additin® RC 8230 lowered wear scar diameter by 0.06 mm in the Four Ball Wear Test conducted on mining equipment hydraulic fluids.
Growing Polymer and Packaging Sector
The polymer industry presents a substantial growth driver for the Metal Deactivator Additives market, particularly in packaging applications where metal contamination can accelerate product degradation. Metal deactivators are essential in polymer processing to prevent discoloration and loss of material properties caused by metal traces. The expanding packaging sector, driven by food safety regulations and consumer demand for durable products, further supports the use of these additives. Their ability to ensure polymer stability and improve product shelf life strengthens their market relevance.
Key Trends & Opportunities
Increasing Demand for High-Performance Additives
The market is witnessing a growing preference for advanced, multi-functional metal deactivator additives that offer superior thermal stability and compatibility across diverse base fluids. Manufacturers are focusing on developing next-generation additives that perform effectively under extreme temperature and pressure conditions. This trend is particularly prominent in high-performance automotive and aviation applications, presenting opportunities for additive producers to introduce differentiated products that meet evolving technical standards and customer requirements.
- For instance, Evonik Industries AG’s VISCOPLEX® metal deactivator maintained thermal stability up to 240°C without additive degradation during extended lubricant heat tests.
Rising Focus on Sustainable Formulations
There is a notable trend towards environmentally friendly and low-toxicity metal deactivator additives driven by stringent regulatory pressures and sustainability goals. Companies are increasingly investing in the development of non-toxic, biodegradable additive solutions that align with green chemistry principles. This shift opens opportunities for innovation in sustainable formulations that can serve industries aiming to reduce their environmental footprint while maintaining product performance, especially in sectors like food packaging and agriculture.
- For instance, Croda International Plc launched CrodaTherm™ MDA, which achieved complete degradation in 21 days under simulated composting conditions in accordance with ISO 14855 standards.
Key Challenges
Stringent Regulatory Compliance
The Metal Deactivator Additives market faces challenges in meeting evolving regulatory standards related to environmental impact and chemical safety. Regulatory bodies, particularly in Europe and North America, impose strict restrictions on the use of certain chemicals, driving the need for continuous reformulation. Adapting to these changing requirements increases production costs and slows the introduction of new products, posing a significant challenge for manufacturers seeking to maintain competitiveness.
Volatility in Raw Material Prices
Fluctuating raw material costs present a persistent challenge for the Metal Deactivator Additives market. Key ingredients used in additive production are often subject to price variations influenced by global supply chain disruptions, geopolitical tensions, and fluctuating crude oil prices. This cost instability can negatively affect profit margins for additive manufacturers and may lead to higher end-product pricing, impacting customer adoption in cost-sensitive industries.
Limited Awareness in Emerging Markets
One of the key obstacles to market expansion is the limited awareness and adoption of metal deactivator additives in emerging economies. Many small-scale manufacturers in these regions may not fully understand the benefits of metal deactivators in extending product life and improving performance. This lack of awareness can restrict market penetration and growth potential, especially in industries where cost minimization is prioritized over product longevity and quality enhancement.
Regional Analysis
North America
In the Metal Deactivator Additives market, North America accounted for USD 45.9 million in 2018 and reached USD 54.9 million in 2024. The market is projected to grow to USD 74.4 million by 2032, registering a CAGR of 5.1% during the forecast period. North America holds approximately 22.5% of the global market share in 2024, supported by robust demand from the automotive and industrial sectors. The region's emphasis on high-performance lubricants and stringent regulatory compliance regarding engine efficiency continues to drive growth. Technological advancements and the presence of leading automotive manufacturers further enhance regional consumption.
Europe
Europe held a significant position in the Metal Deactivator Additives market, with a value of USD 49.7 million in 2018, increasing to USD 61.1 million in 2024. The market is expected to reach USD 85.5 million by 2032, growing at a CAGR of 5.3%. Europe represents around 25% of the global market share in 2024, driven by strong automotive production and widespread use in industrial applications. The region's commitment to sustainable and high-performance additives fuels continuous product innovation. Additionally, strict environmental policies across the European Union have accelerated the adoption of advanced metal deactivator solutions.
Asia Pacific
Asia Pacific leads the Metal Deactivator Additives market, with a market size of USD 67.9 million in 2018, expanding to USD 92.8 million in 2024. It is projected to reach USD 159.9 million by 2032, growing at the fastest CAGR of 6.1%. Asia Pacific holds approximately 38% of the global market share in 2024, supported by rapidly growing automotive, industrial, and polymer sectors in countries like China, India, and Japan. The increasing focus on manufacturing, rising vehicle production, and expanding consumer goods sectors continue to propel demand, positioning the region as the key growth hub globally.
Latin America
In Latin America, the Metal Deactivator Additives market was valued at USD 7.9 million in 2018 and reached USD 11.0 million in 2024. It is projected to grow to USD 18.6 million by 2032, at a CAGR of 3.9% during the forecast period. The region accounts for around 4.5% of the global market share in 2024. Growth is driven by the gradual development of the automotive and industrial sectors, especially in Brazil and Mexico. However, the market remains relatively small due to lower levels of industrialization and limited adoption of advanced additive technologies in some parts of the region.
Middle East
The Middle East Metal Deactivator Additives market recorded USD 11.3 million in 2018, increasing to USD 14.7 million in 2024. The market is anticipated to reach USD 23.1 million by 2032, growing at a CAGR of 4.4%. The Middle East holds approximately 6% of the global market share in 2024. The demand is primarily driven by the industrial sector, lubricants market, and moderate automotive demand. Investments in manufacturing and increasing industrialization, particularly in Gulf Cooperation Council (GCC) countries, support market expansion. However, the market is still emerging compared to more mature regions such as North America and Europe.
Africa
Africa’s Metal Deactivator Additives market was valued at USD 4.9 million in 2018, rising to USD 9.8 million in 2024. It is expected to reach USD 10.4 million by 2032, growing at a CAGR of 3.2%. Africa represents approximately 4% of the global market share in 2024. The region shows limited growth due to lower industrial penetration and slower adoption rates of advanced additive technologies. However, gradual infrastructure development and increasing automotive activities in select countries like South Africa and Egypt offer moderate opportunities. The market remains in its early growth stage with potential for expansion in the long term.
Market Segmentations:
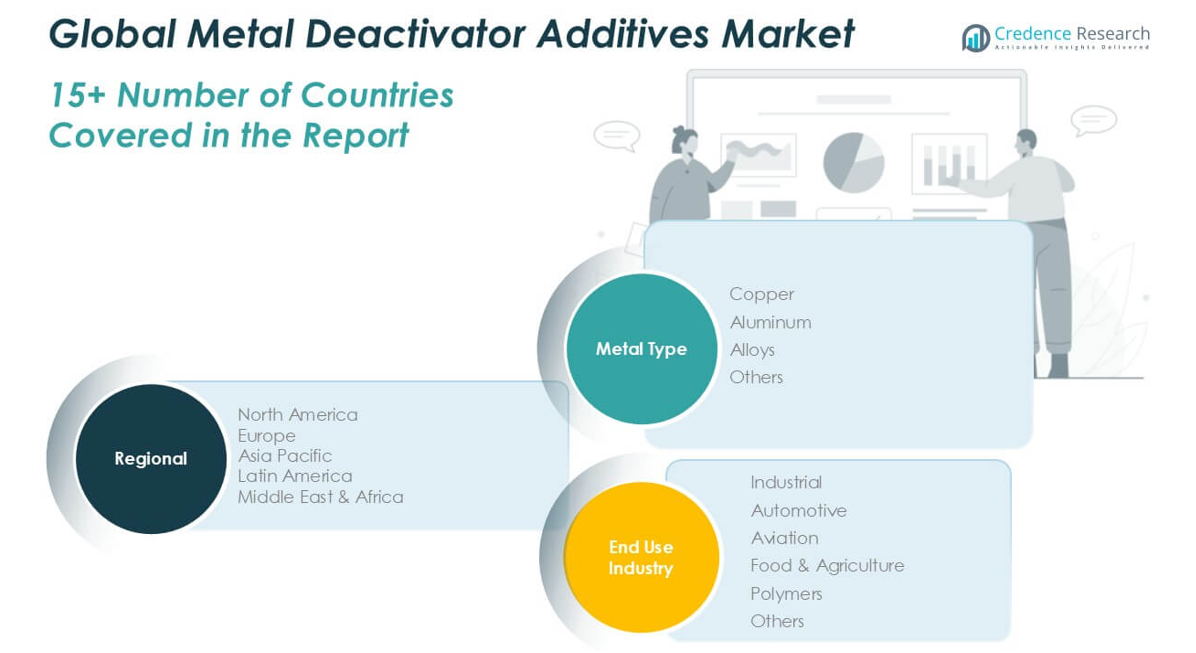
By Metal Type:
- Copper
- Aluminum
- Alloys
- Others
By End Use Industry:
- Industrial
- Automotive
- Aviation
- Food & Agriculture
- Polymers
- Others
By Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Metal Deactivator Additives market is moderately consolidated, with key players focusing on product innovation, strategic partnerships, and geographic expansion to strengthen their market positions. Leading companies such as Afton Chemical Corporation, The Lubrizol Corporation, BASF SE, and Chevron Oronite Company LLC actively invest in research and development to offer advanced, multi-functional additives that meet evolving industry standards. These players emphasize improving additive efficiency and compatibility with diverse base fluids to cater to the automotive, industrial, and polymer sectors. Companies like Innospec Inc. and Dorf Ketal Chemicals are expanding their regional presence through collaborations and distribution agreements to capture emerging market opportunities in Asia Pacific and Latin America. Additionally, sustainability is becoming a competitive focus, with several manufacturers developing environmentally friendly formulations to comply with stringent regulatory requirements. The market's competitive dynamics are driven by continuous product differentiation, expanding application portfolios, and a growing emphasis on meeting customer-specific performance requirements across diverse end-use industries.
Key Player Analysis
- Afton Chemical Corporation
- The Lubrizol Corporation
- BASF SE
- Chevron Oronite Company LLC
- Innospec Inc.
- Dorf Ketal Chemicals
- LANXESS
- Infineum International Limited
- King Industries, Inc.
- ADEKA Corporation
- PMC Group, Inc.
- Croda International Plc
- Clariant AG
- Evonik Industries AG
Recent Developments
- In 2025, Afton Chemicalcontinues to enhance its portfolio of metal deactivator additives. These additives, crucial for fuel stability, neutralize the catalytic effects of metals like copper and iron, which can cause gum and sediment formation by accelerating fuel oxidation. Even trace amounts of these metals can significantly impact fuel stability, making metal deactivators essential.
- In 2025, Chevron Oronite is continuing its focus on developing innovative fuel and lubricant additive technology, particularly for lower carbon solutions and advanced testing. While R&D efforts are ongoing, there are no specific new metal deactivator products publicly announced by the company so far this year.
- In December 2024, Lubrizol announced new innovations, emphasizing sustainability, agile development, and local manufacturing, but didn't specifically mention new metal deactivator additives. Despite this, Lubrizol is recognized as a key player in the metal deactivator additives market and actively invests in R&D for rapid product development.
- In October 2024, Dorf Ketal introduced a breakthrough “reactive adjunct chemistry” for desalting, which, while not a traditional metal deactivator additive, represents a significant innovation in metals removal and process protection for refineries. This technology enhances desalter efficiency, improves rag layer control, and offers advanced metals removal solutions, especially for challenging crudes. Dorf Ketal’s portfolio also includes solutions specifically for metals removal in desalters, helping protect refining assets from metal-catalyzed issues.
Market Concentration & Characteristics
The Metal Deactivator Additives Market is moderately concentrated, with a few key players controlling a significant portion of the global supply. It features strong competition among established companies that focus on advanced product development and strategic partnerships to expand their reach. The market is characterized by a high degree of technical expertise, driven by the need for additives that offer superior thermal stability and broad fluid compatibility. It demands strict compliance with environmental and safety regulations, which influences both product formulation and market entry barriers. Companies continuously invest in research to develop sustainable and high-performance solutions that align with evolving industry standards. It exhibits consistent demand from the automotive, industrial, and polymer sectors, where metal deactivators play a critical role in enhancing product life and operational efficiency. The competitive landscape encourages differentiation through innovative, multi-functional additive solutions. Emerging markets, particularly in Asia Pacific, present significant growth opportunities, supported by expanding manufacturing activities and rising consumer awareness. It also faces challenges linked to raw material price fluctuations and regulatory complexities that require constant monitoring and product adaptation.
Report Coverage
The research report offers an in-depth analysis based on Metal Type, End Use Industry and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for metal deactivator additives will grow steadily in the automotive sector due to the focus on improving fuel stability and engine performance.
- Manufacturers will continue to develop environmentally friendly and sustainable additive formulations to meet stricter global regulations.
- The Asia Pacific region will remain the fastest-growing market, supported by rapid industrialization and increasing automotive production.
- Companies will invest more in research and development to create multi-functional additives with higher thermal stability and broader application compatibility.
- The polymer and packaging industries will drive additional demand for metal deactivators to prevent product degradation and extend material life.
- Partnerships, mergers, and acquisitions will become key strategies for market players aiming to strengthen global distribution networks.
- Rising demand from the aviation sector will create new growth avenues for high-performance metal deactivator additives.
- The market will face ongoing challenges related to fluctuating raw material costs and supply chain disruptions.
- Adoption of metal deactivator additives in emerging markets will increase as awareness of their benefits improves among manufacturers.
- Regulatory changes will continue to shape product innovation, pushing companies to prioritize safer and more compliant additive solutions.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Automotive Production and Focus on Engine Longevity
The automotive sector is the largest consumer of metal deactivator additives, driven by increasing global vehicle production and the need to enhance fuel stability and engine life. Metal deactivators are essential in preventing metal-catalyzed oxidation in fuel systems and lubricants, supporting cleaner engines and longer service intervals.
Expansion of Industrial and Manufacturing Activities
Industrial machinery and equipment require metal deactivator additives to prevent oxidation and extend component life. Growing investments in manufacturing, mining, and heavy equipment sectors globally are increasing the demand for these additives to improve operational efficiency and reduce maintenance costs.
Growth in Polymer and Packaging Applications
The polymer industry, especially in packaging, relies on metal deactivator additives to prevent discoloration and degradation caused by metal contamination. The expanding packaging sector, driven by food safety regulations and consumer demand for durable products, is boosting the use of these additives to ensure product stability and shelf life.
Shift Toward Sustainable and Multi-Functional Additives
Stringent environmental regulations and sustainability goals are pushing manufacturers to develop environmentally friendly, low-toxicity, and biodegradable metal deactivator formulations. This trend is opening new opportunities for innovation and market growth, particularly in regions with strict regulatory standards.
Technological Advancements and Product Innovation
Key market players are investing in R&D to create advanced, multi-functional metal deactivator additives with superior thermal stability and compatibility across diverse applications. These innovations are meeting the evolving technical requirements of high-performance automotive, aviation, and industrial sectors, further driving market expansion.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Metal Deactivator Additives Market?
What are the key segments within the Metal Deactivator Additives Market?
What are some challenges faced by the Metal Deactivator Additives Market?
Who are the major players in the Metal Deactivator Additives Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Metal Type
- 1.2.1 Copper
- 1.2.2 Aluminum
- 1.2.3 Alloys
- 1.2.4 Others
- 1.3 By End Use Industry
- 1.3.1 Automotive
- 1.3.2 Industrial
- 1.3.3 Aviation
- 1.3.4 Food & Agriculture
- 1.3.5 Polymers
- 1.3.6 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 244.2 million → 2032: USD 371.9 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Metal Deactivator Additives Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Metal Deactivator Additives Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Metal Deactivator Additives Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Metal Deactivator Additives Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Metal Deactivator Additives Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Metal Deactivator Additives Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Metal Deactivator Additives Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Metal Deactivator Additives Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 244.2 million → 2032: USD 371.9 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Metal Deactivator Additives Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Metal Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Copper
- 12.3.7.2 Aluminum
- 12.3.7.3 Alloys
- 12.3.7.4 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End Use Industry - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Automotive
- 12.4.7.2 Industrial
- 12.4.7.3 Aviation
- 12.4.7.4 Food & Agriculture
- 12.4.7.5 Polymers
- 12.4.7.6 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Metal Deactivator Additives End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Metal Deactivator Additives Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Metal Deactivator Additives Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Metal Deactivator Additives Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Afton Chemical Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 The Lubrizol Corporation
- 18.4 BASF SE
- 18.5 Chevron Oronite Company LLC
- 18.6 Innospec Inc.
- 18.7 Dorf Ketal Chemicals
- 18.8 LANXESS
- 18.9 Infineum International Limited
- 18.10 Croda International Plc
- 18.11 Evonik Industries AG
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

