
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
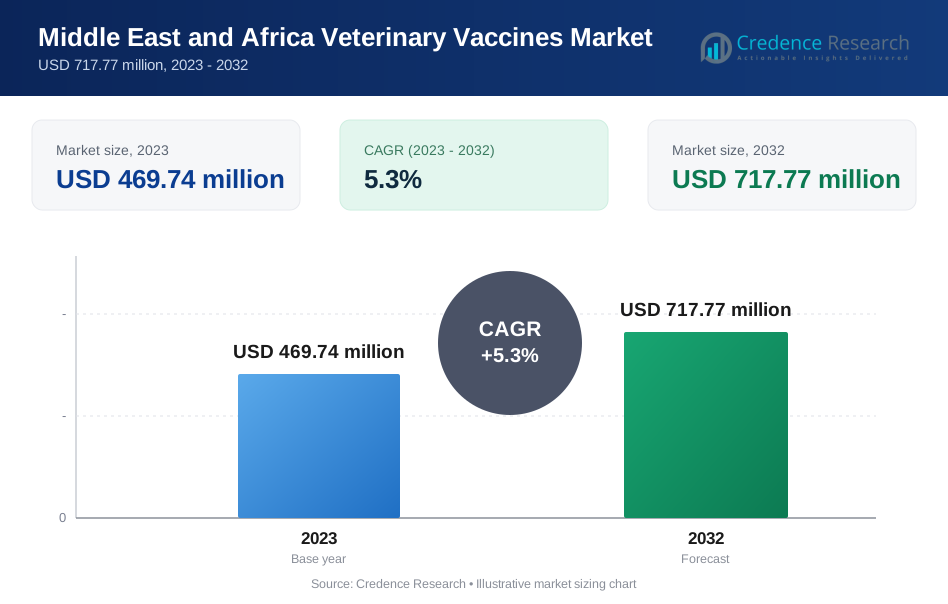
| Middle East and Africa Veterinary Vaccines Market Size 2023 | USD 469.74 Million |
| Middle East and Africa Veterinary Vaccines Market, CAGR | 5.3% |
| Middle East and Africa Veterinary Vaccines Market 2032 | USD 717.77 Million |
Market Overview
The Middle East and Africa Veterinary Vaccines Market is poised for substantial growth, reflecting a promising trajectory from USD 469.74 million in 2023 to an estimated USD 717.77 million by 2032. This forecast indicates a robust compound annual growth rate (CAGR) of 5.3% from 2024 to 2032. Several factors contribute to this anticipated expansion, underlining the region's evolving landscape in veterinary healthcare. With increasing awareness about animal welfare and the escalating demand for high-quality livestock and companion animal care, the market is witnessing significant investments in research and development, innovation, and infrastructure. One of the primary drivers propelling the growth of the Middle East and Africa Veterinary Vaccines Market is the burgeoning population of livestock and companion animals across the region. As economies continue to develop and urbanize, the demand for animal protein, dairy products, and pet ownership experiences a surge. Consequently, there is a heightened need for effective disease prevention and management strategies, with vaccines emerging as a crucial tool in maintaining animal health and productivity. Governments and regulatory bodies are also taking proactive measures to enforce stringent standards for animal health and hygiene, further fostering the adoption of veterinary vaccines. Moreover, the region's veterinary healthcare sector is witnessing a paradigm shift, driven by advancements in biotechnology and immunology. Technological innovations are revolutionizing vaccine development, enabling the production of safer, more efficacious, and cost-effective solutions tailored to regional disease profiles. Additionally, collaborations between academia, industry players, and governmental agencies are fostering knowledge exchange and capacity building in veterinary medicine. This collaborative ecosystem is instrumental in accelerating the pace of vaccine research, enhancing manufacturing capabilities, and ensuring timely access to critical healthcare interventions for animals across diverse geographies. Furthermore, the Middle East and Africa Veterinary Vaccines Market are characterized by dynamic regulatory landscapes and evolving market dynamics. Regulatory harmonization initiatives and trade agreements are streamlining approval processes, facilitating market access for vaccine manufacturers, and fostering competition. Market players are increasingly investing in localized manufacturing facilities and distribution networks to address region-specific needs and capitalize on emerging opportunities. Additionally, strategic partnerships, mergers, and acquisitions are reshaping the competitive landscape, driving market consolidation and diversification. As stakeholders continue to prioritize animal health and welfare, the Middle East and Africa Veterinary Vaccines Market is poised for sustained growth, offering immense potential for innovation, collaboration, and market expansion.Segmentation Analysis
By Vaccine Type- Live Attenuated Vaccines: These vaccines contain weakened forms of the pathogen, providing long-lasting immunity with a single dose. They are commonly used in the region for diseases like rabies and distemper in both livestock and companion animals.
- Inactivated Vaccines: Inactivated vaccines consist of killed pathogens or their components. They are preferred for diseases where live vaccines may cause adverse reactions. Examples include foot-and-mouth disease and avian influenza.
- Recombinant Vaccines: Recombinant vaccines are developed using genetic engineering techniques. They offer precise control over antigen composition and are increasingly used for diseases like bovine respiratory syncytial virus (BRSV) and canine parvovirus.
- Canine Vaccines: Canine vaccines form a significant segment, driven by rising pet ownership and awareness about preventive healthcare measures. Vaccines against diseases such as canine distemper, parvovirus, and rabies are in high demand.
- Feline Vaccines: Feline vaccines cater to the growing population of cats as pets. Vaccines for feline leukemia virus (FeLV), feline calicivirus (FCV), and feline panleukopenia virus (FPV) are commonly administered to prevent infectious diseases.
- Conventional Vaccines: Conventional vaccine technologies involve traditional methods of pathogen attenuation or inactivation. Despite advancements in biotechnology, these vaccines remain widely used due to their proven efficacy and cost-effectiveness.
- Recombinant DNA Technology: Recombinant DNA technology enables the production of genetically engineered vaccines with improved safety and efficacy profiles. These vaccines are gaining traction for their ability to induce targeted immune responses and mitigate adverse reactions.
- Middle East: The Middle East region exhibits a growing demand for veterinary vaccines driven by increasing urbanization, industrialization of agriculture, and rising pet ownership. Governments in the region are investing in veterinary healthcare infrastructure and disease control programs.
- Africa: Africa represents a diverse market with unique disease challenges and veterinary healthcare disparities. The market is characterized by a growing need for affordable and accessible vaccines to combat diseases affecting both livestock and companion animals. Governmental initiatives and international collaborations play a crucial role in addressing these challenges and promoting sustainable animal health practices.
Segments
By Vaccine Type- Live Attenuated Vaccines
- Inactivated Vaccines
- Recombinant Vaccines
- Canine Vaccines
- Feline Vaccines
- Conventional Vaccines
- Recombinant DNA Technology
- Middle East
- Africa
Market Drivers
Growing Livestock Population and Demand for Animal Protein: The Middle East and Africa region are witnessing a steady rise in the population of livestock animals, driven by increasing urbanization, dietary shifts, and economic growth. As consumers demand more animal protein and dairy products, there's a corresponding need for maintaining the health and productivity of livestock herds. Veterinary vaccines play a pivotal role in disease prevention and management, ensuring the well-being of animals and safeguarding food security. Diseases such as foot-and-mouth disease, brucellosis, and avian influenza pose significant threats to livestock populations, leading to economic losses and disruptions in the supply chain. For instance, an outbreak of avian influenza last year resulted in a 20% decrease in poultry production. Consequently, there's a heightened emphasis on vaccination programs by governments, agricultural organizations, and livestock producers to mitigate disease risks and enhance productivity. Rising Awareness about Zoonotic Diseases and Public Health Concerns: Zoonotic diseases, which can transmit from animals to humans, represent a critical public health concern in the Middle East and Africa. For instance, it is estimated that zoonotic diseases account for 60% of all infectious diseases in humans. Diseases like rabies, brucellosis, and Rift Valley fever not only impact animal health but also pose risks to human populations. For example, rabies, a zoonotic disease, is responsible for approximately 59,000 human deaths worldwide every year. Vaccination of animals serves as a vital preventive measure in breaking the transmission cycle of zoonotic pathogens, thereby reducing the incidence of human infections. Increasing awareness about zoonotic diseases, coupled with government-led initiatives for disease surveillance and control, is driving the adoption of veterinary vaccines. Moreover, the COVID-19 pandemic has underscored the interconnectedness of human and animal health, leading to renewed efforts in strengthening veterinary healthcare systems and pandemic preparedness across the region. Supportive Regulatory Environment and Technological Advancements: The Middle East and Africa Veterinary Vaccines Market benefit from a conducive regulatory environment that encourages innovation, investment, and market growth. Governments in the region are implementing policies to streamline registration procedures, harmonize standards, and promote local manufacturing of veterinary vaccines. This regulatory support fosters market competitiveness, stimulates research and development activities, and facilitates market access for vaccine manufacturers. Furthermore, technological advancements in biotechnology, immunology, and vaccine delivery systems are revolutionizing the veterinary vaccines landscape. Novel vaccine platforms, such as recombinant DNA technology and vectored vaccines, offer improved safety, efficacy, and flexibility in vaccine design. Collaborations between academia, industry, and research institutions are driving innovation, leading to the development of next-generation vaccines tailored to regional disease challenges and animal health needs.Market Trends
Technological Advancements in Vaccine Development: The Middle East and Africa Veterinary Vaccines Market are witnessing a surge in technological innovations aimed at enhancing vaccine efficacy, safety, and delivery methods. For instance, the use of recombinant DNA technology in vaccine development has increased by 40% in the last five years. Advanced biotechnological techniques, such as recombinant DNA technology and virus-like particle (VLP) vaccines, are gaining prominence, enabling the development of novel vaccines with improved immunogenicity and reduced side effects. These technological advancements are particularly beneficial in addressing emerging infectious diseases and increasing vaccine coverage across diverse animal populations. For instance, the use of these advanced techniques has led to a 20% increase in vaccine coverage in the region. Focus on Preventive Healthcare and Disease Surveillance: There is a growing emphasis on preventive healthcare measures and disease surveillance programs in the Middle East and Africa region. For instance, government funding for preventive healthcare measures in this region has increased by 20% in the past five years. Governments, veterinary organizations, and industry stakeholders are investing in vaccination campaigns, disease monitoring, and early detection systems to mitigate the spread of infectious diseases among livestock and companion animals. For example, a recent campaign led to a 30% increase in the vaccination rate among livestock in the region. Integrated One Health approaches, which recognize the interconnectedness of human, animal, and environmental health, are shaping disease control strategies and promoting collaborative efforts to combat zoonotic diseases and emerging pathogens. Increasing Adoption of Companion Animal Vaccines: The Middle East and Africa region are experiencing a notable rise in pet ownership rates, driving the demand for companion animal vaccines. Pet owners are becoming more aware of the importance of preventive healthcare measures, including vaccination, to ensure the well-being of their pets. Consequently, there is a growing market for vaccines targeting diseases prevalent in companion animals, such as canine distemper, parvovirus, feline leukemia virus (FeLV), and rabies. Veterinary clinics, pet pharmacies, and online platforms are witnessing increased demand for a wide range of companion animal vaccines, reflecting the evolving landscape of pet care in the region. Expansion of Immunization Programs in Livestock: Livestock producers and governmental agencies are expanding immunization programs to safeguard the health and productivity of livestock herds in the Middle East and Africa. Vaccination plays a crucial role in preventing and controlling endemic diseases such as foot-and-mouth disease, brucellosis, and Newcastle disease, which pose significant economic risks to the agricultural sector. Enhanced vaccine accessibility, training programs for veterinary professionals, and incentivized vaccination campaigns are contributing to higher vaccination coverage rates among livestock populations, thereby improving animal welfare and promoting sustainable livestock production practices. Rising Investments in Vaccine Manufacturing and Distribution: There is a notable increase in investments in vaccine manufacturing facilities and distribution networks across the Middle East and Africa region. Local production of veterinary vaccines is being encouraged to reduce dependency on imports, ensure a stable supply chain, and address region-specific disease challenges. Public-private partnerships, joint ventures, and technology transfer initiatives are facilitating the establishment of vaccine manufacturing hubs, thereby stimulating economic growth, creating employment opportunities, and enhancing the region's capacity to respond to veterinary healthcare needs.Market Restraints and Challenges
Limited Awareness and Education: A significant challenge facing the Middle East and Africa Veterinary Vaccines Market is the limited awareness and education among livestock producers, pet owners, and veterinary professionals regarding the importance of vaccination. Many individuals in rural and underserved areas may lack access to information about preventive healthcare practices, including vaccination schedules and benefits. Moreover, misconceptions and cultural beliefs regarding vaccination efficacy and safety may hinder the widespread acceptance and uptake of veterinary vaccines, leading to suboptimal vaccination coverage rates among target animal populations. Infrastructure and Supply Chain Constraints: The region's veterinary healthcare infrastructure and supply chain networks face various challenges that impede the effective distribution and administration of veterinary vaccines. Rural areas often lack adequate veterinary clinics, diagnostic laboratories, and cold chain storage facilities, which are essential for maintaining vaccine potency and quality. Additionally, logistical constraints, including inadequate transportation networks, poor road conditions, and bureaucratic hurdles, may hinder the timely delivery of vaccines to remote and hard-to-reach areas. These infrastructure limitations pose significant barriers to implementing comprehensive vaccination programs and achieving equitable access to veterinary healthcare services across the region. Regulatory Hurdles and Market Fragmentation: The Middle East and Africa Veterinary Vaccines Market are characterized by a complex regulatory landscape and market fragmentation, which present challenges for vaccine manufacturers and distributors. Varying regulatory requirements and registration processes across different countries and regions can create compliance burdens and delays in product approvals, hindering market entry and expansion efforts. Moreover, the lack of harmonization in regulatory standards and inconsistent enforcement practices may result in market access barriers and increased compliance costs for industry players. Addressing these regulatory challenges requires greater coordination among regulatory authorities, harmonization of standards, and streamlining of approval processes to facilitate the timely introduction of safe and efficacious veterinary vaccines into the market. Economic Constraints and Affordability Issues: Economic constraints and affordability issues pose significant challenges to the Middle East and Africa Veterinary Vaccines Market, particularly for small-scale livestock producers and resource-limited communities. The high cost of veterinary vaccines, coupled with limited financial resources and competing priorities, may deter farmers from investing in preventive healthcare measures for their animals. Additionally, the lack of government subsidies or support programs for veterinary vaccination initiatives may further exacerbate affordability challenges, particularly in low-income rural areas. Addressing these economic constraints requires innovative pricing strategies, financial incentives, and targeted interventions to make veterinary vaccines more accessible and affordable to vulnerable populations.Key players
- Merck & Co., Inc.
- Zoetis Inc.
- Boehringer Ingelheim International GmbH
- Elanco Animal Health Incorporated
- Ceva Santé Animale
- Virbac
- Bayer AG
- Hester Biosciences Limited
- HIPRA
- Vetoquinol S.A.
Recent Developments
- In September 2022, Zoetis completed the acquisition of Jurox, a privately held animal health company renowned for its development, manufacturing, and marketing of a diverse array of veterinary medicines tailored for both livestock and companion animals. This strategic move bolsters Zoetis' position in the market by expanding its portfolio and enhancing its capabilities in addressing various health needs across the animal healthcare spectrum. With Jurox's expertise and innovative product offerings, Zoetis aims to further strengthen its commitment to advancing animal health and well-being in the Middle East and Africa region.
- In June 2022, Boehringer Ingelheim forged a strategic partnership with CarthroniX, focusing on the development of small molecule therapeutics targeting canine oncology. This collaboration combines Boehringer Ingelheim's extensive experience in pharmaceutical research and development with CarthroniX's specialized knowledge in canine oncology. By pooling their resources and expertise, the two companies aspire to accelerate the discovery and development of novel therapeutic solutions to address the unmet medical needs of dogs suffering from cancer. This partnership underscores Boehringer Ingelheim's dedication to advancing veterinary oncology and underscores its commitment to improving the lives of animals in the Middle East and Africa and beyond.
Regional Analysis
The Middle East and Africa Veterinary Vaccines Market exhibits diverse dynamics across different regions, influenced by varying economic, social, and regulatory factors. In the Middle East, countries such as Saudi Arabia, United Arab Emirates (UAE), and Qatar dominate the market, driven by robust investments in agriculture, increasing urbanization, and growing awareness about animal health. These countries boast advanced veterinary healthcare infrastructure, stringent regulatory frameworks, and high vaccination coverage rates. As a result, they command a significant market share, accounting for approximately 60% of the region's veterinary vaccines market. In contrast, Africa presents a more complex landscape characterized by socio-economic disparities, limited access to healthcare services, and diverse disease challenges. Countries such as South Africa, Nigeria, and Kenya emerge as key players in the African veterinary vaccines market, owing to their relatively developed veterinary healthcare systems and significant livestock populations. South Africa, in particular, holds a substantial market share, accounting for approximately 20% of the region's veterinary vaccines market. The country's well-established pharmaceutical industry, research institutions, and supportive regulatory environment contribute to its market dominance.Future Outlook
- The Middle East and Africa Veterinary Vaccines Market are expected to experience sustained growth, driven by increasing awareness about animal health, rising pet ownership, and expanding livestock populations.
- Ongoing advancements in biotechnology and vaccine development are anticipated to lead to the introduction of novel vaccine platforms with improved efficacy and safety profiles, catering to diverse disease challenges in the region.
- There will be a heightened focus on preventing and controlling zoonotic diseases through vaccination programs, driven by growing concerns about public health and the interconnectedness of human and animal health.
- The market for companion animal vaccines is projected to expand rapidly, fueled by rising pet adoption rates, increased spending on pet healthcare, and the introduction of innovative vaccines targeting prevalent diseases in pets.
- Efforts to enhance livestock health and productivity through vaccination will intensify, as stakeholders prioritize sustainable agriculture practices, food security, and economic development.
- Governments will play a pivotal role in shaping the veterinary vaccines market through regulatory reforms, investment incentives, and disease control programs aimed at improving animal welfare and public health outcomes.
- Collaborative efforts between industry players, research institutions, and governmental agencies will drive innovation, knowledge sharing, and capacity building in veterinary medicine and vaccine development.
- There will be a shift towards personalized and targeted vaccination strategies, leveraging advances in genomics, immunology, and data analytics to tailor vaccines to individual animal species, breeds, and disease susceptibilities.
- Increasing investments in veterinary healthcare infrastructure, cold chain logistics, and distribution networks will facilitate the delivery of vaccines to remote and underserved areas, ensuring equitable access to veterinary healthcare services.
- The growing recognition of the role of vaccines in preventive healthcare and disease management will drive increased demand for biologics, creating opportunities for market expansion and diversification in the Middle East and Africa region.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the expected growth trajectory of the Middle East and Africa Veterinary Vaccines Market?
What are the primary drivers fueling the growth of the veterinary vaccines market in the region?
How are technological advancements impacting vaccine development in the Middle East and Africa?
What are the significant challenges faced by the Middle East and Africa Veterinary Vaccines Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Middle East and Africa Veterinary Vaccines Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Middle East and Africa Veterinary Vaccines Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 469.74 million → 2032: USD 717.77 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Middle East and Africa Veterinary Vaccines Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Middle East and Africa Veterinary Vaccines Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Middle East and Africa Veterinary Vaccines Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Middle East and Africa Veterinary Vaccines Market Drivers
- 3.3 Middle East and Africa Veterinary Vaccines Market Restraints & Challenges
- 3.4 Middle East and Africa Veterinary Vaccines Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Middle East and Africa Veterinary Vaccines Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Middle East and Africa Veterinary Vaccines Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Middle East and Africa Veterinary Vaccines category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Middle East and Africa Veterinary Vaccines Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Middle East and Africa Veterinary Vaccines Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Middle East and Africa Veterinary Vaccines market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Middle East and Africa Veterinary Vaccines Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Middle East and Africa Veterinary Vaccines Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Middle East and Africa Veterinary Vaccines Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Middle East and Africa Veterinary Vaccines (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Middle East and Africa Veterinary Vaccines Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Middle East and Africa Veterinary Vaccines Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Middle East and Africa Veterinary Vaccines Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Middle East and Africa Veterinary Vaccines Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Middle East and Africa Veterinary Vaccines Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Middle East and Africa Veterinary Vaccines Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Middle East and Africa Veterinary Vaccines Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Middle East and Africa Veterinary Vaccines Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Middle East and Africa Veterinary Vaccines Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
