
Market Overview:
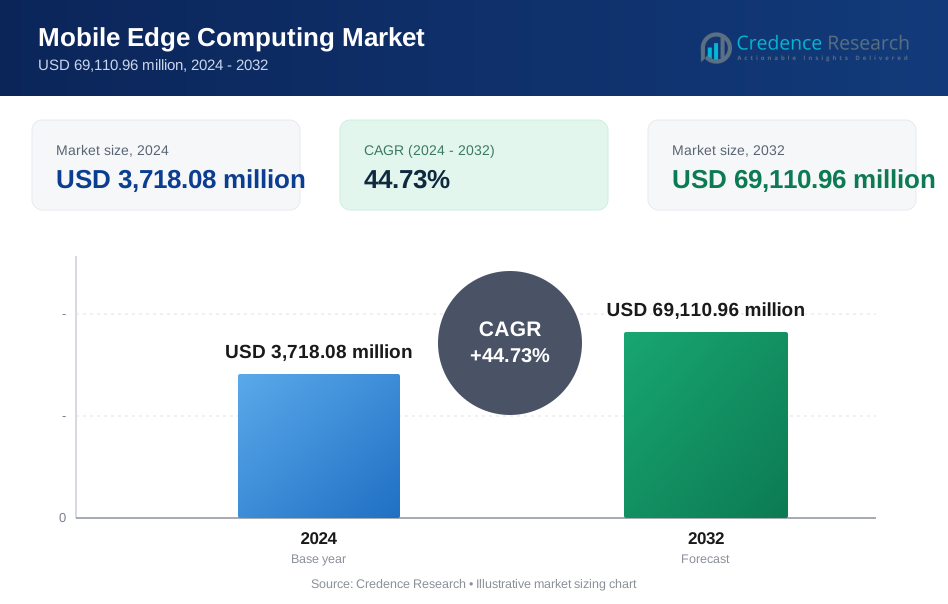
The Mobile Edge Computing market size was valued at USD 850.00 million in 2018 and increased to USD 3,718.08 million in 2024. It is anticipated to reach USD 69,110.96 million by 2032, growing at a CAGR of 44.73% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Mobile Edge Computing (MEC) Market Size 2024 | USD 3,718.08 million |
| Mobile Edge Computing (MEC) Market, CAGR | 44.73% |
| Mobile Edge Computing (MEC) Market Size 2032 | USD 69,110.96million |
The Mobile Edge Computing market is led by prominent players including Nokia Corporation, Huawei Technologies, Intel Corporation, Dell Technologies, Hewlett Packard Enterprise (HPE), Cisco Systems, and IBM Corporation. These companies offer end-to-end MEC solutions, combining advanced hardware with software-defined platforms optimized for 5G, AI, and IoT use cases. Nokia and Huawei lead in telecom-integrated edge deployments, while Intel and Dell focus on high-performance edge servers and chipsets. Cisco and HPE emphasize edge-to-cloud orchestration, targeting enterprise networks. North America dominates the market with a 35.3% share in 2024, supported by early 5G rollouts and mature digital infrastructure. Asia Pacific follows closely with a 32.0% share, driven by large-scale industrial adoption and government-backed smart infrastructure initiatives. Europe holds a 21.2% share, supported by strong regulatory frameworks and private 5G investments.

Market Insights
- The Mobile Edge Computing market was valued at USD 850.00 million in 2018 and reached USD 3,718.08 million in 2024, expected to grow to USD 69,110.96 million by 2032 at a CAGR of 44.73%.
- Rapid 5G deployment and the rising use of IoT devices are driving real-time processing needs, fueling market expansion across enterprise, industrial, and telecom applications.
- The market trends show increasing edge AI integration, private 5G networks, and content delivery innovations, with companies like Nokia, Huawei, and Dell leading through scalable MEC platforms.
- High deployment costs and integration complexities restrain growth, especially for SMEs and emerging economies with limited digital infrastructure and skilled resources.
- North America holds the largest market share at 35.3%, followed by Asia Pacific at 32.0% and Europe at 21.2%, while hardware remains the dominant component segment driven by edge server demand.
Market Segmentation Analysis:
By Component:
The hardware segment dominates the Mobile Edge Computing market, accounting for the largest revenue share in 2024. Within hardware, servers lead due to their central role in processing and storing data at the edge. Rising deployment of 5G networks and the need for low-latency computing drive demand for robust, edge-specific servers. Routers and gateways follow as key enablers of secure and seamless connectivity. In contrast, the software segment, led by MEC platforms, is gaining traction for managing distributed infrastructure and orchestrating edge applications, especially in telecom and enterprise networks integrating AI and IoT workloads.
- For instance, Dell Technologies ships edge-optimized PowerEdge servers deployed in over 50,000 edge locations globally, supporting telecom and enterprise MEC workloads.
By Application:
Location-based services represent the leading application segment in the Mobile Edge Computing market, holding the highest revenue share in 2024. Real-time navigation, proximity marketing, and fleet tracking drive adoption across logistics, retail, and transportation sectors. Video surveillance follows closely, driven by rising smart city deployments and public safety investments. Optimized local content distribution supports streaming services and AR/VR platforms with lower latency. Unified communication and data analytics gain momentum in enterprise use cases. Environmental monitoring is emerging in industrial zones, driven by regulatory compliance and the need for real-time air and noise quality tracking.
- For instance, Huawei supports smart city video platforms capable of handling over 500,000 concurrent camera streams using edge computing for real-time analysis.
By Organization Size:
Large enterprises dominate the Mobile Edge Computing market, capturing the highest revenue share in 2024. These organizations invest heavily in distributed infrastructure to support real-time decision-making, operational automation, and advanced analytics. Industries such as telecom, automotive, and manufacturing lead adoption due to scale and performance requirements. Small and medium-sized enterprises (SMEs) show increasing uptake, supported by scalable MEC platforms and cloud-integrated edge services. Lower deployment costs, modular solutions, and 5G rollout are helping SMEs access edge computing benefits, particularly for localized data processing, retail analytics, and remote asset monitoring.
Key Growth Drivers
Rising 5G Deployment and Network Densification
The expansion of 5G networks is a major growth driver for the Mobile Edge Computing (MEC) market. 5G’s ultra-low latency and high bandwidth capabilities make edge computing essential for delivering real-time services. Telecom providers are deploying MEC nodes close to users to offload traffic and reduce network congestion. This supports emerging use cases such as autonomous vehicles, AR/VR, and smart manufacturing. As 5G densification continues with small cell rollouts, it creates a scalable infrastructure for edge platforms. Operators are increasingly bundling MEC with 5G private networks to offer enterprises localized processing capabilities, reducing reliance on centralized cloud systems. With global 5G subscriptions expected to grow rapidly, MEC becomes integral to delivering on its performance promises.
- For instance, Verizon deployed more than 20 MEC sites in the United States using AWS Wavelength, enabling application latencies below 10 milliseconds for enterprise and consumer use cases.
Proliferation of IoT Devices and Real-Time Data Processing
The growing number of IoT devices across industries is fueling demand for Mobile Edge Computing. Smart factories, connected vehicles, and wearable devices generate vast amounts of data requiring near-instant processing. MEC helps manage this data closer to the source, cutting latency and improving response times. In industrial settings, MEC supports real-time analytics for predictive maintenance, process automation, and quality control. In healthcare, edge-enabled wearables and remote diagnostics need immediate processing for critical insights. As IoT expands across sectors, MEC provides the computational infrastructure to manage distributed, latency-sensitive workloads efficiently. The rising complexity and volume of connected devices make edge computing a strategic necessity for future-ready IoT ecosystems.
- For instance, Bosch uses edge computing in smart IoT solutions where sensors and gateways process data locally, improving decision making and reducing cloud traffic for real-time analytics.
Demand for Low Latency and High Bandwidth Applications
Applications that demand low latency and high bandwidth are key drivers for Mobile Edge Computing adoption. Video analytics, immersive gaming, AR/VR, and autonomous systems all require minimal delay in data transmission. Traditional cloud models fall short due to distance-based latency. MEC solves this by hosting compute resources at the network edge, closer to the user. Content providers and CDNs integrate edge nodes to deliver streaming media faster and more reliably. Enterprises rely on MEC to ensure seamless communication between automated systems in smart facilities. The need to meet user expectations for instant data access and responsiveness across consumer and industrial applications is accelerating the integration of edge infrastructure.

Key Trends & Opportunities
Integration of AI and Machine Learning at the Edge
One of the major trends in the MEC market is the integration of AI and machine learning directly at the edge. Businesses increasingly deploy AI models on MEC platforms to analyze real-time data streams without needing to send data to centralized cloud systems. This trend enables faster decision-making and reduces data transfer costs. Use cases span predictive maintenance in factories, anomaly detection in surveillance, and personalization in retail environments. The development of lightweight AI frameworks optimized for edge devices is expanding deployment possibilities. Vendors are launching AI-optimized edge servers and chipsets, opening opportunities for solution providers to offer industry-specific, edge-intelligent systems. As AI use cases diversify, combining MEC with edge AI creates a scalable and agile digital architecture for next-gen applications.
- For instance, NVIDIA has built a massive edge AI ecosystem with over 1 million developers and more than 6,000 companies worldwide utilizing the Jetson platform. This deployment supports real-time vision, robotics, and industrial analytics directly at the edge, utilizing advanced hardware like the Jetson AGX Thor for high-performance autonomous machines.
Growth of Private 5G and Edge Cloud Ecosystems
The convergence of private 5G networks with MEC creates strong market opportunities. Enterprises are investing in private wireless infrastructure for secure, low-latency connectivity, particularly in manufacturing, logistics, and healthcare. MEC complements this by enabling localized compute environments tailored to enterprise needs. Cloud providers and telecom operators are collaborating to offer hybrid edge-cloud solutions that allow seamless workload orchestration across data centers and edge locations. These partnerships open opportunities for managed services, application hosting, and vertical-specific platforms. The rise of edge cloud ecosystems also supports compliance, data residency, and energy efficiency. As more enterprises seek agile infrastructure models, private 5G paired with MEC becomes a key enabler of digital transformation.
Key Challenges
Infrastructure Deployment and Integration Complexity
Deploying Mobile Edge Computing infrastructure poses a significant challenge due to integration complexities. MEC requires distributed nodes, reliable backhaul, edge-optimized software stacks, and seamless orchestration across cloud and edge layers. These deployments demand high capital investment and technical expertise. Integration with legacy systems and existing network infrastructure adds another layer of complexity. Operators face hurdles in scaling MEC sites across geographically dispersed locations while ensuring consistent performance. Compatibility between hardware vendors, network standards, and orchestration tools remains inconsistent, slowing adoption. Without streamlined deployment models, enterprises may hesitate to transition from centralized cloud models to decentralized edge ecosystems, limiting MEC’s growth potential.
Data Security and Regulatory Compliance
Ensuring data security and meeting regulatory compliance at the edge is a growing challenge. MEC environments, being distributed and close to end-users, increase the attack surface for cyber threats. Protecting sensitive data during transmission and processing requires strong encryption, access controls, and endpoint security, which can be difficult to enforce uniformly across decentralized locations. Furthermore, different regions have varying regulations on data privacy, storage, and sovereignty. Companies deploying MEC across borders must navigate complex compliance landscapes. Any lapse in edge data governance can result in penalties, reputational loss, and operational disruptions. Addressing security and compliance at scale is essential for building enterprise confidence in MEC platforms.
Regional Analysis
North America
North America held the largest share of the Mobile Edge Computing market in 2024, reaching USD 1,314.69 million, up from USD 304.30 million in 2018. With a projected CAGR of 44.7%, the region is expected to reach USD 24,403.20 million by 2032, accounting for approximately 35.3% of the global market. Strong 5G rollout, advanced cloud ecosystems, and high enterprise tech adoption drive this growth. The U.S. leads in edge deployments for autonomous systems, AI analytics, and smart cities. Key players and early commercial adoption position North America as a mature and innovation-driven MEC market.
Europe
Europe accounted for USD 839.44 million in 2024, rising from USD 200.60 million in 2018, and is forecasted to reach USD 14,634.43 million by 2032, registering a CAGR of 43.6%. The region holds a 21.2% market share in 2024. Germany, the UK, and France are key contributors, with edge applications supporting automotive, healthcare, and manufacturing sectors. EU data regulations and sustainability goals also promote decentralized computing and localized data processing. Government support for 5G corridors and cross-border digital infrastructure accelerates MEC growth across the region.
Asia Pacific
Asia Pacific recorded USD 1,192.93 million in 2024, growing from USD 263.50 million in 2018, and is set to reach USD 24,002.29 million by 2032, growing at the highest regional CAGR of 46.2%. Holding a 32% market share in 2024, the region sees rapid adoption due to large-scale 5G rollouts, smart city initiatives, and industrial IoT expansion. China, Japan, South Korea, and India lead in telecom innovation and mobile user base. Investments in hyperscale data centers and government-backed digital infrastructure projects are accelerating edge computing penetration across diverse verticals.
Latin America
Latin America’s Mobile Edge Computing market was valued at USD 191.07 million in 2024, up from USD 44.20 million in 2018, and is projected to reach USD 3,239.23 million by 2032 at a CAGR of 43.1%. The region held a 2.6% global market share in 2024. Brazil and Mexico are early adopters, with telecom providers introducing edge-enabled services. Rising demand for content delivery, smart mobility, and public safety solutions is driving localized edge deployments. Growing cloud and telecom partnerships are also helping overcome infrastructure barriers in urban centers.
Middle East
The Middle East registered USD 98.50 million in 2024, increasing from USD 24.57 million in 2018, and is expected to reach USD 1,589.93 million by 2032, growing at a CAGR of 42.2%. The region accounted for 1.3% of the global market share in 2024. Countries like the UAE and Saudi Arabia are investing in smart city frameworks, 5G trials, and AI-driven surveillance, driving MEC uptake. Government-backed digital economy strategies, especially in GCC nations, support deployment of edge infrastructure to enhance public services and real-time analytics.
Africa
Africa’s Mobile Edge Computing market reached USD 81.44 million in 2024, up from USD 12.84 million in 2018, and is projected to grow to USD 1,241.87 million by 2032, at a CAGR of 40.4%. With a 1.2% market share in 2024, growth is modest but steady, supported by mobile network expansion and rising digital services demand. South Africa, Nigeria, and Kenya lead regional edge adoption. MEC is gaining traction in fintech, e-learning, and e-health applications. As connectivity improves and cloud adoption grows, edge computing is set to address local latency and bandwidth challenges.
Market Segmentations:
By Component:
- Hardware
- Servers
- Routers
- Switches
- Controllers
- Gateways
- Software
- MEC Platform
- Application Software
By Application:
- Location-based Services
- Video Surveillance
- Unified Communication
- Optimized Local Content Distribution
- Data Analytics
- Environmental Monitoring
By Organization Size:
- Large Enterprises
- Small and Medium-sized Enterprises (SMEs)
By Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa

Competitive Landscape
The competitive landscape of the Mobile Edge Computing (MEC) market is marked by intense innovation and strategic collaboration among global technology leaders. Companies such as Nokia, Huawei, Intel, Dell Technologies, HPE, and Cisco Systems dominate the ecosystem by offering integrated edge infrastructure, virtualization platforms, and 5G-ready solutions. These players invest heavily in R&D to enhance edge computing performance, scalability, and AI integration. Strategic alliances between telecom operators and cloud service providers are also reshaping market dynamics. For instance, partnerships between Microsoft Azure and operators like AT&T, or AWS Wavelength with Verizon, are accelerating MEC adoption across industries. Vendors are targeting key verticals such as manufacturing, retail, and automotive with customized edge solutions. Startups like Zenlayer and Vapor IO are gaining traction by focusing on low-latency content delivery and edge interconnection. Overall, the market remains highly dynamic, with continuous developments in software-defined infrastructure, hardware optimization, and edge-cloud convergence driving competition and growth.
Key Player Analysis
- Nokia Corporation
- Huawei Technologies Co., Ltd.
- Intel Corporation
- Dell Technologies Inc.
- Hewlett Packard Enterprise Development LP (HPE)
- Cisco Systems, Inc.
- IBM Corporation
- Juniper Networks, Inc.
- Commscope
- Advantech Co., Ltd.
- Zenlayer Inc.
- ADLINK Technology Inc.
- Fujitsu Limited
- Vapor IO, Inc.
- ESW Capital
Recent Developments
- In March 2025, AWS introduced an Outposts server based on Graviton3 Arm chips, claiming 50–70% lower power draw for cloud RAN and MEC functions.
- In 2025, Advantech unveiled its “Edge Computing & WISE-Edge in Action” strategy, co-developing high-performance platforms with Intel and NVIDIA to accelerate digital transformation in smart manufacturing and healthcare.
- In 2025, NXP Semiconductors acquired Kinara for USD 307 million to strengthen edge-AI portfolios in industrial and automotive domains.
Report Coverage
The research report offers an in-depth analysis based on Component, Application, Organization Size and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Mobile Edge Computing adoption will accelerate with wider 5G network rollouts across urban and rural areas.
- AI and machine learning at the edge will drive real-time decision-making across industrial and commercial sectors.
- Enterprises will increasingly deploy private 5G networks combined with edge platforms for secure, low-latency operations.
- Growth in smart cities will boost demand for edge-enabled surveillance, traffic control, and public safety systems.
- Edge computing will become critical for autonomous mobility, supporting real-time vehicle-to-infrastructure communication.
- Telecom operators and cloud providers will deepen partnerships to offer integrated edge-cloud solutions.
- Rising use of IoT devices will require scalable edge infrastructure to process vast volumes of sensor data.
- Modular and container-based edge deployments will simplify integration and reduce operational complexity.
- Edge-based content delivery will expand across gaming, AR/VR, and immersive media applications.
- Regulatory focus on data privacy and localization will promote regional edge computing infrastructure investments.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Mobile Edge Computing market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Mobile Edge Computing market projected to grow between 2024 and 2032?
Which Mobile Edge Computing market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Mobile Edge Computing market?
Who are the leading companies in the Mobile Edge Computing market?
Which region commanded the largest share of the Mobile Edge Computing market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Mobile Edge Computing Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Mobile Edge Computing Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 3,718.08 million → 2032: USD 69,110.96 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Mobile Edge Computing Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Mobile Edge Computing Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Mobile Edge Computing Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Mobile Edge Computing Market Drivers
- 3.3 Mobile Edge Computing Market Restraints & Challenges
- 3.4 Mobile Edge Computing Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Mobile Edge Computing Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Mobile Edge Computing Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Mobile Edge Computing category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Mobile Edge Computing Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Mobile Edge Computing Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Mobile Edge Computing market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Mobile Edge Computing Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Mobile Edge Computing Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Mobile Edge Computing Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Mobile Edge Computing (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Mobile Edge Computing Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Mobile Edge Computing Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Mobile Edge Computing Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Mobile Edge Computing Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Mobile Edge Computing Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Mobile Edge Computing Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Mobile Edge Computing Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Mobile Edge Computing Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Mobile Edge Computing Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
