
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
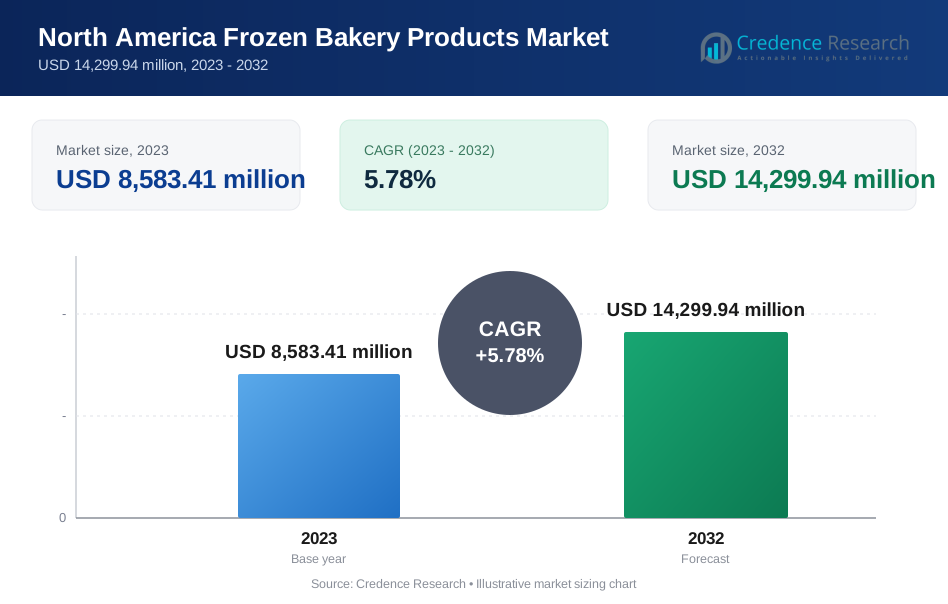
| North America Frozen Bakery Products Market Size 2023 | USD 8,583.41 Million |
| North America Frozen Bakery Products Market, CAGR | 5.78% |
| North America Frozen Bakery Products Market Size 2032 | USD 14,299.94 Million |
Market Overview
The North America Frozen Bakery Products Market is projected to grow from USD 8,583.41 million in 2023 to an estimated USD 14,299.94 million by 2032, with a compound annual growth rate (CAGR) of 5.78% from 2024 to 2032. This growth is driven by the increasing demand for convenience foods, the rising popularity of ready-to-eat products, and the expanding retail sector.
Key market drivers include the growing consumer inclination toward healthier and organic frozen bakery products and the increasing number of quick-service restaurants and cafés offering frozen bakery items. Trends such as the introduction of gluten-free and vegan options are also contributing to market growth, catering to the diverse dietary preferences of consumers.
Geographically, the United States dominates the North American market, followed by Canada and Mexico. The U.S. leads due to its large consumer base and well-established food retail sector. Key players in the market include Aryzta AG, General Mills Inc., Grupo Bimbo, S.A.B. de C.V., and Lantmännen Unibake, who are continuously innovating to maintain their competitive edge in this growing market.
Market Drivers
Rising Demand for Convenience Foods
The modern lifestyle in North America is characterized by busy schedules and a growing preference for convenience in daily activities, including food consumption. Frozen bakery products fit well into this trend, offering a quick and easy solution for consumers who seek ready-to-eat or ready-to-bake items without compromising on taste and quality. For instance, a survey conducted by the American Frozen Food Institute found that frozen food consumption increased significantly during the COVID-19 pandemic, with many consumers reporting they plan to continue purchasing frozen foods at higher levels. The ease of storage, longer shelf life, and availability of a variety of frozen bakery items cater to the diverse needs of consumers. Retailers are also expanding their frozen food sections, recognizing the growing consumer inclination toward such products. According to data from the National Frozen & Refrigerated Foods Association, frozen bakery sales in the U.S. have shown consistent growth over the past few years. This trend is expected to continue, further fueling market expansion as consumers increasingly prioritize convenience in their food choices.
Increasing Health Consciousness and Demand for Healthier Options
While convenience remains a key factor, North American consumers are also becoming increasingly health-conscious. There is a growing demand for frozen bakery products that cater to specific dietary needs, such as gluten-free, whole grain, organic, and low-calorie options. For instance, a survey by the International Food Information Council found that a significant percentage of consumers are actively seeking healthier food options, including in the frozen food aisle. Manufacturers are responding to this demand by introducing products that align with health trends in the market. The U.S. Department of Agriculture reports an increase in the availability and consumption of whole grain products, including in the frozen bakery sector. Additionally, the growing popularity of plant-based diets has led to the introduction of vegan frozen bakery products. A study by the Plant Based Foods Association showed substantial growth in plant-based food sales, including frozen baked goods. This shift in consumer preference is driving innovation within the industry, with companies investing in research and development to offer healthier options without compromising on taste or texture.
Expansion of the Retail Sector and E-commerce
The retail landscape in North America has been evolving rapidly, with the expansion of supermarket chains, hypermarkets, and convenience stores playing a significant role in the distribution of frozen bakery products. For instance, data from the Food Marketing Institute shows an increase in the number of supermarkets offering expanded frozen food sections. Additionally, the rise of e-commerce has revolutionized the way consumers purchase frozen bakery products. A survey by the National Retail Federation found that online grocery shopping, including frozen foods, has seen substantial growth in recent years. This shift towards online retail has prompted manufacturers and retailers to optimize their supply chains for frozen products. The U.S. Census Bureau reports steady growth in e-commerce sales for food and beverage categories, which includes frozen bakery items. Furthermore, a study by Brick Meets Click revealed that online grocery sales have maintained higher levels even after pandemic-related restrictions eased, indicating a lasting change in consumer behavior. The growth of the retail sector, both in physical stores and online platforms, continues to be a major driver of the frozen bakery products market in North America.
Technological Advancements in Freezing Techniques
Technological innovation in freezing techniques has played a crucial role in the growth of the North America Frozen Bakery Products Market. Advanced freezing technologies such as blast freezing, cryogenic freezing, and individual quick freezing (IQF) have enhanced the quality, texture, and shelf life of frozen bakery products. These technologies help in preserving the nutritional content and flavor of bakery products, making them more appealing to health-conscious consumers. Additionally, improvements in packaging materials and methods, such as vacuum packaging and modified atmosphere packaging (MAP), have further extended the shelf life of frozen bakery items while maintaining their freshness. The ability to produce frozen bakery products that can be stored for longer periods without compromising quality has encouraged consumers to opt for these items. This technological progress has also enabled manufacturers to expand their product offerings, introducing new and innovative frozen bakery products that cater to the evolving tastes and preferences of consumers in North America. As technology continues to advance, it is expected to drive further growth in the frozen bakery products market, making high-quality products more widely available.
Market Trends
Increasing Adoption of Clean Label and Natural Ingredients
The North America Frozen Bakery Products Market is experiencing a significant shift towards clean label and natural ingredients. Consumers are increasingly seeking products with simple, recognizable ingredients and minimal processing. For instance, a survey by the International Food Information Council found that over 60% of consumers say they try to choose foods made with clean ingredients. This trend is driving manufacturers to reformulate their frozen bakery offerings, removing artificial additives and preservatives in favor of natural alternatives. Major players like General Mills have reported strong sales growth in their clean label frozen bakery lines. The demand for transparency has also led to the rise of "free-from" claims on packaging, with gluten-free and non-GMO being particularly popular. Government data shows that sales of products with clean label claims have consistently outpaced conventional alternatives in recent years. As a result, even traditional bakery brands are launching clean label versions of their popular products to meet consumer expectations. This trend is expected to continue shaping the frozen bakery landscape, with companies investing in research and development to create innovative clean label solutions that maintain taste and texture while appealing to health-conscious consumers.
Growth of Plant-Based and Vegan Frozen Bakery Products
The North America Frozen Bakery Products Market is witnessing substantial growth in plant-based and vegan offerings. This trend is driven by increasing consumer interest in plant-based diets for health, environmental, and ethical reasons. A recent survey by the Plant Based Foods Association found that plant-based food sales are growing at double-digit rates, with frozen plant-based baked goods being a particularly fast-growing segment. Major retailers have reported significant expansion of their plant-based frozen bakery sections to meet this demand. For instance, Whole Foods Market has doubled its plant-based frozen bakery SKUs in the past two years. Manufacturers are innovating with alternative ingredients like almond milk, coconut oil, and aquafaba to create vegan versions of traditional bakery items. The trend extends beyond just dairy and egg alternatives, with companies also focusing on developing plant-based protein-enriched bakery products. Government data indicates that the number of new product launches in the vegan frozen bakery category has increased by over 50% in the past three years. This growth is expected to continue as more consumers, including flexitarians, incorporate plant-based options into their diets, driving further innovation and market expansion in the vegan frozen bakery sector.
Market Restraints and Challenges
High Competition and Price Sensitivity
The North America Frozen Bakery Products Market faces intense competition and price sensitivity, creating significant challenges for manufacturers. The market is saturated with a wide array of frozen bakery products from both established brands and private label manufacturers, leading to fierce price wars and margin pressures. This competitive landscape makes it difficult for companies to maintain profitability while offering competitive prices, especially as consumers become increasingly cost-conscious. For instance, a survey conducted by the American Bakers Association found that price is a top consideration for 78% of consumers when purchasing bakery products. The pressure to keep prices low can sometimes compromise product quality or limit innovation, as companies focus on reducing costs to remain competitive. Additionally, the availability of fresh bakery products poses a challenge, as some consumers prefer these over frozen options when price differences are minimal. For example, a study by the International Dairy Deli Bakery Association revealed that 65% of consumers prefer fresh bakery items when given the choice between fresh and frozen at similar price points.
Supply Chain and Distribution Challenges
The North America Frozen Bakery Products Market faces significant supply chain and distribution challenges, particularly in maintaining the cold chain from production to the point of sale. Frozen bakery products require stringent temperature control to preserve their quality and safety, adding complexity and cost to the supply chain. For instance, a report by the Food Marketing Institute highlighted that maintaining proper temperature control during transportation and storage is a top concern for 82% of frozen food distributors. Any disruption in the cold chain can result in product spoilage, leading to financial losses and damage to brand reputation. The logistics of distributing frozen products over long distances can be particularly challenging, especially in remote or underserved regions. For example, a study by the National Frozen & Refrigerated Foods Association found that 35% of frozen food distributors reported difficulties in serving rural areas due to infrastructure limitations. The high costs associated with cold storage, transportation, and energy consumption for maintaining low temperatures also pose significant challenges. These supply chain and distribution challenges require continuous investment in technology and infrastructure, as well as close collaboration with logistics providers, to ensure product integrity.
Market Segmentation Analysis
By Product Type
According to industry reports, bread remains the largest segment in the North America Frozen Bakery Products Market. For instance, a survey by the American Bakers Association found that over 90% of U.S. households regularly purchase bread products. The U.S. Department of Agriculture reports that whole grain bread consumption has increased significantly in recent years. Cakes and pastries are also experiencing robust growth, with Nielsen data showing double-digit sales increases for frozen desserts. Morning goods like muffins and croissants are gaining popularity as convenient breakfast choices. The Frozen Food Institute notes that pizza crusts are a fast-growing segment, reflecting the widespread popularity of at-home pizza nights.
By Distribution Channel
Industry data indicates that hypermarkets and supermarkets dominate frozen bakery product distribution. For instance, a Food Marketing Institute study found that over 80% of U.S. consumers purchase frozen foods from these outlets. Specialty stores cater to a niche market, with the National Restaurant Association reporting increased demand for artisanal and gourmet frozen bakery items. Online retailing is rapidly expanding, with eMarketer data showing significant year-over-year growth in online grocery sales. The Convenience Store News Annual Industry Report highlights the importance of convenience stores in reaching consumers seeking quick access to frozen bakery products. Foodservice channels also play a vital role, with the International Foodservice Manufacturers Association noting increased usage of frozen bakery items in restaurants and catering.
Segments
Based on Product Type
- Bread
- Cakes and Pastries
- Morning Goods
- Pizza Crust
- Other Product Types
Based on Distribution Channel
- Hypermarkets/Supermarkets
- Specialty Stores
- Online Retailing
- Other Distribution Channels
Based on Region
- United States
- Canada
- Mexico
Regional Analysis
United States (70%):
The United States holds the largest market share in the North America Frozen Bakery Products Market, accounting for approximately 70% of the regional market. For instance, a survey by the American Bakers Association found that 78% of Americans consume bakery products at least once a week. The market is characterized by innovation in healthier options, with data from Nielsen showing strong growth in gluten-free and whole grain frozen bakery sales. Major players like General Mills and Grupo Bimbo continue to expand their product lines to meet evolving consumer preferences. The U.S. Department of Agriculture reports that frozen food sales, including bakery items, have seen consistent growth over the past decade, reflecting the market's strength and consumer acceptance.
Canada (20%):
Canada accounts for approximately 20% of the North America Frozen Bakery Products Market, making it the second-largest market in the region. Statistics Canada reports that frozen food sales, including bakery items, have risen annually over the past five years. A survey by the Bakery Association of Canada found that 65% of Canadians purchase frozen baked goods at least monthly. The market is seeing a trend towards healthier options, with organic and natural ingredient claims gaining traction. For instance, the Canada Organic Trade Association notes that sales of organic frozen foods, including bakery products, have grown at double-digit rates. Canadian consumers also show strong interest in artisanal and specialty frozen bakery items, driving innovation among both local and international manufacturers in the market.
Key players
- Aryzta AG
- co.in
- Conagra Brands, Inc.
- ADM
- Daiya Foods Inc.
- Grupo Bimbo S.A.B. de C.V.
- General Mills Inc.
- Cole’s Quality Food Inc.
- Barilla Holding S.p.A.
- Britannia Industries Limited
- Canada Bread Company Ltd.
- Dawn Food Products Inc.
- Dunkin' Donuts LLC
- Marzetti Company
- United Biscuits
Competitive Analysis
The North America Frozen Bakery Products Market is highly competitive, with a mix of global giants and regional players vying for market share. Key players like Aryzta AG, Conagra Brands, Inc., and General Mills Inc. dominate the market with their extensive product portfolios and strong distribution networks. These companies leverage their brand recognition and continuous innovation to maintain a competitive edge. Grupo Bimbo S.A.B. de C.V. and ADM also play significant roles, particularly in expanding their reach across North America through strategic acquisitions and partnerships. Companies like Daiya Foods Inc. and Barilla Holding S.p.A. cater to niche segments, such as plant-based and specialty products, attracting health-conscious consumers. The presence of established brands like Dunkin' Donuts LLC and United Biscuits further intensifies competition, as they focus on brand loyalty and expanding their frozen product lines. This competitive landscape drives continuous innovation and diversification within the market.
Recent Developments
- In April 2024, Aryzta AG appointed Michael Schai as new CEO effective January 1, 2025.
- In June 2024, Conagra Brands, Inc. unveiled over 50 new food products across various categories, though none were specifically related to tablet counting machines.
- In December 2023, ADM announced an agreement to acquire UK-based FDL, a developer and producer of flavor and functional ingredient systems, to broaden its global flavors capabilities.
- In March 2024, Daiya Foods Inc. introduced new dairy-free cheese shreds for foodservice operators.
- In July 2024, Grupo Bimbo S.A.B. de C.V. reported that 93% of its packaging is made of recyclable materials.
- In March 2024, Britannia launched an AI-powered camera campaign for NutriChoice with Ranveer Singh.
Market Concentration and Characteristics
The North America Frozen Bakery Products Market is characterized by a moderate to high level of market concentration, with a few dominant players such as Aryzta AG, General Mills Inc., and Grupo Bimbo S.A.B. de C.V. holding significant market shares. These companies benefit from extensive distribution networks, strong brand recognition, and continuous product innovation, allowing them to maintain a competitive edge. The market is also marked by the presence of several regional and niche players who cater to specific consumer demands, such as health-conscious and specialty diets. Despite the concentration, the market remains dynamic, with competition driving innovation, diversification, and the introduction of new products to meet evolving consumer preferences.
Report Coverage
The research report offers an in-depth analysis based on Products Type, Distribution channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for convenience foods is expected to drive steady growth in the frozen bakery products market, as busy lifestyles push consumers toward quick and easy meal solutions.
- The market will see an increase in health-oriented frozen bakery products, including gluten-free, organic, and low-calorie options, catering to the growing health-conscious consumer base.
- The plant-based trend will continue to shape the market, with more companies introducing vegan and dairy-free frozen bakery products to meet the dietary preferences of a broader audience.
- Manufacturers are likely to invest in R&D to develop innovative frozen bakery products that offer better taste, texture, and nutritional value, driving consumer interest and market growth.
- The shift towards online grocery shopping will fuel the expansion of the frozen bakery products market, as more consumers opt for the convenience of home delivery.
- The trend towards clean label products will continue to gain traction, with consumers seeking frozen bakery items made from natural, minimally processed ingredients.
- Ongoing advancements in freezing and packaging technologies will enhance the quality and shelf life of frozen bakery products, supporting market expansion.
- The market will witness growth opportunities in emerging markets within North America, particularly in Mexico, where urbanization and rising disposable incomes are driving demand.
- Companies in the frozen bakery products market will increasingly focus on sustainability, including eco-friendly packaging and reducing food waste, to align with consumer expectations and regulatory demands.
- To strengthen their market position, leading players are expected to pursue strategic partnerships and acquisitions, enabling them to expand their product portfolios and reach new customer segments.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Demand for Convenience Foods
Busy lifestyles in North America are increasing the preference for convenient meal solutions, making frozen bakery products attractive due to their ease of preparation, long shelf life, and consistent quality.
Health and Wellness Trends
Consumers are seeking healthier frozen bakery options, such as gluten-free, whole grain, organic, and low-calorie products, prompting manufacturers to innovate and expand their product lines to meet these evolving dietary preferences.
Expansion of Retail and E-commerce Channels
The growth of large supermarket chains, specialty stores, and the rapid rise of online grocery shopping have made frozen bakery products more accessible, supporting higher sales and broader market reach.
Technological Advancements in Freezing and Packaging
Innovations in freezing techniques and packaging materials have improved the quality, texture, and shelf life of frozen bakery products, making them more appealing to consumers and reducing food waste.
Growth of Plant-Based and Clean Label Products
Rising interest in plant-based diets and clean label foods is driving the introduction of vegan, dairy-free, and minimally processed frozen bakery items, attracting health-conscious and environmentally aware consumers.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the North America Frozen Bakery Products Market?
What are the key drivers of the North America Frozen Bakery Products Market?
Which product types are most popular in the North America Frozen Bakery Products Market?
How are health trends influencing the frozen bakery products market in North America?
Who are the major players in the North America Frozen Bakery Products Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product Type
- 1.2.1 Bread
- 1.2.2 Cakes and Pastries
- 1.2.3 Morning Goods
- 1.2.4 Pizza Crust
- 1.2.5 Other Product Types
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 8,583.41 million → 2032: USD 14,299.94 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 North America Frozen Bakery Products Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 North America Frozen Bakery Products Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 North America Frozen Bakery Products Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 North America Frozen Bakery Products Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 North America Frozen Bakery Products Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 North America Frozen Bakery Products Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 North America Frozen Bakery Products Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 North America Frozen Bakery Products Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 8,583.41 million → 2032: USD 14,299.94 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 North America Frozen Bakery Products Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product Type - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Bread
- 12.3.7.2 Cakes and Pastries
- 12.3.7.3 Morning Goods
- 12.3.7.4 Pizza Crust
- 12.3.7.5 Other Product Types
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 Segment Growth Comparison
- 12.5 Segment Attractiveness and Priority Matrix
Chapter 13 North America Frozen Bakery Products Geographic Market Outlook, 2023-2032
- 13.1 Regional Market Size and Country-Level Shares, 2023
- 13.2 Country Market Size Comparison, 2023
- 13.3 Country Market Forecasts, 2023-2032
- 13.4 Subregional Industrial and Demand Clusters
- 13.5 Intra-Regional Pricing and Cost Differences
- 13.6 Cross-Border Trade and Supply Networks
- 13.7 Regional Supply and Demand Balances
- 13.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 14 North America Frozen Bakery Products Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2023-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 North America Frozen Bakery Products Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2023
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2023-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Aryzta AG
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 General Mills Inc.
- 17.4 Grupo Bimbo S.A.B. de C.V.
- 17.5 Conagra Brands, Inc.
- 17.6 ADM
- 17.7 Daiya Foods Inc.
- 17.8 Barilla Holding S.p.A.
- 17.9 Canada Bread Company Ltd.
- 17.10 Dawn Food Products Inc.
- 17.11 Dunkin' Donuts LLC
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

