
Market Overview
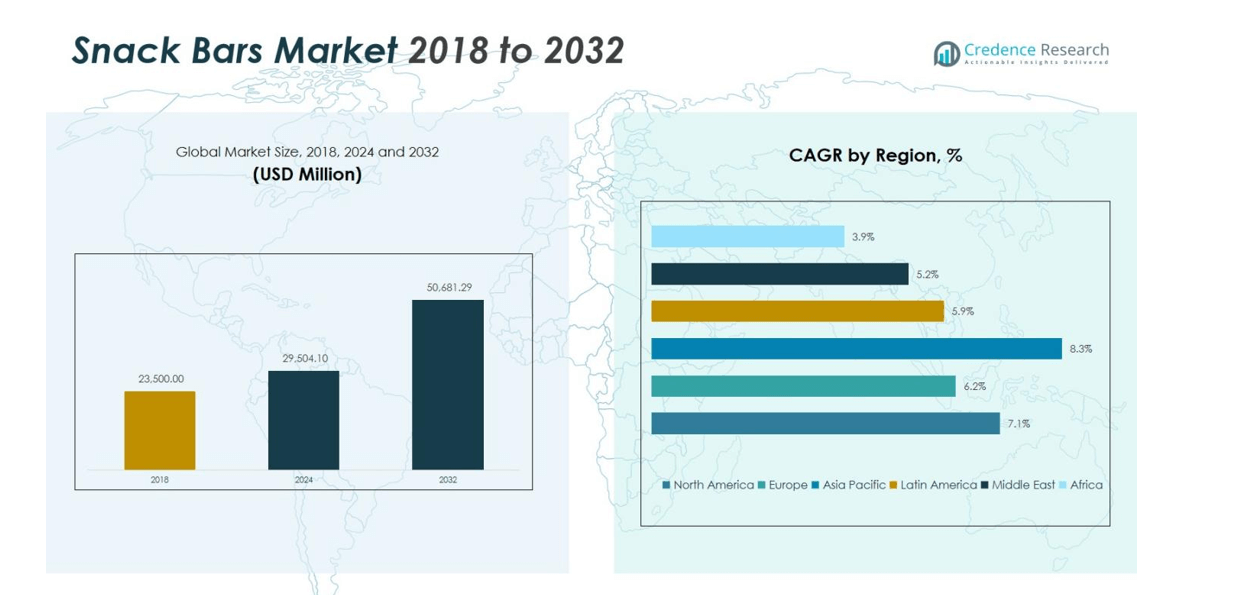
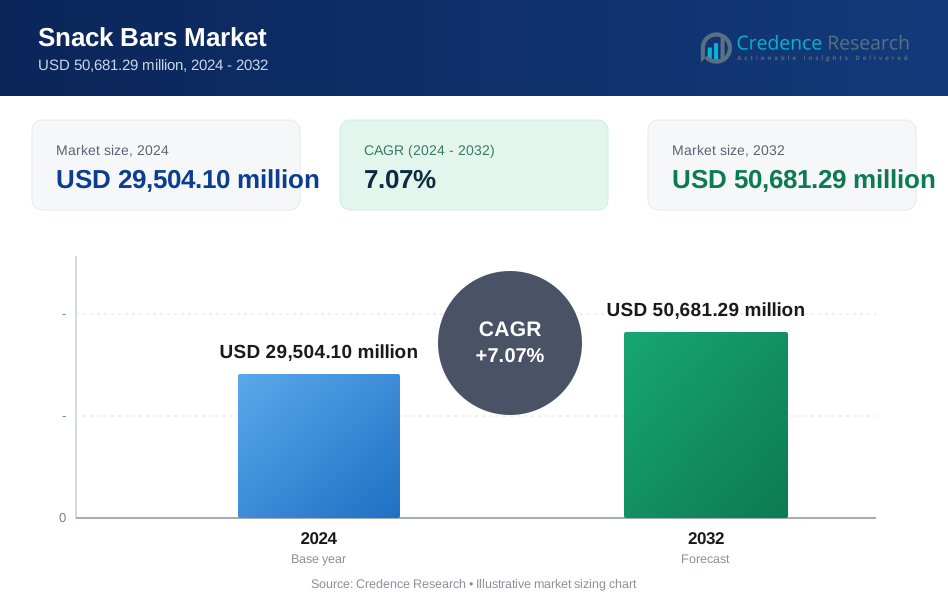
The Global Snack Bars Market size was valued at USD 23,500.00 million in 2018, increased to USD 29,504.10 million in 2024, and is anticipated to reach USD 50,681.29 million by 2032, expanding at a CAGR of 7.07% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Snack Bars Market Size 2024 | USD 29,504.10 million |
| Snack Bars Market, CAGR | 7.07% |
| Snack Bars Market Size 2032 | USD 50,681.29 million |
The Snack Bars Market features strong competition led by General Mills, Kellanova, Weetabix, The Quaker Oats Company, Mondelez International, Mars, Nestlé, The Hain Celestial Group, and Hero Group. These companies prioritize protein-rich, clean-label, and plant-based innovations while expanding omnichannel reach. North America remains the leading region with 41.8% market share in 2024, supported by mature retail networks, frequent product launches, and high adoption of functional snacks. Europe follows with 21.5%, driven by demand for organic and low-sugar bars and strict labeling standards. Asia Pacific holds 22.7% and posts the fastest growth, as urbanization, rising incomes, and e-commerce penetration accelerate category adoption.
Market Insights
- The Global Snack Bars Market was valued at USD 29,504.10 million in 2024 and is projected to reach USD 50,681.29 million by 2032, expanding at a CAGR of 7.07%.
- Rising consumer demand for convenient, nutritious, and portable food options is driving steady market growth worldwide.
- The market trends highlight a strong shift toward plant-based, protein-enriched, and clean-label formulations with sustainable packaging.
- Competition remains moderate, led by key players such as General Mills, Kellanova, Weetabix, Mondelez, Mars, and Nestlé, focusing on product innovation and e-commerce expansion.
- North America holds the largest share at 41.8%, followed by Europe at 21.5% and Asia Pacific at 22.7%; the Energy & Nutrition Bars segment leads globally with 35% market share, while supermarkets and hypermarkets account for over 45% of total distribution.
Market Segmentation Analysis:
By Product
The Energy & Nutrition Bars segment dominates the Global Snack Bars Market, accounting for 35% of total revenue in 2024. Their high protein content, portability, and focus on functional health benefits make them popular among fitness-conscious consumers and busy professionals. The Granola/Muesli Bars segment follows closely with around 28% share, driven by demand for natural ingredients and clean-label formulations. Fruit Bars and Breakfast Bars collectively capture 30% of the market, appealing to consumers seeking convenient meal replacements. The Others category contributes a smaller but growing share, supported by niche formulations and regional flavors.
- For instance, Glanbia Performance Nutrition's think! brand launched downsized protein bar Minis inspired by Girl Scout cookie flavors, enhancing the appeal of better-for-you snacks with nostalgic taste.
By Distribution Channel
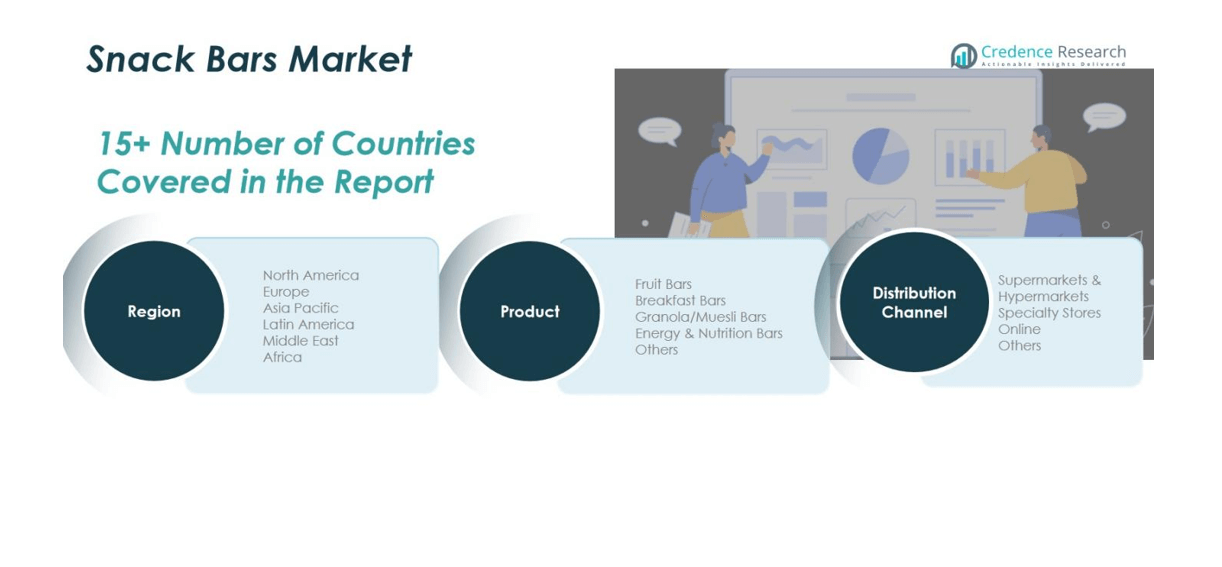
Supermarkets & Hypermarkets lead the Snack Bars Market with a market share exceeding 45% in 2024, benefiting from broad product availability and in-store promotional campaigns. Specialty Stores hold 25% share, driven by premium health-focused and organic offerings that target discerning consumers. The Online channel, contributing nearly 20%, is the fastest-growing segment due to digital retail expansion and subscription-based snack box models. The Others segment, comprising convenience and local stores, captures about 10% of sales, supported by impulse purchases and regional accessibility.
- For instance, major supermarket chains like Walmart and Carrefour consistently expand shelf space and feature diverse snack bar offerings to attract impulse buys.
Key Growth Drivers
Rising Demand for On-the-Go Nutrition
The Snack Bars Market grows rapidly due to the rising preference for quick and nutritious food options. Busy lifestyles and increased urbanization encourage consumers to choose convenient meal substitutes like energy and breakfast bars. These products deliver balanced nutrition and portability, meeting the needs of students, professionals, and travelers. Manufacturers emphasize protein-rich, fiber-loaded, and low-sugar formulations to attract health-conscious buyers. Expanding retail availability across supermarkets and online channels further boosts accessibility, strengthening the overall demand for snack bars worldwide.
- For instance, Junkless entered the protein bar segment with a line featuring dessert-inspired flavors containing 15g of protein, 6-8g of fiber, and minimal sugar, promoting a balance of taste and health without artificial additives.
Growing Health and Wellness Awareness
Consumers are increasingly prioritizing healthier snacking habits, fueling demand for natural and functional snack bars. Products enriched with superfoods, plant-based proteins, and minimal additives align with evolving dietary preferences. This trend is especially strong among millennials and fitness enthusiasts seeking sustained energy and weight management solutions. Brands respond by launching fortified and organic variants that support wellness goals. The emphasis on clean-label and transparent ingredient sourcing continues to enhance consumer trust, driving long-term market growth across developed and emerging regions.
- For instance, Perfect Snacks has launched refrigerated protein bars that offer fresh, organic, and non-GMO options catering to health-conscious consumers focused on clean-label transparency.
Product Innovation and Flavor Diversification
Innovation in product formulation and flavor is a key driver supporting market expansion. Companies introduce new combinations of nuts, seeds, fruits, and grains to enhance taste and nutritional value. These innovations appeal to both indulgent and health-focused consumers. Functional inclusions such as probiotics and adaptogens are also gaining traction. Premium packaging and limited-edition flavors help brands capture attention in competitive retail spaces. The diversification of product portfolios ensures broader consumer appeal, fueling repeat purchases and improving global market penetration.
Key Trends and Opportunities
Rise of Plant-Based and Protein-Enriched Bars
Plant-based snack bars are gaining strong momentum as consumers shift toward sustainable and vegan diets. Manufacturers increasingly use pea protein, almond butter, and oats to replace animal-derived ingredients. Protein-enriched bars appeal to gym-goers and individuals seeking high-energy options for active lifestyles. This trend encourages continuous innovation in texture, flavor, and ingredient sourcing. As veganism becomes mainstream, companies that deliver balanced plant-based nutrition stand to capture growing market share in both mature and emerging economies.
- For instance, Nestlé launched its YES! Plant Protein bars containing 10 grams of plant protein derived from a blend of nuts and peas, catering to consumers looking for natural, additive-free energy options with sustainable packaging.
Expansion Through E-Commerce and Direct-to-Consumer Models
Online retail platforms are transforming how consumers access snack bars globally. Brands leverage e-commerce and direct-to-consumer (D2C) models to offer subscription-based snack boxes, personalized nutrition packs, and seasonal assortments. This approach improves brand visibility, customer engagement, and convenience while reducing dependency on traditional retail distribution. The use of digital marketing, influencer collaborations, and customer feedback analytics allows companies to refine offerings and expand reach. The growing preference for home delivery and health-focused online shopping boosts long-term sales prospects.
- For instance, KIND Snacks successfully expanded its direct-to-consumer channels by launching a subscription service during the pandemic, allowing customers to customize their snack boxes with over 80 varieties of products.
Key Challenges
Intense Market Competition and Price Pressure
The Snack Bars Market faces stiff competition due to numerous global and regional players offering similar products. Price sensitivity among consumers limits premium brand expansion, forcing companies to balance cost efficiency with product innovation. Frequent product launches create market saturation, leading to shorter product life cycles. Retail shelf space competition adds to marketing and distribution costs. This competitive intensity pressures margins, compelling manufacturers to enhance differentiation through branding, sustainability, and ingredient quality.
Supply Chain and Ingredient Cost Volatility
Fluctuating prices of raw materials such as nuts, oats, and dried fruits pose significant challenges for manufacturers. Climate-related disruptions and geopolitical factors affect agricultural yield and supply reliability. These factors increase production costs, impacting profit margins and product pricing. Maintaining consistent ingredient quality becomes difficult, especially for brands focused on organic or clean-label claims. Companies are investing in diversified sourcing networks and long-term supplier partnerships to mitigate volatility and ensure steady production across global markets.
Regional Analysis
North America
North America dominates the Global Snack Bars Market with a market share of around 41.8% in 2024, valued at USD 12,350.24 million, up from USD 9,940.50 million in 2018. The region is projected to reach USD 21,189.94 million by 2032, expanding at a CAGR of 7.1%. Growth is driven by rising health consciousness, busy work lifestyles, and strong consumer preference for protein-enriched and functional snacks. The U.S. remains the largest contributor, supported by wide product availability, innovation in clean-label formulations, and the presence of leading global brands such as General Mills and Kellanova.
Europe
Europe holds a market share of nearly 21.5% in 2024, generating USD 6,307.17 million, up from USD 5,264.00 million in 2018, and is expected to reach USD 10,123.72 million by 2032, growing at a CAGR of 6.2%. The region’s growth is influenced by demand for organic, gluten-free, and low-sugar bars. Countries such as the UK, Germany, and France lead consumption due to high adoption of convenient and natural snacks. Regulatory focus on healthier ingredients and sustainable packaging further drives innovation, promoting expansion across supermarkets, specialty health stores, and online channels.
Asia Pacific
Asia Pacific emerges as the fastest-growing regional market, with a CAGR of 8.3% and market share of 22.7% in 2024. The market increased from USD 5,969.00 million in 2018 to USD 7,814.04 million in 2024, and is projected to reach USD 14,763.50 million by 2032. Rapid urbanization, rising disposable incomes, and increasing adoption of Western eating habits boost demand for convenient nutrition. China, Japan, and India represent major growth engines, supported by expanding e-commerce platforms and youth-focused marketing. The shift toward protein-rich, plant-based, and locally flavored bars strengthens long-term regional market potential.
Latin America
Latin America accounts for a market share of 5% in 2024, with the market growing from USD 1,287.80 million in 2018 to USD 1,598.83 million in 2024, and projected to reach USD 2,517.34 million by 2032, recording a CAGR of 5.9%. Growth is driven by rising middle-class incomes and increasing awareness of health-oriented snacking. Brazil leads the market, followed by Argentina, as consumers shift toward nutritious, portion-controlled food products. Expanding retail infrastructure and the entry of multinational snack manufacturers improve product accessibility and affordability, strengthening regional demand across both premium and mainstream categories.
Middle East
The Middle East Snack Bars Market was valued at USD 781.67 million in 2024, up from USD 679.15 million in 2018, and is expected to reach USD 1,165.95 million by 2032, growing at a CAGR of 5.2%. The region holds a market share of 2.7%, supported by growing consumer interest in healthy eating and lifestyle management. GCC countries drive demand, led by the UAE and Saudi Arabia, where higher disposable incomes and urban retail expansion support market penetration. Increasing product diversification, including sugar-free and protein-rich options, aligns with regional health and wellness priorities.
Africa
Africa represents a market share of 1.3% in 2024, with revenues rising from USD 359.55 million in 2018 to USD 652.16 million in 2024, and forecasted to reach USD 920.84 million by 2032, expanding at a CAGR of 3.9%. Growth is moderate but steady, driven by rising urbanization and gradual dietary diversification. South Africa leads regional consumption, followed by Egypt, supported by growing retail penetration and availability of affordable snack options. Multinational brands are focusing on smaller packaging and locally adapted flavors to attract consumers in developing economies, improving accessibility and long-term adoption of snack bars.
Market Segmentations:
By Product
- Fruit Bars
- Breakfast Bars
- Granola/Muesli Bars
- Energy & Nutrition Bars
- Others
By Distribution Channel:
- Supermarkets & Hypermarkets
- Specialty Stores
- Online
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Snack Bars Market features major players such as General Mills, Kellanova, Weetabix, The Quaker Oats Company, Mondelez International Group, Earnest Eats, Mars, Nestlé, The Hain Celestial Group, and Hero Group. The market remains moderately consolidated, with global brands holding strong distribution networks and brand recognition. These companies compete through innovation in formulations, focusing on protein-rich, gluten-free, and plant-based offerings to meet evolving consumer preferences. Product diversification, clean-label certifications, and premium packaging are key differentiation strategies. Regional players increasingly penetrate niche categories through local sourcing and cost-effective production. Mergers, acquisitions, and collaborations are common to expand geographic reach and product portfolios. Leading companies also invest in e-commerce channels and personalized marketing campaigns to strengthen customer engagement and brand loyalty. Continuous R&D investments and sustainability initiatives further define competitive advantage in this dynamic global market.
Key Player Analysis
- General Mills
- Kellanova
- Weetabix
- The Quaker Oats Company
- Mondelez International Group
- Earnest Eats
- Mars, Incorporated
- Nestlé S.A.
- The Hain Celestial Group, Inc.
- Hero Group
Recent Developments
- In January 2025, Ferrero Group acquired protein-snack brand Power Crunch from Bio-Nutritional Research Group to expand its presence in the U.S. healthy snacking segment.
- In 2025, Mondelez International, Inc. launched a new range of reduced-sugar CLIF protein bars, featuring 5 g of sugar and 16 g of protein, targeting health-conscious consumers seeking balanced nutrition.
- On June 10, 2025, ONE Bars collaborated with The Hershey Company to launch the “ONE × Hershey’s Double Chocolate” protein bar featuring 18 g of protein and just 1 g of sugar.
- On June 3, 2025, RXBAR (under Kellanova) introduced its new High Protein line delivering 18 g of protein with only six recognizable ingredients; the launch also included a new Lemon Honey Cashew Butter flavor
Report Coverage
The research report offers an in-depth analysis based on Product, Distribution Channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Snack Bars Market will continue expanding due to rising demand for convenient nutrition.
- Energy and protein bars will lead growth as fitness and wellness trends strengthen.
- Plant-based and vegan snack bars will gain popularity among health-conscious consumers.
- E-commerce and direct-to-consumer sales channels will play a larger market role.
- Innovation in natural ingredients and sustainable packaging will drive product differentiation.
- Asia Pacific will remain the fastest-growing region supported by urbanization and youth demand.
- Personalized nutrition and functional snack formulations will attract premium consumers.
- Strategic mergers and acquisitions will help global brands strengthen regional presence.
- Clean-label and low-sugar product launches will shape future brand positioning.
- Continuous focus on R&D and digital marketing will support long-term market expansion.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Snack Bar Market?
At what Compound Annual Growth Rate is the Snack Bars Market projected to grow between 2025 and 2032?
What factors are driving the growth of the Snack Bar Market?
What are the key segments within the Snack Bar Market?
What are some challenges faced by the Snack Bar Market?
Who are the major players in the Snack Bar Market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Snack Bars Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Snack Bars Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 29,504.10 million → 2032: USD 50,681.29 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Snack Bars Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Snack Bars Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Snack Bars Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Snack Bars Market Drivers
- 3.3 Snack Bars Market Restraints & Challenges
- 3.4 Snack Bars Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Snack Bars Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Snack Bars Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Snack Bars category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Snack Bars Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Snack Bars Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Snack Bars market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Snack Bars Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Snack Bars Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Snack Bars Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Snack Bars (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Snack Bars Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Snack Bars Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Snack Bars Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Snack Bars Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Snack Bars Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Snack Bars Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Snack Bars Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Snack Bars Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Snack Bars Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
