
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Aerial Imaging Market Size 2024 | USD 2745.8 Million |
| Aerial Imaging Market, CAGR | 14.80% |
| Aerial Imaging Market Size 2032 | USD 9509.24 Million |
Market Overview:
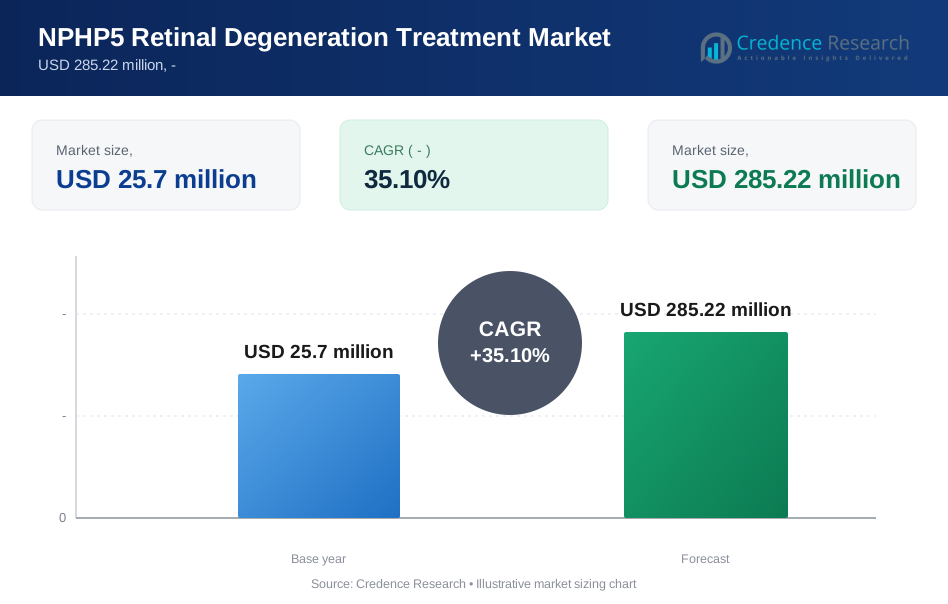
The global NPHP5 retinal degeneration treatment market is expected to grow significantly from USD 25.7 million in 2024 to USD 285.22 million by 2032, registering a robust CAGR of 35.10% during the forecast period. The market's growth trajectory is primarily driven by advancements in gene therapy, innovative treatment modalities, and the increasing prevalence of genetic retinal diseases, including nephronophthisis (NPHP5). With the rising awareness and diagnostic capabilities for retinal degeneration, there is a strong push towards developing targeted treatments that cater to the unmet needs of patients suffering from this rare genetic condition.
Key market drivers include the growing focus on personalized medicine and the significant investments in research and development for gene-based therapies. Pharmaceutical companies are collaborating with research institutions to accelerate clinical trials and bring innovative therapies to the market. Additionally, the increasing support from governmental and non-governmental organizations for orphan drug development is a critical driver. The rise in healthcare infrastructure and the availability of advanced diagnostic tools further contribute to the rapid market growth.
Regionally, North America dominates the NPHP5 retinal degeneration treatment market due to its strong healthcare system, early adoption of advanced therapies, and substantial investments in biotechnology. Europe is expected to witness significant growth, supported by increasing clinical trials and government support for rare disease treatments. Meanwhile, the Asia Pacific region is projected to grow at the highest CAGR, driven by improving healthcare infrastructure, rising awareness of retinal diseases, and the expansion of biotech companies in emerging markets like China and India.
Market Drivers:
Advancements in Gene Therapy:
One of the primary drivers of the NPHP5 retinal degeneration treatment market is the significant advancements in gene therapy. Breakthroughs in CRISPR and other gene-editing technologies have enabled precise targeting of genetic mutations responsible for retinal diseases. For instance, companies like Editas Medicine and CRISPR Therapeutics have developed gene-editing platforms that are showing promising results in treating inherited retinal disorders. The ability to directly modify the underlying genetic cause of retinal degeneration has fueled optimism in both clinical research and patient outcomes, leading to increased investment and innovation in this area.
Increasing Prevalence of Genetic Retinal Diseases:
The rising prevalence of genetic retinal diseases such as nephronophthisis is a critical factor driving the demand for effective treatments. According to government health surveys, genetic retinal disorders affect approximately 1 in 3,500 individuals globally, with a significant percentage remaining undiagnosed due to a lack of awareness and diagnostic tools. As genetic testing becomes more accessible, there has been a notable increase in the number of diagnosed cases. This growing patient pool has intensified the need for novel therapies, driving research and development efforts aimed at targeting specific genetic mutations like NPHP5.
Collaborations and Funding Initiatives:
Collaborations between pharmaceutical companies, research institutions, and government agencies have also played a pivotal role in driving the market. For example, the National Institutes of Health (NIH) in the U.S. has been actively funding gene therapy projects focused on rare genetic disorders, including retinal degeneration. In 2021, the NIH allocated over USD 300 million towards advancing gene-based therapies. Such funding initiatives not only provide financial support for ongoing research but also attract biotech companies to develop innovative therapies, accelerating the commercialization of treatments for NPHP5 retinal degeneration.
Growing Focus on Personalized Medicine:
The increasing emphasis on personalized medicine is another key driver shaping the NPHP5 retinal degeneration treatment market. Personalized medicine approaches tailor treatment plans based on an individual’s genetic makeup, ensuring higher efficacy and minimized side effects. This trend has prompted pharmaceutical companies to invest in developing therapies that target specific genetic mutations, including NPHP5. The global shift towards personalized treatment solutions is fostering the development of gene therapy programs, increasing their acceptance among healthcare providers and patients alike.
Market Trends:
Expansion of Clinical Trials:
A notable trend in the NPHP5 retinal degeneration treatment market is the expansion of clinical trials focusing on gene therapy and other innovative treatment modalities. Companies like Spark Therapeutics and RegenxBio have initiated several clinical trials aimed at testing the safety and efficacy of gene therapies for inherited retinal diseases. For instance, Spark Therapeutics’ Phase 1/2 trials demonstrated promising results in treating rare retinal disorders, which have paved the way for more targeted clinical studies. This increase in clinical trials is crucial for advancing the development pipeline and bringing new therapies to patients faster.
Increasing Regulatory Approvals:
The regulatory landscape for gene-based treatments is evolving rapidly, with more therapies gaining approval from regulatory authorities. The U.S. Food and Drug Administration (FDA) and the European Medicines Agency (EMA) have streamlined the approval process for orphan drugs and gene therapies, recognizing the urgent need for effective treatments for rare diseases. For instance, the FDA approved Luxturna, a gene therapy for retinal dystrophy, marking a significant milestone in the treatment of inherited retinal diseases. This shift in regulatory frameworks encourages companies to accelerate their development timelines and seek approvals for therapies targeting NPHP5.
Growing Patient Advocacy and Awareness:
Patient advocacy groups and organizations dedicated to rare diseases are playing an increasingly important role in driving awareness and funding for retinal degeneration treatments. Groups like the Foundation Fighting Blindness and the Retina International Consortium have been instrumental in raising awareness about genetic retinal disorders and advocating for increased research funding. For example, the Foundation Fighting Blindness has raised over USD 100 million to support research into retinal degenerative diseases. This increased awareness helps bridge the gap between scientific research and patient needs, ultimately pushing forward the development of new treatments.
Adoption of Advanced Diagnostic Tools:
Another key trend in the NPHP5 retinal degeneration treatment landscape is the growing adoption of advanced diagnostic tools. Innovations in genetic testing and imaging technologies have significantly improved the early diagnosis of retinal degeneration. For instance, next-generation sequencing (NGS) technologies allow for comprehensive genetic testing that can identify specific mutations like NPHP5 with high accuracy. This advancement enables more precise diagnosis and better treatment planning, which is essential for the success of gene therapy and other targeted treatments in this field.
Market Challenges Analysis:
High Costs of Gene Therapies:
One of the key restraints in the NPHP5 Retinal Degeneration Treatment market is the high cost associated with advanced gene therapies. The development and commercialization of gene-based treatments require significant investment in technology, research, and clinical trials. For instance, gene therapies approved for other retinal disorders, such as Luxturna, are priced at approximately USD 850,000 per treatment, which limits accessibility for many patients. These high costs pose a substantial barrier, especially in regions with limited healthcare funding or inadequate insurance coverage, making advanced therapies out of reach for a large portion of the affected population.
Limited Understanding of Genetic Variability:
Another significant challenge is the limited understanding of the genetic variability associated with NPHP5 retinal degeneration. While there have been advances in identifying the genetic mutations responsible for this condition, gaps in knowledge remain regarding the full spectrum of genetic variations and their impact on disease progression. This incomplete understanding makes it difficult for researchers to develop highly targeted treatments, and can also complicate the diagnostic process, leading to delays in identifying patients eligible for specific therapies. This genetic complexity hinders the development of effective and universally applicable treatments.
Regulatory and Approval Challenges:
Navigating the regulatory landscape for gene therapies presents additional hurdles. Regulatory bodies such as the FDA and EMA have stringent safety and efficacy requirements, necessitating extensive clinical trials and long-term patient monitoring. For instance, proving the long-term effectiveness and safety of gene therapies involves significant time and financial investment. These regulatory challenges can delay the introduction of new treatments to the market, slowing the progress of innovative therapies for NPHP5 retinal degeneration.
Small Patient Population:
The rarity of NPHP5 retinal degeneration also presents a commercial challenge. The small patient population limits the potential market size, making it less attractive for pharmaceutical companies to invest in costly drug development. This reduced commercial viability can slow down innovation and limit the availability of effective treatments for this rare condition.
Market Segmentation Analysis:
By Type, the market is divided into Gene Therapy, Stem Cell Therapy, and Drug Therapy. Gene therapy is expected to dominate this segment due to its ability to target the root cause of the disease by addressing specific genetic mutations like NPHP5. Stem cell therapy is gaining traction as an emerging treatment option, with advancements in regenerative medicine supporting its growth. Drug therapy remains important for symptom management and supportive care.
By Technology, the market is categorized into CRISPR-Cas9, AAV Vectors, and Lentiviral Vectors. CRISPR-Cas9 technology is driving significant innovation in the field, allowing precise editing of defective genes responsible for retinal degeneration. AAV vectors, already a well-established method for delivering genetic material, are being further developed to enhance safety and efficiency in retinal therapies. Lentiviral vectors are also gaining attention for their long-lasting expression in target cells, making them a viable option for gene therapy.
By End User, the market is segmented into Hospitals, Specialty Clinics, and Research Institutes. Hospitals are the largest end user segment due to their advanced infrastructure and expertise in handling complex gene therapies. Specialty clinics are increasingly involved in providing personalized care for rare genetic conditions, while research institutes play a pivotal role in advancing clinical trials and the development of novel treatments.
Segmentation:
By Treatment Type- Gene Therapy
- Cell Therapy
- Drug Therapy
- Others
- Retinitis Pigmentosa
- Leber Congenital Amaurosis
- Usher Syndrome
- Others
- Retail Pharmacies
- Hospital Pharmacies
- Online Pharmacies
- North America
- US
- Canada
- Latin America
- Brazil
- Argentina
- Mexico
- Rest of Latin America
- Europe
- Germany
- UK
- Spain
- France
- Italy
- Russia
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- Australia
- South Korea
- ASEAN
- Rest of Asia Pacific
- Middle East
- GCC
- Israel
- Rest of Middle East
- Africa
- South Africa
- North Africa
- Central Africa
Regional Analysis:
North America
North America holds the largest market share in the NPHP5 retinal degeneration treatment market, accounting for approximately 40% of the global market. The region's dominance is driven by advanced healthcare infrastructure, robust research and development investments, and early adoption of gene therapies. The United States leads this region, with key biotechnology companies and research institutions, such as Editas Medicine and Spark Therapeutics, pioneering gene-based therapies. Government support, including significant funding from the National Institutes of Health (NIH), further accelerates research into rare retinal diseases like NPHP5. The well-established regulatory framework of the U.S. Food and Drug Administration (FDA) facilitates the approval and commercialization of these innovative therapies, contributing to the market's growth in this region.
Europe
Europe accounts for around 30% of the global NPHP5 retinal degeneration treatment market. Countries such as Germany, France, and the United Kingdom are leading the region in terms of clinical trials and adoption of gene therapies. The European Medicines Agency (EMA) has created favorable regulatory pathways for orphan drugs and gene-based treatments, making it easier for companies to gain approval for novel therapies. Furthermore, government initiatives and patient advocacy groups in Europe are driving increased awareness and funding for rare genetic diseases. Collaborations between pharmaceutical companies and research institutions, particularly in Germany and the UK, are helping to expand treatment options for patients with retinal degenerative diseases.
Asia-Pacific
The Asia-Pacific region is expected to witness the fastest growth in the NPHP5 retinal degeneration treatment market, with a projected market share of 20% by 2032. This growth is fueled by improvements in healthcare infrastructure, rising awareness of genetic disorders, and increasing investments in biotechnological research. Countries such as China, Japan, and South Korea are at the forefront of this growth, with governments actively supporting clinical research and development of rare disease treatments. The growing adoption of advanced diagnostic tools, such as genetic testing, is also driving demand for more targeted therapies in the region. Additionally, emerging markets like India are investing in healthcare innovation, further boosting the market's growth.
Latin America and Middle East & Africa
Latin America and the Middle East & Africa collectively account for around 10% of the global market. In Latin America, countries such as Brazil and Mexico are seeing a gradual increase in the adoption of advanced treatments as healthcare infrastructure improves and awareness of rare genetic diseases grows. In the Middle East & Africa, countries like Saudi Arabia and the UAE are investing in healthcare modernization, which includes support for innovative therapies like gene-based treatments. However, economic constraints and limited healthcare access in certain parts of these regions present challenges to widespread adoption. Nevertheless, as healthcare systems develop, these regions hold long-term potential for the NPHP5 retinal degeneration treatment market.
Key Player Analysis:
- Editas Medicine
- Spark Therapeutics
- CRISPR Therapeutics
- RegenxBio
- Nightstar Therapeutics
- Applied Genetic Technologies Corporation (AGTC)
- GenSight Biologics
- MeiraGTx
- ProQR Therapeutics
- 4D Molecular Therapeutics
Competitive Analysis:
The NPHP5 retinal degeneration treatment market is highly competitive, with key players focusing on developing innovative gene therapies to address the underlying genetic causes of the condition. Companies such as Editas Medicine, Spark Therapeutics, and CRISPR Therapeutics are leading the market, leveraging advancements in gene editing and vector technologies. These firms are heavily investing in research and clinical trials to improve treatment efficacy and safety. Additionally, companies like RegenxBio and Nightstar Therapeutics are actively working on adeno-associated viral (AAV) vector-based gene therapies, gaining traction in the market due to their precision and targeted approach. Collaborations and partnerships between biotechnology firms and research institutions are common, aimed at accelerating drug development and commercialization. However, the high cost of gene therapies and the rarity of NPHP5 retinal degeneration limit market opportunities, pushing companies to focus on niche patient populations while ensuring regulatory compliance and long-term patient outcomes.
Recent Developments:
- RegenxBio announced positive interim results from its Phase II AAVIATE trial in 2023. The study focuses on ABBV-RGX-314, a gene therapy delivered through suprachoroidal injection, showing promising outcomes in reducing the treatment burden for retinal diseases, including NPHP5-related conditions.
- Cognition Therapeutics launched its Phase II MAGNIFY study in early 2024, investigating the efficacy of CT1812, an oral medication aimed at slowing retinal damage processes. This trial focuses on dry AMD but highlights growing interest in addressing genetic retinal conditions like NPHP5.
- EyePoint Pharmaceuticals initiated its DAVIO-2 trial in 2023 to compare EYP-1901, a pan-VEGF receptor inhibitor, with traditional treatments for retinal degeneration. This drug could offer a less frequent dosing regimen, which may be applicable to NPHP5 patients.
- The Center for Hereditary Retinal Degenerations (CHRD) conducted a webinar in early 2024, showcasing research on gene therapies targeting NPHP5 mutations. The event emphasized the potential of emerging treatments for rare retinal diseases.
Market Concentration & Characteristics:
The NPHP5 Retinal Degeneration Treatment Market is moderately concentrated, with a few leading companies driving the majority of research and development activities. Key players such as Editas Medicine, CRISPR Therapeutics, and RegenxBio dominate the market through their advanced gene therapy programs. These companies benefit from significant research funding and partnerships with academic institutions, which helps them maintain a competitive edge. Additionally, the market is characterized by high barriers to entry due to the specialized nature of gene therapy, high development costs, and stringent regulatory requirements. The small patient population and the rarity of NPHP5 retinal degeneration further limit the number of participants in this niche market, although growing interest in personalized medicine and orphan drug incentives are driving innovation. As the field advances, collaboration between biotech firms and regulatory bodies is key to accelerating treatment availability.
Report Coverage:
The research report offers an in-depth analysis based on Treatment Type, Indication, Distribution Channel, and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Gene therapy is expected to remain the dominant treatment approach for NPHP5 retinal degeneration, with advancements in CRISPR technology enhancing precision and efficacy.
- Increased collaboration between biotech companies and research institutions will accelerate the development and commercialization of novel therapies.
- Regulatory agencies are likely to streamline approval processes for orphan drugs, making treatments more accessible to rare disease patients.
- Stem cell therapy, although still in early stages, shows promising potential to become a complementary treatment option for retinal regeneration.
- Advanced diagnostic tools, such as next-generation sequencing, will improve early detection and personalized treatment planning for NPHP5 patients.
- The rarity of NPHP5 retinal degeneration may encourage governments to provide more funding and support for clinical research and patient care.
- Orphan drug incentives will continue to attract pharmaceutical investments, driving further innovation in the treatment landscape.
- Increased awareness of genetic retinal diseases will push for greater patient advocacy and funding from non-profit organizations.
- The rise of telemedicine could facilitate better management and follow-up care for NPHP5 retinal degeneration patients.
- Long-term follow-up studies will be crucial in understanding the durability and safety of gene therapies, influencing future treatment protocols.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the NPHP5 Retinal Degeneration Treatment Market?
What factors are driving the growth of the NPHP5 Retinal Degeneration Treatment Market?
What are some challenges faced by the NPHP5 Retinal Degeneration Treatment Market?
Who are the major players in the NPHP5 Retinal Degeneration Treatment Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 NPHP5 Retinal Degeneration Treatment Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (the historical period; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global NPHP5 Retinal Degeneration Treatment Market Snapshot
- 2.1.1 Market Size – Historical (the historical period) & Forecast (the forecast period) (base year: USD 25.7 million → forecast year: USD 285.22 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 NPHP5 Retinal Degeneration Treatment Market Segmentation Snapshot
- 2.2.1 Market Split by Region – vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share –
- 2.3.2 Top 10 Players by Volume Share –
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. NPHP5 Retinal Degeneration Treatment Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 NPHP5 Retinal Degeneration Treatment Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 NPHP5 Retinal Degeneration Treatment Market Drivers
- 3.3 NPHP5 Retinal Degeneration Treatment Market Restraints & Challenges
- 3.4 NPHP5 Retinal Degeneration Treatment Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 NPHP5 Retinal Degeneration Treatment Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 NPHP5 Retinal Degeneration Treatment Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, NPHP5 Retinal Degeneration Treatment category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 NPHP5 Retinal Degeneration Treatment Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. NPHP5 Retinal Degeneration Treatment Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (the historical period)
- 5.1.2 Global Export Volume by Country (the historical period)
- 5.1.3 Global Import Value by Country (the historical period)
- 5.1.4 Global Import Volume by Country (the historical period)
- 5.1.5 Net Trade Balance by Country (the historical period)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (the historical period)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the NPHP5 Retinal Degeneration Treatment market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 NPHP5 Retinal Degeneration Treatment Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs.
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 NPHP5 Retinal Degeneration Treatment Market Share Analysis –
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. )
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 NPHP5 Retinal Degeneration Treatment Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in NPHP5 Retinal Degeneration Treatment (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New NPHP5 Retinal Degeneration Treatment Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global NPHP5 Retinal Degeneration Treatment Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel ( & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America NPHP5 Retinal Degeneration Treatment Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe NPHP5 Retinal Degeneration Treatment Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific NPHP5 Retinal Degeneration Treatment Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America NPHP5 Retinal Degeneration Treatment Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East NPHP5 Retinal Degeneration Treatment Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa NPHP5 Retinal Degeneration Treatment Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. NPHP5 Retinal Degeneration Treatment Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
