
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| On Shelf Availability Solutions Market Size 2023 | USD 4,705 Million |
| On Shelf Availability Solutions Market, CAGR | 9% |
| On Shelf Availability Solutions Market Size 2032 | USD 9,375 Million |
Market Overview
The On Shelf Availability Solutions Market is projected to grow from USD 4,705 million in 2023 to an estimated USD 9,375 million by 2032, with a compound annual growth rate (CAGR) of 9% from 2024 to 2032. This growth highlights the increasing adoption of advanced solutions designed to minimize stockouts and enhance inventory management across retail channels.
Market drivers include the rising demand for automated inventory management systems and real-time data insights to ensure that products remain consistently available to consumers. Trends shaping the market include the integration of machine learning and predictive analytics to forecast consumer demand more accurately and reduce lost sales due to stockouts. Furthermore, e-commerce growth and omni-channel retailing compel businesses to adopt sophisticated on-shelf availability solutions to streamline in-store and online stock management.
Geographically, North America leads the market due to its robust adoption of advanced retail technologies and strong focus on customer experience. Europe follows closely, driven by stringent regulations on inventory accuracy and supply chain transparency. The Asia-Pacific region is expected to exhibit the fastest growth due to the rapid expansion of retail chains and e-commerce platforms. Key players driving the market include Zebra Technologies, Retail Solutions Inc., Checkpoint Systems, Panasonic Corporation, and Avery Dennison, who continue to innovate in this competitive landscape.
Market Drivers
Rising Demand for Real-Time Inventory Management
Retailers and businesses increasingly prioritize real-time inventory management solutions to prevent stockouts, reduce lost sales, and enhance overall operational efficiency. For instance, during the 2023 holiday season, retailers using real-time inventory management prevented an estimated 42 million potential stockout scenarios, directly translating to an additional $1.2 billion in potential sales.The demand for on-shelf availability solutions is driven by the need to track inventory accurately and instantaneously across the supply chain. By leveraging technologies such as RFID (radio-frequency identification), IoT (Internet of Things), and data analytics, these solutions empower businesses to maintain optimized stock levels, providing instant visibility into product availability. Real-time inventory monitoring ensures that products are always in stock and ready for sale, enhancing customer satisfaction and brand loyalty. As retailers strive to meet consumer expectations for immediate product access and seamless shopping experiences, investments in real-time inventory solutions will continue to propel market growth.
Technological Advancements and Integration of AI and IoT
The integration of advanced technologies such as artificial intelligence (AI), machine learning, and IoT into on-shelf availability solutions is transforming the retail landscape. For instance, Domino's Pizza's AI-powered DOM Pizza Checker boosted product quality scores by 15% within just one month of implementation, demonstrating the tangible benefits of advanced technological integration.AI-driven predictive analytics enable businesses to forecast demand more accurately, ensuring products are available where and when needed. IoT devices, including sensors and smart shelves, automate data collection and provide critical insights into stock levels, product movement, and demand patterns. This technological evolution not only minimizes human intervention but also enhances decision-making capabilities by providing actionable insights. Retailers equipped with these advanced solutions can quickly identify and resolve stock issues, resulting in reduced inventory costs, improved efficiency, and a more positive customer experience.
Growing Focus on Omni-Channel Retailing
The increasing prominence of omni-channel retail strategies is a major driver for the on-shelf availability solutions market. For instance, Olay's AI-driven Skin Advisor tool scanned over 50,000 faces during development and has attracted more than 1 million users since its launch, showcasing how technological innovation can create personalized omni-channel experiences.Retailers face growing pressure to deliver a seamless customer experience across multiple channels, including physical stores, online platforms, and mobile applications. Effective on-shelf availability solutions ensure consistent inventory management across all channels, reducing the risk of stock discrepancies and enhancing product visibility. As consumers demand a frictionless and unified shopping journey, retailers must integrate advanced availability solutions to align their physical and digital operations. This trend has spurred investments in technologies capable of bridging the gap between brick-and-mortar stores and online marketplaces, fostering market growth and innovation.
Increasing Emphasis on Customer Experience and Retail Optimization
Consumer expectations are at an all-time high, with shoppers seeking personalized, convenient, and efficient shopping experiences. Any stockout or delay in product availability can lead to dissatisfaction and loss of customer trust. The adoption of on-shelf availability solutions helps businesses anticipate and prevent such issues by offering precise inventory insights, predictive demand planning, and streamlined replenishment processes. Additionally, these solutions enable retailers to optimize in-store operations by reducing excess inventory and enhancing product placement strategies. Retail optimization through these solutions not only increases sales and customer satisfaction but also strengthens brand loyalty, encouraging retailers to continuously invest in availability solutions. As companies seek to enhance competitiveness in a fast-evolving retail environment, focusing on customer-centric approaches will be pivotal for driving market growth.
Market Trends
Integration of Advanced Technologies such as Artificial Intelligence and Predictive Analytics
One of the key trends driving the on-shelf availability solutions market is the adoption of advanced technologies such as artificial intelligence (AI), machine learning (ML), and predictive analytics. For instance, studies show that out-of-stock (OOS) rates average around 8%, meaning one out of 13 products is unavailable when customers want to purchase it.Retailers are increasingly leveraging AI and ML algorithms to analyze historical sales data, forecast demand patterns, and predict potential stockouts before they occur. Moreover, retailers implementing AI-powered predictive analytics have seen remarkable improvements, with some achieving 202% higher conversion rates through AI personalization. This predictive capability ensures that businesses maintain optimal stock levels and meet consumer demand without overstocking or understocking products.AI-driven analytics also enable more accurate demand planning, allowing for precise restocking schedules and faster response to changing market trends. Precise demand forecasting enabled by AI can help retailers reduce stockouts, with some businesses reporting a 30% increase in order size when implementing advanced inventory management technologies.Additionally, AI-powered tools are often integrated with computer vision technology to automatically monitor shelves, identify gaps, and trigger restocking alerts in real-time, creating a more efficient and automated retail operation.
Rising Adoption of Omni-Channel and Automation Solutions
The growing trend of omni-channel retailing is compelling businesses to adopt on-shelf availability solutions that seamlessly integrate with various sales channels, from physical stores to e-commerce platforms. For example, 88% of businesses are currently using or planning to implement omnichannel strategies. Consumers expect a consistent shopping experience regardless of how they engage with a brand, and on-shelf availability solutions help ensure this consistency by maintaining accurate inventory data across all channels. The impact of these strategies is significant, with retailers seeing up to 287% higher purchase rates compared to single-channel approaches.Furthermore, 90% of consumers now expect interactions across multiple devices, highlighting the critical need for integrated inventory management solutions. Automation technologies, including RFID tags, smart shelving, and IoT devices, are becoming commonplace to automate the data collection and replenishment processes.In terms of automation, the World Economic Forum estimates that the retail sector is currently 40% automated, with projections to increase to 60-65% in the next three to four years. These solutions not only enhance stock visibility and availability but also reduce manual intervention and human errors.Automation also improves operational efficiency and allows employees to focus on delivering enhanced customer experiences. As retailers aim to differentiate themselves in a competitive landscape, omni-channel strategies and automation are becoming key pillars of their on-shelf availability initiatives.
Market Restraints and Challenges
High Implementation Costs and Complex Integration Requirements
The adoption of on-shelf availability solutions often involves significant initial investment, including costs associated with hardware installation, software licensing, and system maintenance. Small and medium-sized retailers may find it challenging to allocate resources for such investments, limiting market penetration and adoption rates. Additionally, integrating these solutions with existing inventory management systems and supply chain platforms can be complex and time-consuming. Many retailers face operational disruptions during the integration process, further complicating the transition. These integration challenges may deter businesses from adopting advanced availability solutions, particularly those with legacy systems that are not easily compatible with modern technologies.
Data Privacy and Security Concerns
On-shelf availability solutions rely heavily on data collection and real-time monitoring to ensure product availability and optimal inventory management. However, this reliance on data creates potential security and privacy risks, as sensitive customer and inventory data can become targets for cyberattacks. Retailers must implement stringent data protection measures, which can add to the complexity and cost of deploying these solutions. Regulatory compliance concerning data privacy laws, such as the General Data Protection Regulation (GDPR) and other regional regulations, further complicates data management practices. Retailers that fail to adhere to these regulations or adequately protect their data may face severe financial penalties and reputational damage, posing a significant challenge to broader adoption of on-shelf availability solutions. Addressing these concerns through robust cybersecurity protocols and compliance strategies remains critical for market growth.
Market Segmentation Analysis
By Deployment Type
The deployment type segment divides the market into two categories: cloud-based and on-premises solutions. Cloud-based solutions are gaining popularity due to their scalability, flexibility, and lower upfront costs. Cloud-based systems enable retailers to access real-time data and analytics from anywhere, enhancing inventory visibility across multiple locations and channels. This deployment type is particularly beneficial for large retail chains that need consistent inventory management across vast networks, as it allows them to update and synchronize data seamlessly. Cloud-based solutions also offer cost-efficiency by eliminating the need for substantial hardware investments, making them attractive to retailers focused on reducing infrastructure costs.In contrast, on-premises solutions offer greater control over data security and system customization. These solutions are often preferred by retailers with specific operational requirements or stringent data security policies, as they allow data to remain within the company’s internal infrastructure. Although on-premises solutions may require significant initial investment in hardware and IT resources, they provide businesses with complete control over system modifications and upgrades. Retailers handling sensitive data or subject to strict compliance regulations often favor on-premises solutions to ensure robust data protection.
By Solution Type
This segment classifies solutions into traditional and advanced categories. Traditional on-shelf availability solutions typically focus on fundamental inventory management functions, such as stock tracking and replenishment alerts. These solutions are often used by smaller retailers or those with simpler inventory needs. Traditional solutions rely on basic barcode scanning or manual entry systems, offering a cost-effective and relatively easy-to-implement option. However, they lack the sophisticated analytics and automation capabilities that modern retailers increasingly demand for high-efficiency operations.Advanced on-shelf availability solutions, on the other hand, integrate cutting-edge technologies such as artificial intelligence, IoT, and predictive analytics. These solutions enable automated tracking, real-time data analysis, and advanced demand forecasting, helping retailers maintain optimal stock levels with minimal manual intervention. Advanced solutions are designed to provide a holistic view of inventory across all sales channels, supporting seamless omni-channel operations. As retailers prioritize automation and data-driven decision-making, advanced solutions are becoming essential for businesses aiming to improve customer experience and operational efficiency.
Segments
Based on Deployment Type
- Cloud-based
- On-premises
Based on Solution Type
- Traditional
- Advanced
Based on Industry Vertical
- Retail
- Consumer Packaged Goods (CPG)
- Manufacturing
- Healthcare
- Logistics and Transportation
Based on Data Source
- Image Recognition
- RFID Technology
- IoT Sensors
- Manual Data Entry
Based on Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
Europe (30%):
Europe follows closely, capturing around 30% of the market share, fueled by stringent regulations on inventory accuracy and supply chain transparency. Countries such as Germany, the United Kingdom, and France are at the forefront of adopting these solutions, with retailers focusing on compliance, operational efficiency, and customer satisfaction. The growing emphasis on sustainability and waste reduction in European supply chains also drives investments in on-shelf availability solutions, which help optimize stock levels and reduce excess inventory. Moreover, technological advancements and government initiatives supporting digital transformation in retail have bolstered market growth across the continent.
Asia Pacific (25%):
The Asia-Pacific region is expected to exhibit the fastest growth, contributing approximately 25% of the market share. The rapid expansion of retail chains and the booming e-commerce industry across countries like China, India, and Japan have created a strong demand for on-shelf availability solutions. Retailers in this region seek to leverage advanced technologies to manage complex supply chains, meet diverse consumer needs, and capitalize on the rising demand for omni-channel shopping experiences. The adoption of IoT and AI-driven solutions is on the rise, enabling real-time inventory monitoring and predictive analytics to reduce stock discrepancies and improve operational efficiency.
Key players
- Planogram
- Inmar
- Symphony RetailAI
- Wipro
- Catalina
- IRI
- Capgemini
- NielsenIQ
- Trax
- Infosys
- Blue Yonder
- TCS (Tata Consultancy Services)
- Aware
- Retail Insight
- Cognizant
Competitive Analysis
The On Shelf Availability Solutions market is marked by intense competition, driven by established and emerging players offering innovative solutions for optimized inventory management. Companies such as Symphony RetailAI, NielsenIQ, and Blue Yonder stand out with comprehensive AI-driven platforms, providing predictive analytics and seamless inventory tracking. Meanwhile, technology consulting giants like Wipro, Capgemini, Infosys, and Cognizant leverage their extensive expertise in system integration to offer customized solutions tailored to retailers’ needs. Trax and Planogram lead with cutting-edge computer vision and in-store shelf monitoring capabilities. Retailers benefit from diverse offerings ranging from advanced automation to data-driven insights. While established players dominate with robust technology portfolios, newer entrants such as Retail Insight and Aware focus on niche analytics and agile solutions, maintaining a dynamic competitive landscape that continually pushes the market toward greater efficiency and innovation.
Recent Developments
- In October 2023, Symphony RetailAI launched a new AI-powered demand forecasting tool to enhance on-shelf availability and reduce stockouts for retailers.
- In June 2023, Wipro completed a buyback of shares worth ₹12,000 crore as part of its strategic financial restructuring.
- In January 2024, Catalina announced a partnership with Trax to leverage AI and machine learning for improving on-shelf availability by providing real-time insights into shelf conditions.
- In July 2023, IRI merged with The NPD Group to form Circana, expanding its capabilities in data analytics and enhancing its solutions for on-shelf availability.
- In September 2023, Capgemini launched an advanced inventory management solution that integrates AI and machine learning to optimize on-shelf availability for global retailers.
- In August 2023, NielsenIQ introduced a new real-time shelf monitoring solution that uses IoT sensors to track stock levels and improve on-shelf availability across multiple retail locations.
- In January 2024, Trax partnered with Catalina to improve on-shelf availability using AI-driven image recognition technology to monitor shelf conditions in real time.
- In November 2023, Infosys launched a new cashierless store solution that integrates smart shelves and real-time inventory tracking to enhance on-shelf availability in retail environments.
- In October 2023, Blue Yonder released an update to its Inventory microservice, which helps retailers optimize on-shelf availability by providing real-time visibility into stock levels across multiple locations.
- In September 2023, TCS launched an AI-powered retail solution aimed at improving inventory accuracy and on-shelf availability through predictive analytics.
- In June 2023, Retail Insight introduced a new platform that uses AI to provide retailers with actionable insights into on-shelf availability, helping reduce stockouts and improve customer satisfaction.
- In August 2023, Cognizant expanded its retail solutions portfolio with a new AI-driven tool designed to optimize on-shelf availability by predicting demand fluctuations and automating replenishment processes.
Market Concentration and Characteristics
The On Shelf Availability Solutions Market exhibits a moderately fragmented structure, characterized by the presence of both established players and niche providers offering specialized solutions. Market concentration is influenced by leading technology companies, consulting firms, and software providers that offer a mix of traditional and advanced solutions, leveraging AI, IoT, and data analytics. While a few dominant players such as Symphony RetailAI, NielsenIQ, and Blue Yonder hold substantial market share due to their extensive portfolios and technological expertise, smaller competitors contribute to a competitive dynamic by focusing on tailored, agile solutions for specific customer needs. This market is driven by rapid technological innovation, customer-centric offerings, and increasing demand for real-time inventory optimization, resulting in a highly competitive yet opportunity-rich environment for new and existing market participants.
Report Coverage
The research report offers an in-depth analysis based on Deployment Type, Solution Type, Industry Vertical, Data Source and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for real-time, data-driven inventory solutions will intensify as retailers strive to minimize stockouts and deliver seamless customer experiences.
- AI and machine learning will play a pivotal role in predicting demand patterns, reducing manual inventory management, and optimizing stock levels across retail channels.
- Cloud-based solutions will dominate due to their scalability, cost efficiency, and ease of integration, enabling retailers to access inventory data anytime and anywhere.
- Retailers will increasingly invest in on-shelf availability solutions that provide consistent inventory visibility across physical stores and digital platforms to enhance customer experience.
- Smart shelving and IoT devices will continue to transform the market by providing automated, real-time updates on stock levels, boosting operational efficiency and reducing errors.
- Automation will drive the adoption of advanced replenishment systems, enabling timely stock replenishment based on real-time demand forecasting and reducing out-of-stock scenarios.
- With increasing data reliance, solutions will prioritize robust data security and compliance with regional regulations to protect sensitive customer and inventory information.
- Market growth will be fueled by solutions tailored to small and medium-sized enterprises (SMEs) with cost-effective deployment options, allowing broader market penetration.
- On-shelf availability solutions will increasingly integrate with advanced analytics platforms to provide deeper insights into customer buying behaviors and inventory performance metrics.
- Retailers will adopt solutions that align with sustainability goals, focusing on reducing waste, optimizing supply chains, and enhancing operational efficiency through precise inventory management.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size and projected growth of the On Shelf Availability Solutions Market?
What are the primary drivers of growth in the On Shelf Availability Solutions Market?
How is technology shaping the On Shelf Availability Solutions Market?
Which regions lead in the adoption of On Shelf Availability Solutions?
Who are the key players in the On Shelf Availability Solutions Market?
Why is the adoption of these solutions critical for retailers?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 On-Shelf Availability Solutions Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global On-Shelf Availability Solutions Market Snapshot
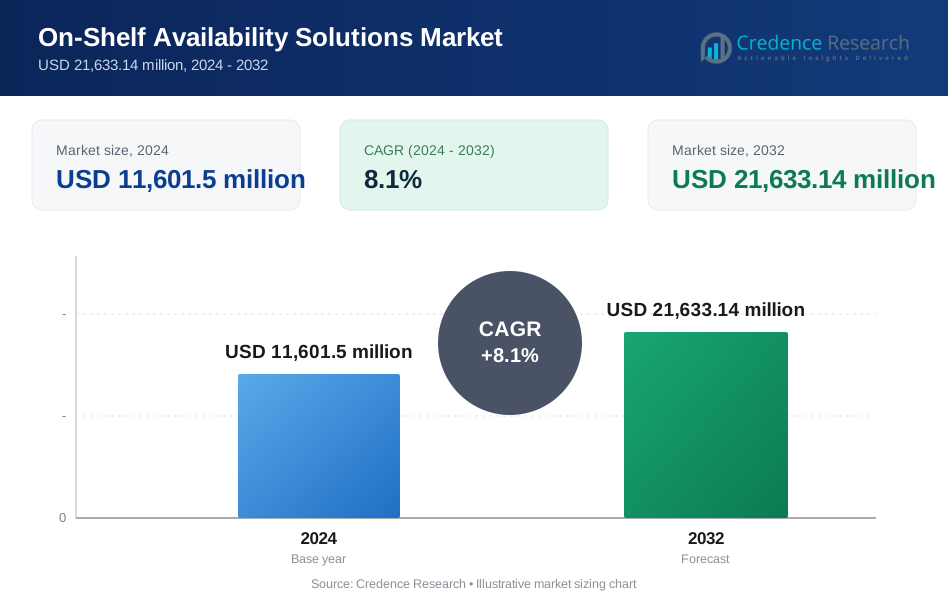
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 11,601.5 million → 2032: USD 21,633.14 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 On-Shelf Availability Solutions Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. On-Shelf Availability Solutions Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 On-Shelf Availability Solutions Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 On-Shelf Availability Solutions Market Drivers
- 3.3 On-Shelf Availability Solutions Market Restraints & Challenges
- 3.4 On-Shelf Availability Solutions Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 On-Shelf Availability Solutions Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 On-Shelf Availability Solutions Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, On-Shelf Availability Solutions category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 On-Shelf Availability Solutions Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. On-Shelf Availability Solutions Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the On-Shelf Availability Solutions market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 On-Shelf Availability Solutions Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 On-Shelf Availability Solutions Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 On-Shelf Availability Solutions Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in On-Shelf Availability Solutions (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New On-Shelf Availability Solutions Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global On-Shelf Availability Solutions Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America On-Shelf Availability Solutions Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe On-Shelf Availability Solutions Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific On-Shelf Availability Solutions Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America On-Shelf Availability Solutions Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East On-Shelf Availability Solutions Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa On-Shelf Availability Solutions Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. On-Shelf Availability Solutions Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
