
Market Overview
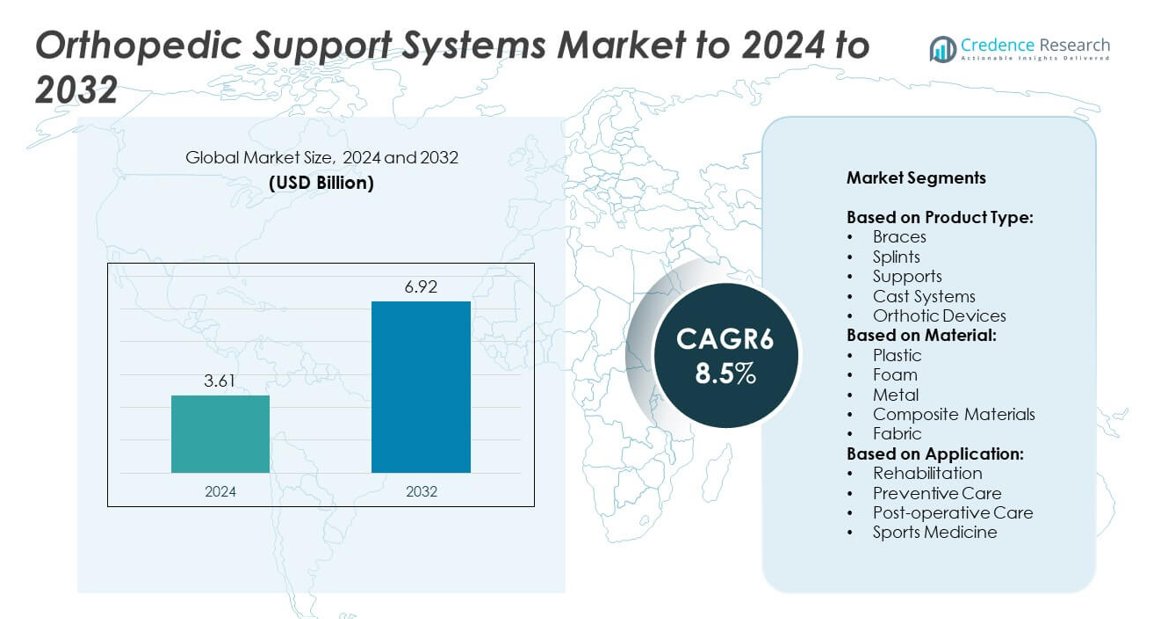
Orthopedic Support Systems Market size was valued at USD 3.61 billion in 2024 and is anticipated to reach USD 6.92 billion by 2032, at a CAGR of 8.5% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Orthopedic Support Systems Market Size 2024 | USD 3.61 billion |
| Orthopedic Support Systems Market, CAGR | 8.5% |
| Orthopedic Support Systems Market Size 2032 | USD 6.92 billion |
The orthopedic support systems market is driven by major players including Otto Bock, Stryker Corporation, DJO Global, Zimmer Biomet, Medtronic, Smith Nephew, B. Braun Melsungen, DePuy Synthes, and Orthofix International. These companies focus on product innovation, advanced materials, and strategic collaborations to expand their global footprint. North America led the market in 2024 with a 34% share, supported by high healthcare spending, strong adoption of advanced orthopedic devices, and a growing elderly population. Europe followed with a 28% share, driven by rising incidences of musculoskeletal disorders and emphasis on preventive and rehabilitative care solutions.
Market Insights
- The orthopedic support systems market was valued at USD 3.61 billion in 2024 and is projected to reach USD 6.92 billion by 2032, expanding at a CAGR of 8.5%.
- Rising prevalence of musculoskeletal disorders, growing elderly population, and increasing sports injuries are the key drivers accelerating adoption of braces, supports, and orthotic devices.
- Market trends highlight growing demand for customized and smart devices, with 3D printing and sensor-based technologies gaining traction, while preventive care supports see rising adoption in daily activities.
- The competitive landscape is fragmented with global players focusing on innovation, ergonomic designs, and partnerships, while cost-effective product lines are being developed to capture emerging market demand.
- Regionally, North America led with 34% share in 2024, followed by Europe at 28% and Asia Pacific at 23%, while braces dominated the product segment with over 35% share due to widespread usage in rehabilitation and corrective care.
Market Segmentation Analysis:
By Product Type
Braces dominated the orthopedic support systems market in 2024 with over 35% share. Their widespread use in treating musculoskeletal conditions, sports injuries, and post-surgical recovery supports this leadership. Braces provide adjustable stability, pain relief, and mobility assistance, making them the first choice for both preventive and corrective care. Rising sports participation and the increasing prevalence of joint-related disorders further fuel demand. Splints and supports are growing steadily due to rising rehabilitation needs, while orthotic devices are gaining momentum through advanced designs improving patient comfort and compliance.
- For instance, Össur reported that in 2023, its Bracing & Supports sales grew by 3 % organically.
By Material
Plastic-based products held the largest share of more than 30% in 2024, owing to their versatility, lightweight nature, and cost-effectiveness. Plastics allow easy molding, making them suitable for customized braces, splints, and cast systems. The segment benefits from advancements in polymer composites that improve strength and durability. Foam-based supports also witness strong adoption due to comfort and cushioning features, particularly in long-term rehabilitation. Metal and composite materials remain vital for high-strength applications in orthopedic devices, while fabrics are increasingly used in flexible supports designed for preventive care and sports medicine.
- For instance, Zimmer Biomet’s ComposiTCP suture anchors, available in various sizes, are made of DuoSorb®, a proprietary biocomposite material composed of 30% \(\beta \)-Tricalcium Phosphate (\(\beta \)-TCP) and 70% Polylactic Acid (PLDL), which balances strength and elasticity similar to cortical bone.
By Application
Rehabilitation accounted for the largest market share of around 40% in 2024, driven by the rising prevalence of orthopedic injuries and post-trauma therapies. Patients recovering from fractures, joint replacements, and spinal conditions require extensive support systems to restore function and mobility. Preventive care is another significant segment, supported by growing awareness of musculoskeletal health and the demand for wearable supports in daily activities. Post-operative care continues to expand as surgical procedures increase globally, while sports medicine sees strong growth due to higher injury incidences among professional athletes and recreational participants.
Key Growth Drivers
Rising Prevalence of Musculoskeletal Disorders
The growing incidence of arthritis, osteoporosis, and joint injuries is a major driver for the orthopedic support systems market. Aging populations in developed regions and increasing lifestyle-related disorders globally have led to higher demand for braces, supports, and orthotic devices. This segment benefits from improved awareness of non-invasive treatment options, which provide effective pain management and mobility support. With musculoskeletal conditions ranked among the leading causes of disability, the demand for orthopedic support systems continues to expand significantly across healthcare and rehabilitation settings.
- For instance, Breg, a leading provider of orthopedic bracing and support solutions, reports that its products serve over 5 million patients annually. As of April 2024, the company had formed a strategic alliance with RevSpring, which integrated with Breg's software at more than 2,500 U.S. clinics.
Expanding Sports and Fitness Activities
The rising participation in sports and recreational activities has increased injury rates, fueling adoption of orthopedic braces, supports, and splints. Professional athletes and fitness enthusiasts are highly reliant on preventive and corrective support systems for faster recovery and injury prevention. Sports medicine has become a critical application segment, especially with advanced support designs catering to high-performance needs. Growing awareness about preventive healthcare among younger demographics further supports this trend. This surge in sports-related injuries makes orthopedic supports a key solution for active individuals worldwide.
- For instance, Enovis (DonJoy) reports that over 2 million Defiance braces have been prescribed. Furthermore, DonJoy braces are used by every team in the AP Top 25 college football rankings, according to an Enovis social media post from December 2024.
Technological Advancements in Orthopedic Devices
Innovation in material science and product design significantly drives market expansion. Lightweight, durable, and customizable materials such as composites and advanced plastics enhance patient comfort and compliance. Digitalization has introduced 3D printing for tailored orthotic devices, allowing precision fitting for individual patients. Additionally, integration of smart technologies, including sensor-based monitoring, provides real-time rehabilitation data. These advancements improve treatment outcomes and reduce long-term healthcare costs. Such technological progress positions orthopedic support systems as more effective and patient-friendly solutions, accelerating adoption across hospitals and homecare.
Key Trends & Opportunities
Growing Focus on Preventive Care
Preventive orthopedic support systems are gaining traction as consumers become more health-conscious. Increasing demand for supports and braces in daily life and workplace settings highlights this shift. Lightweight and fabric-based supports are particularly popular, offering comfort for long-term use. Companies are introducing ergonomically designed products that prevent musculoskeletal stress before injuries occur. This preventive trend presents opportunities for expansion in both developed and emerging markets, as awareness campaigns and digital retail platforms make orthopedic supports more accessible to a wider consumer base.
- For instance, Medi GmbH & Co. KG manufactures a wide range of orthopedic products, including the medi ROM Walker and protect.4 sports braces, and exports to more than 90 countries worldwide.
Rising Demand for Customized and Smart Devices
Personalized orthopedic support systems are an emerging trend, with 3D printing enabling patient-specific braces and orthotics. Customization ensures better fit, comfort, and therapeutic efficiency, driving adoption in rehabilitation and post-operative care. Additionally, the integration of smart sensors provides opportunities for real-time monitoring of mobility, compliance, and recovery progress. These connected devices are gaining acceptance in sports medicine and homecare due to their ability to provide data-driven insights. The trend toward customized and smart orthopedic supports reflects the growing emphasis on digital health and patient-centric solutions.
- For instance, as of September 2023, 62 CUVIS systems had been installed across India. Later, in 2024, Meril launched a new robotic system, MISSO, which quickly achieved over 50 installations in India within a short period."
Key Challenges
High Cost of Advanced Orthopedic Supports
One of the major challenges in the market is the high cost of advanced support systems. Devices with customized features, smart sensors, or advanced materials remain expensive, limiting accessibility in low-income regions. Many patients prefer low-cost traditional alternatives, slowing adoption of innovative solutions. Reimbursement limitations in several healthcare systems also restrict patient access. This cost barrier creates disparities between developed and emerging markets, where affordability plays a critical role in adoption. Addressing price sensitivity is crucial for wider market penetration and sustained growth.
Limited Awareness and Compliance Issues
Despite their effectiveness, orthopedic support systems often face limited adoption due to lack of awareness in emerging economies. Patients may underuse or misuse supports, reducing their therapeutic effectiveness. Compliance is another challenge, as bulky or uncomfortable devices discourage prolonged use. Inadequate patient education and cultural perceptions of mobility aids further add to the issue. Healthcare providers must prioritize awareness campaigns and training to ensure proper usage. Overcoming these compliance barriers is essential to unlocking the full potential of orthopedic support systems.
Regional Analysis
North America
North America held the largest share of 34% in the orthopedic support systems market in 2024. The region benefits from advanced healthcare infrastructure, high awareness about musculoskeletal health, and strong adoption of innovative orthopedic devices. The growing elderly population and high prevalence of arthritis and sports-related injuries continue to drive demand. Strong reimbursement frameworks and the presence of leading manufacturers also support growth. The United States remains the dominant contributor within the region, supported by high healthcare spending, increasing orthopedic surgeries, and widespread use of preventive and rehabilitative care systems across hospitals and homecare settings.
Europe
Europe accounted for 28% of the global orthopedic support systems market in 2024, driven by strong adoption in countries like Germany, France, and the United Kingdom. Rising demand is supported by the growing geriatric population, coupled with higher incidences of bone and joint disorders. The region emphasizes preventive care, with government initiatives promoting early diagnosis and non-invasive treatments. Sports medicine is also expanding due to higher participation in professional and recreational activities. European manufacturers focus on product innovation and regulatory compliance, ensuring steady demand for braces, orthotics, and rehabilitation devices across hospitals and homecare environments.
Asia Pacific
Asia Pacific captured a market share of 23% in 2024 and is expected to show the fastest growth. The rising burden of osteoporosis, arthritis, and trauma injuries in countries such as China, India, and Japan is fueling adoption. Expanding healthcare access, increasing investments in hospitals, and a growing focus on sports and fitness are key growth drivers. Affordable manufacturing and distribution have also improved accessibility of orthopedic devices in the region. Additionally, rapid urbanization and lifestyle changes are increasing the demand for preventive orthopedic supports, while multinational companies are strengthening their presence through regional partnerships and product localization.
Latin America
Latin America represented 8% of the orthopedic support systems market in 2024, with Brazil and Mexico serving as the largest contributors. The market is growing due to increasing healthcare expenditure, expanding private hospital networks, and greater awareness of musculoskeletal disorders. Sports injuries and road accidents are major contributors to the rising demand for braces, splints, and supports. However, cost sensitivity limits the adoption of advanced devices, creating demand for affordable options. The region is expected to benefit from government efforts to modernize healthcare services and partnerships with global manufacturers to expand product availability and patient outreach.
Middle East and Africa
The Middle East and Africa accounted for 7% of the global orthopedic support systems market in 2024. Growth is driven by the rising prevalence of orthopedic conditions, particularly in countries with expanding healthcare infrastructure such as the United Arab Emirates, Saudi Arabia, and South Africa. Demand is also supported by higher incidences of trauma injuries and an increasing focus on post-operative rehabilitation. Limited awareness and affordability issues remain challenges, particularly in lower-income parts of Africa. However, the region is witnessing gradual adoption of orthopedic support systems due to urbanization, improved hospital facilities, and growing investments in healthcare.
Market Segmentations:
By Product Type:
- Braces
- Splints
- Supports
- Cast Systems
- Orthotic Devices
By Material:
- Plastic
- Foam
- Metal
- Composite Materials
- Fabric
By Application:
- Rehabilitation
- Preventive Care
- Post-operative Care
- Sports Medicine
By Geography:
North America- U.S.
- Canada
- Mexico
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Rest of Europe
- China
- Japan
- South Korea
- India
- Australia
- Southeast Asia
- Rest of Asia Pacific
- Brazil
- Argentina
- Rest of Latin America
- GCC Countries
- Israel
- Turkey
- Rest of Middle East
- South Africa
- Egypt
- Rest of Africa
Competitive Landscape
The orthopedic support systems market is shaped by leading players such as Otto Bock, Stryker Corporation, DJO Global, B. Braun Melsungen, Tynor Orthotics, Zimmer Biomet, DePuy Synthes, Kinetec, Orthofix International, Smith Nephew, Medtronic, Hanger Inc, United Orthopedic Corporation, and Acelity. These companies collectively drive growth through continuous innovation, product diversification, and expansion into emerging regions. The market is highly competitive, with firms focusing on advanced materials, ergonomic designs, and smart technologies to improve patient outcomes. Strategic collaborations, acquisitions, and distribution partnerships strengthen global presence and enhance supply chains. Rising demand for customized and preventive orthopedic solutions encourages investment in research and development. Many players are expanding their product portfolios to target rehabilitation, preventive care, and sports medicine applications. Regional expansions, cost-effective product lines, and focus on digital platforms also play a key role in market positioning. The competitive landscape remains dynamic, with innovation and affordability serving as critical differentiators.
Key Player Analysis
- Otto Bock
- Stryker Corporation
- DJO Global
- Braun Melsungen
- Tynor Orthotics
- Zimmer Biomet
- DePuy Synthes
- Kinetec
- Orthofix International
- Smith Nephew
- Medtronic
- Hanger Inc
- United Orthopedic Corporation
- Acelity
Recent Developments
- In 2024, Hanger Inc. Launched its "Hanger Ventures" program to invest in and support innovative orthotic and prosthetic solutions from entrepreneurs and small businesses.
- In 2023, Tynor Orthotics: Inaugurated a new manufacturing facility in Mohali, Punjab, India. The new plant, equipped with advanced technology like ultrasonic welding and robotic systems, positions Tynor as a frontrunner in orthopedic appliance manufacturing.
- In 2023, DePuy Synthes (a Johnson & Johnson company) launched the VELYS Robotic-Assisted Solution in Europe.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Material, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will expand steadily, supported by rising orthopedic surgeries worldwide.
- Growing aging populations will drive long-term demand for braces and supports.
- Sports-related injuries will continue boosting adoption of preventive and corrective devices.
- Technological innovation in lightweight materials will improve patient comfort and compliance.
- 3D printing will enable personalized orthotic solutions tailored to individual patient needs.
- Smart sensor integration will support real-time monitoring in rehabilitation and homecare.
- Preventive care awareness will encourage adoption of supports in non-clinical settings.
- Emerging markets will experience faster growth due to expanding healthcare infrastructure.
- Partnerships between global players and local distributors will strengthen regional penetration.
- Digital retail channels will enhance accessibility of orthopedic support products to wider consumers.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence of Musculoskeletal Disorders
Increasing cases of arthritis, osteoporosis, and joint injuries, especially among aging populations, are driving demand for orthopedic support systems as effective non-invasive solutions for pain management and mobility support.
Expanding Sports and Fitness Activities
Greater participation in sports and recreational activities has led to higher injury rates, fueling the adoption of braces, supports, and splints for both preventive and corrective care among athletes and active individuals.
Technological Advancements in Orthopedic Devices
Innovations in material science, such as advanced plastics and composites, along with the integration of 3D printing and smart sensors, are enabling more comfortable, customizable, and effective orthopedic support systems, accelerating market growth.
Growing Focus on Preventive Care
Rising health awareness is increasing the use of orthopedic supports in daily and workplace settings to prevent musculoskeletal stress and injuries, expanding the market beyond traditional rehabilitation and post-operative applications.
Improved Healthcare Infrastructure in Emerging Markets
Expanding hospital networks, increased healthcare spending, and greater accessibility to orthopedic devices in regions like Asia Pacific and Latin America are supporting faster market growth and broader adoption.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Orthopedic Support Systems Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Orthopedic Support Systems Market projected to grow between 2025 and 2032?
What are the primary factors fueling the growth of the Orthopedic Support Systems Market?
Who are the leading companies in the Orthopedic Support Systems Market?
Which region commanded the largest share of the Orthopedic Support Systems Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Material
- 1.2.1 Plastic
- 1.2.2 Foam
- 1.2.3 Metal
- 1.2.4 Composite Materials
- 1.2.5 Fabric
- 1.3 By Application
- 1.3.1 Rehabilitation
- 1.3.2 Preventive Care
- 1.3.3 Post-operative Care
- 1.3.4 Sports Medicine
- 1.4 By Product Type
- 1.4.1 Braces
- 1.4.2 Splints
- 1.4.3 Supports
- 1.4.4 Cast Systems
- 1.4.5 Orthotic Devices
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 3.61 billion → 2032: USD 6.92 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Orthopedic Support Systems Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Orthopedic Support Systems Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Orthopedic Support Systems Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Orthopedic Support Systems Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Orthopedic Support Systems Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Orthopedic Support Systems Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Orthopedic Support Systems Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Orthopedic Support Systems Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 3.61 billion → 2032: USD 6.92 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Orthopedic Support Systems Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Material - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Plastic
- 12.3.7.2 Foam
- 12.3.7.3 Metal
- 12.3.7.4 Composite Materials
- 12.3.7.5 Fabric
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Rehabilitation
- 12.4.7.2 Preventive Care
- 12.4.7.3 Post-operative Care
- 12.4.7.4 Sports Medicine
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Braces
- 12.5.7.2 Splints
- 12.5.7.3 Supports
- 12.5.7.4 Cast Systems
- 12.5.7.5 Orthotic Devices
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Orthopedic Support Systems End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Orthopedic Support Systems Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Orthopedic Support Systems Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Orthopedic Support Systems Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Otto Bock
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Stryker Corporation
- 18.4 DJO Global
- 18.5 Zimmer Biomet
- 18.6 Medtronic
- 18.7 Smith & Nephew
- 18.8 B. Braun Melsungen
- 18.9 DePuy Synthes
- 18.10 Orthofix International
- 18.11 Tynor Orthotics
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

