
Market Overview
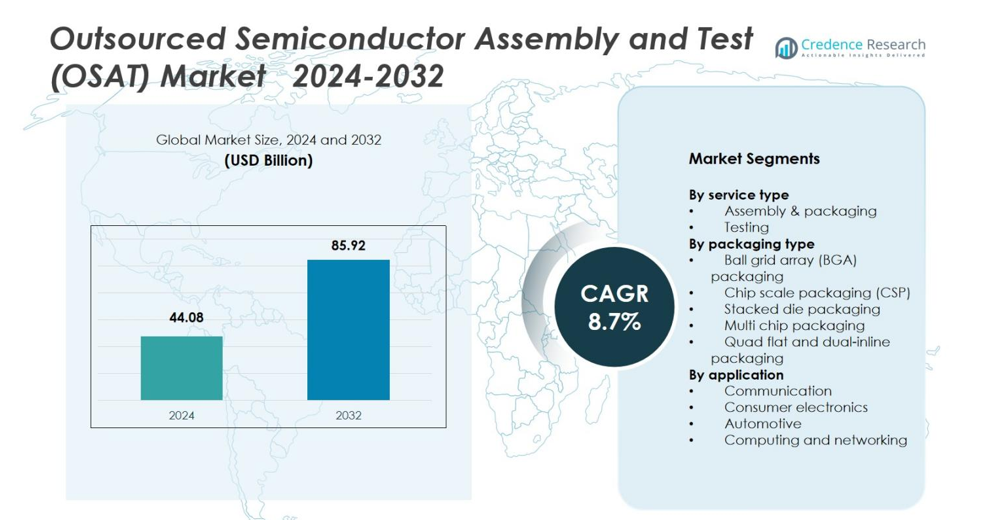
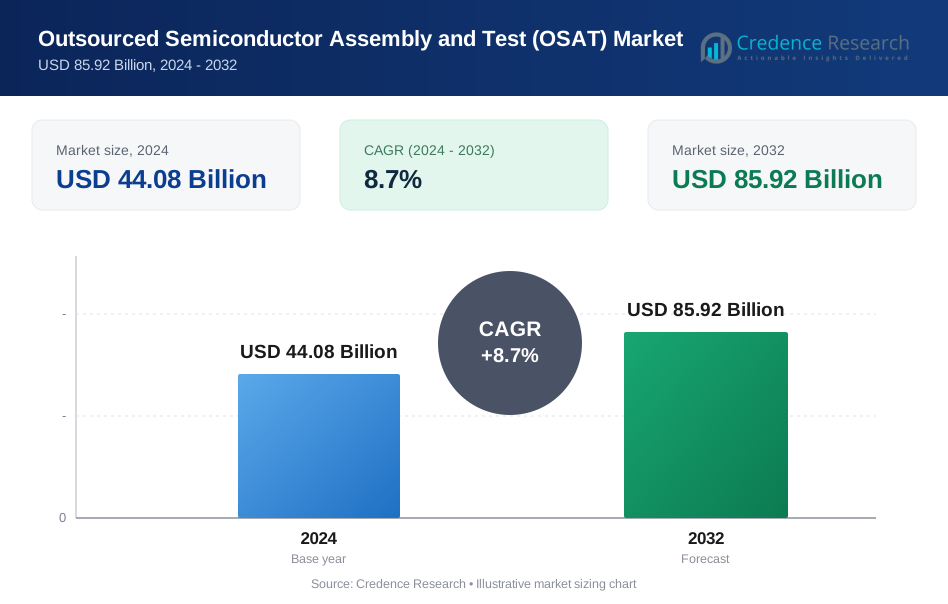
The Outsourced Semiconductor Assembly and Test (OSAT) Market size was valued at USD 44.08 Billion in 2024 and is anticipated to reach USD 85.92 Billion by 2032, at a CAGR of 8.7% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Outsourced Semiconductor Assembly and Test (OSAT) Market Size 2024 | USD 44.08 Billion |
| Outsourced Semiconductor Assembly and Test (OSAT) Market, CAGR | 8.7% |
| Outsourced Semiconductor Assembly and Test (OSAT) Market Size 2032 | USD 85.92 Billion |
The Outsourced Semiconductor Assembly and Test (OSAT) Market is dominated by key players such as ASE Technology Holding Co., Ltd., Amkor Technology, Inc., Siliconware Precision Industries Co., Ltd., JCET Group Co., Ltd., and Powertech Technology Inc. These companies lead the market by offering a wide range of assembly, packaging, and testing solutions to industries including consumer electronics, automotive, and telecommunications. In terms of regional leadership, the Asia-Pacific region holds a dominant position with a market share of 73.5% in 2024, benefiting from a well-established semiconductor manufacturing infrastructure, particularly in countries like China, Taiwan, and South Korea. North America follows with an 18% share, driven by domestic semiconductor manufacturing investments and reshoring initiatives. Europe, contributing 8%, is primarily supported by automotive and industrial electronics demand, while other regions like the Middle East, Africa, and Latin America hold a smaller share of the market.
Market Insights
- The Outsourced Semiconductor Assembly and Test (OSAT) market size stood at USD 44.08 billion in 2024 and is projected to grow at a CAGR of 8.7%.
- Asia‑Pacific leads the market with a 73.5% share in 2024, supported by robust semiconductor manufacturing ecosystems in China, Taiwan, and South Korea; the assembly & packaging service type holds 58.6% of total share, driven by demand for compact, high‑performance chips.
- Rising demand for consumer electronics and the global rollout of 5G technology accelerate adoption of advanced packaging and testing services, boosting OSAT volumes.
- Growing automotive semiconductor content - especially for EVs and ADAS - expands the need for reliable OSAT services tailored to automotive-grade quality standards.
- Major OSAT players, including ASE Technology, Amkor, and JCET, dominate the market, focusing on advanced packaging, quality, and global expansion.
Market Segmentation Analysis:
By Service Type
The Outsourced Semiconductor Assembly and Test (OSAT) market is primarily segmented by service type into assembly & packaging and testing. In 2024, the assembly & packaging segment dominates the market, accounting for 58.6% of the total market share. This segment is driven by the increasing demand for miniaturized and high-performance semiconductors, particularly in consumer electronics and automotive applications. The growth in 5G technology and the rising need for advanced packaging solutions further contribute to the segment's dominance. Testing services hold the remaining 41.4% market share and are driven by the need for quality assurance in complex semiconductor products.
- For instance, ASE Technology has developed advanced fan-out wafer-level packaging that enhances performance and reduces size for mobile devices.
By Packaging Type
In terms of packaging type, the Ball Grid Array (BGA) packaging segment leads the OSAT market with a share of 34.2% in 2024. BGA's dominance is attributed to its ability to handle high-performance and complex semiconductor devices, especially in the consumer electronics and automotive industries. Chip Scale Packaging (CSP) follows with a 27.3% share, offering compact size and high efficiency, driving its growth in mobile devices and wearables. Stacked Die and Multi-Chip Packaging, with shares of 16.8% and 12.5% respectively, are growing due to the rising demand for memory chips and multi-functional semiconductors.
- For instance, Samsung’s stacked die technology in their V-NAND memory products exemplifies this trend, enabling higher storage capacity and faster performance.
By Application
The application segment of the OSAT market is led by consumer electronics, commanding 41.5% of the market share in 2024. This is due to the escalating demand for advanced semiconductor components in smartphones, wearables, and other connected devices. The automotive sector holds the second-largest share at 28.9%, driven by the integration of semiconductors in electric vehicles, autonomous driving, and infotainment systems. Communication applications account for 19.4%, with growth fueled by the rollout of 5G infrastructure. Lastly, the computing and networking sector makes up 10.2% of the market, benefiting from the increasing adoption of cloud computing and data centers.
Key Growth Drivers
Increasing Demand for Miniaturized Electronics
The growing demand for miniaturized, high-performance electronic devices is a major driver of the Outsourced Semiconductor Assembly and Test (OSAT) market. As consumer electronics, including smartphones, wearables, and IoT devices, become more compact and powerful, the need for advanced semiconductor packaging and testing services escalates. OSAT providers are increasingly focused on developing smaller, more efficient packaging solutions that can handle the complex functionalities required in these devices. This trend is set to continue as the electronics industry drives further innovation in form factor and performance.
- For instance, ROHM's PMIC BD868A0MUF-C, a 3.5x3.5 mm chip that integrates all required power supplies, meeting strict safety and automotive standards, showcasing advanced miniaturization in power management components.
Expansion of 5G Technology
The rollout of 5G networks globally is a significant growth driver for the OSAT market. 5G technology demands high-performance, low-latency chips that require advanced packaging and testing to ensure optimal functionality. OSAT providers are addressing these needs by enhancing their services to support the production of 5G-enabled semiconductors. The increase in 5G infrastructure, coupled with the demand for 5G-enabled consumer electronics and automotive applications, is expected to propel the OSAT market, as companies seek to ensure reliable performance and quality in their semiconductor products.
- For instance, companies like Amkor have opened new facilities in Vietnam to provide advanced packaging solutions specifically for high-performance computing and automotive sectors, which benefit from 5G connectivity.
Automotive Electronics Growth
The increasing integration of electronics in automotive applications, particularly in electric vehicles (EVs) and autonomous driving systems, is driving growth in the OSAT market. Advanced semiconductors are crucial for enabling functions such as infotainment, driver assistance systems, and battery management. The growing trend toward electrification and autonomous vehicles demands specialized packaging and testing services for automotive-grade chips. As automotive manufacturers adopt more sophisticated semiconductor technologies, OSAT providers are positioned to capture a significant share of this expanding market.
Key Trends & Opportunities
Adoption of Advanced Packaging Solutions
One of the key trends in the OSAT market is the rising adoption of advanced packaging technologies such as 3D stacking, system-in-package (SiP), and chip-on-chip (CoC) solutions. These packaging techniques allow for higher functionality in smaller footprints, catering to the needs of industries like consumer electronics, telecommunications, and automotive. As devices become more complex and demand higher processing power, advanced packaging solutions present an opportunity for OSAT providers to offer differentiated services, gaining a competitive edge while meeting the evolving needs of end users.
- For instance, Freescale’s fan-out wafer-level packaging (FO-WLP) has facilitated novel SiP solutions that significantly reduce package size and improve system performance by shortening signal traces compared to traditional packaging methods.
Shift Towards Outsourcing by Semiconductor Companies
Another significant opportunity in the OSAT market is the shift towards outsourcing by semiconductor companies. As semiconductor manufacturing becomes increasingly capital-intensive, many companies are turning to third-party OSAT providers to handle assembly, testing, and packaging. This trend is especially prevalent among fabless semiconductor companies that focus on design and rely on OSAT providers for production. This outsourcing trend presents growth potential for OSAT companies as they expand their service offerings and cater to the increasing demand from global semiconductor designers.
- For instance, fabless semiconductor companies like MediaTek outsource packaging and testing to OSAT providers to focus on chip design and increase efficiency.
Key Challenges
Complexity in Meeting High-Quality Standards
One of the key challenges faced by OSAT providers is the increasing complexity in meeting the high-quality standards required by industries like automotive, healthcare, and consumer electronics. These sectors demand highly reliable and durable semiconductor products, especially as devices become more sophisticated. OSAT providers must invest in state-of-the-art testing and inspection technologies to meet stringent quality control standards. Failing to ensure consistent quality can result in product failures, damaging the reputation of both the OSAT provider and their clients.
Pressure on Profit Margins Due to Cost Competition
The OSAT market faces significant pressure on profit margins due to intense cost competition. As semiconductor companies strive to reduce manufacturing costs, OSAT providers are often forced to lower their prices to remain competitive. This is particularly challenging for smaller OSAT companies with limited economies of scale. The increasing complexity of semiconductor packaging and testing processes, coupled with the need for continuous investment in new technologies, further strains profitability. OSAT providers must focus on operational efficiencies and innovation to maintain margins while staying competitive in the global market.
Regional Analysis
Asia‑Pacific
The Asia‑Pacific region dominates the OSAT market, accounting for 73.5% of the global revenue in 2024. This region's leadership is driven by a well-established semiconductor manufacturing ecosystem, particularly in countries like China, Taiwan, South Korea, and Japan. Strong demand from industries such as consumer electronics, automotive, and telecommunications, along with robust foundry‑OSAT linkages, reinforce this dominance. The region benefits from economies of scale, a mature supply chain, and proximity to major chip design houses, securing Asia‑Pacific’s continued position as the global OSAT hub.
North America
North America holds 18% of the OSAT market share in 2024 and is expected to experience significant growth over the coming years. This growth is fueled by increased investments in domestic semiconductor manufacturing, rising demand from high-performance computing, AI, automotive, and defense sectors, and efforts to diversify supply chains. Government incentives and reshoring initiatives are boosting demand for advanced packaging and testing services locally. As semiconductor design houses seek secure, regionally-based supply chains, North America’s OSAT market is positioned for accelerated expansion.
Europe
Europe contributes 8% of the global OSAT market in 2024. The demand in the region is driven by its strong automotive and industrial electronics sectors, which require reliable and high-quality semiconductor packaging and testing services. However, Europe's OSAT market is smaller compared to Asia‑Pacific, due to less concentrated semiconductor manufacturing ecosystems. While recent efforts to bolster regional packaging and testing capabilities are underway, Europe’s OSAT market remains secondary, with the region focusing on meeting the needs of its established industries while facing increasing competition from other regions.
Middle East & Africa (MEA) and Latin America / Rest of World (ROW)
The combined share of the Middle East & Africa (MEA) and Latin America / Rest of World (ROW) in the OSAT market is 8% in 2024. These regions are currently underdeveloped in terms of large-scale semiconductor manufacturing infrastructure, limiting the demand for OSAT services. However, as industrialization policies evolve and electronics manufacturing expands, these regions present future growth opportunities. With the ongoing trend of global supply chain diversification, MEA and ROW are expected to gradually attract OSAT capacity expansions, although their market share remains relatively small in the near term.
Market Segmentations:
By service type
- Assembly & packaging
- Testing
By packaging type
- Ball grid array (BGA) packaging
- Chip scale packaging (CSP)
- Stacked die packaging
- Multi chip packaging
- Quad flat and dual-inline packaging
By application
- Communication
- Consumer electronics
- Automotive
- Computing and networking
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Outsourced Semiconductor Assembly and Test (OSAT) market is highly competitive, with key players including ASE Technology Holding Co., Ltd., Amkor Technology, Inc., Siliconware Precision Industries Co., Ltd., JCET Group Co., Ltd., and Powertech Technology Inc. These companies dominate the market by providing comprehensive assembly, packaging, and testing solutions across various semiconductor applications, including consumer electronics, automotive, and telecommunications. The market is characterized by intense competition due to the increasing demand for advanced semiconductor technologies, requiring continuous innovation in packaging solutions and testing capabilities. Leading players focus on expanding their service offerings, investing in new technologies such as 3D stacking, system-in-package (SiP), and advanced ball grid array (BGA) solutions. Additionally, strategic partnerships, mergers, and acquisitions are common, enabling companies to strengthen their capabilities and geographical reach. As the OSAT industry grows, companies are also concentrating on expanding their presence in emerging markets, ensuring long-term sustainability and market share growth.
Key Player Analysis
- ChipMOS Technologies Inc.
- Powertech Technology Inc.
- ASE Technology Holding Co., Ltd.
- Amkor Technology, Inc.
- Tianshui Huatian Technology Co., Ltd.
- STATS ChipPAC Pte. Ltd.
- Siliconware Precision Industries Co., Ltd.
- JCET Group Co., Ltd.
- Chipbond Technology Corporation
- Tongfu Microelectronics Co., Ltd.
Recent Developments
- In August 2025, CG Semi launched a full-service OSAT pilot line facility in Sanand, Gujarat, marking one of India’s first end-to-end OSAT offerings.
- In September 2025, Kaynes Semicon entered into an equity-linked collaboration with UST Technology International (UST), agreeing to issue convertible preference shares a move that supports Kaynes’ plan to establish an OSAT plant in Sanand, Gujarat.
- In November 2025, Aehr Test Systems announced a strategic partnership with ISE Labs (a subsidiary of ASE, Inc.) to deliver advanced wafer-level test and burn-in services tailored for high-performance computing (HPC) and AI processors a development relevant to the OSAT ecosystem.
Report Coverage
The research report offers an in-depth analysis based on Service Type, Packaging Type, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The OSAT market is expected to experience significant growth due to the increasing demand for miniaturized, high-performance semiconductor devices across various industries.
- Advancements in 5G technology will drive further growth as the demand for high-performance semiconductor packaging and testing solutions increases.
- The automotive sector will continue to be a key growth driver, particularly with the rise of electric vehicles and autonomous driving technologies.
- The adoption of advanced packaging technologies, such as 3D stacking and system-in-package (SiP), will continue to shape the market, enabling higher functionality in smaller form factors.
- North America is likely to see accelerated OSAT market growth driven by reshoring initiatives and increased domestic semiconductor production.
- Emerging markets, particularly in Asia-Pacific and Latin America, will present new opportunities for OSAT providers due to growing semiconductor demand in these regions.
- Increasing integration of AI and IoT technologies in consumer electronics will create greater demand for advanced semiconductor testing and packaging services.
- Companies are expected to invest more in research and development to support innovation in packaging solutions, improving performance and cost-efficiency.
- Environmental sustainability will play an increasingly important role, with OSAT providers focusing on energy-efficient and eco-friendly packaging solutions.
- Strategic partnerships, mergers, and acquisitions will be crucial for OSAT companies to enhance their technological capabilities and expand their market reach.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Miniaturization of Electronics
The push for smaller, more powerful consumer electronics and IoT devices is driving demand for advanced semiconductor packaging and testing services, as manufacturers require compact, high-performance chips with complex functionalities.
Expansion of 5G Technology
The global rollout of 5G networks necessitates high-performance, low-latency chips, increasing the need for sophisticated OSAT services to ensure optimal performance and reliability in 5G-enabled devices and infrastructure.
Growth in Automotive Electronics
The rising integration of semiconductors in electric vehicles, autonomous driving systems, and automotive infotainment is expanding the need for automotive-grade OSAT services that meet stringent quality and reliability standards.
Adoption of Advanced Packaging Solutions
Technological advancements such as 3D stacking, system-in-package (SiP), and fan-out wafer-level packaging are enabling higher functionality in smaller footprints, prompting OSAT providers to innovate and capture new market opportunities.
Shift Toward Outsourcing by Semiconductor Companies
As semiconductor manufacturing becomes more capital-intensive, fabless and integrated device manufacturers are increasingly outsourcing assembly and testing to OSAT providers, fueling market growth and expanding the customer base for specialized OSAT services.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Outsourced Semiconductor Assembly and Test (OSAT) Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Outsourced Semiconductor Assembly and Test (OSAT) Market projected to grow between 2025 and 2032?
Which Outsourced Semiconductor Assembly and Test (OSAT) Market segment held the largest share in 2024?
Which region commanded the largest share of the Outsourced Semiconductor Assembly and Test (OSAT) Market in 2024?
Who are the leading companies in the Outsourced Semiconductor Assembly and Test (OSAT) Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Application
- 1.2.1 Consumer electronics
- 1.2.2 Automotive
- 1.2.3 Communication
- 1.2.4 Computing and networking
- 1.3 By Service Type
- 1.3.1 Assembly & packaging
- 1.3.2 Testing
- 1.4 By Packaging Type
- 1.4.1 Ball grid array (BGA) packaging
- 1.4.2 Chip scale packaging (CSP)
- 1.4.3 Stacked die packaging
- 1.4.4 Multi chip packaging
- 1.4.5 Quad flat and dual-inline packaging
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 44.08 Billion → 2032: USD 85.92 Billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Outsourced Semiconductor Assembly and Test (OSAT) Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Outsourced Semiconductor Assembly and Test (OSAT) Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Outsourced Semiconductor Assembly and Test (OSAT) Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Outsourced Semiconductor Assembly and Test (OSAT) Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Outsourced Semiconductor Assembly and Test (OSAT) Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Outsourced Semiconductor Assembly and Test (OSAT) Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Outsourced Semiconductor Assembly and Test (OSAT) Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Outsourced Semiconductor Assembly and Test (OSAT) Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 44.08 Billion → 2032: USD 85.92 Billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Outsourced Semiconductor Assembly and Test (OSAT) Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Application - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Consumer electronics
- 12.3.7.2 Automotive
- 12.3.7.3 Communication
- 12.3.7.4 Computing and networking
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Service Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Assembly & packaging
- 12.4.7.2 Testing
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Packaging Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Ball grid array (BGA) packaging
- 12.5.7.2 Chip scale packaging (CSP)
- 12.5.7.3 Stacked die packaging
- 12.5.7.4 Multi chip packaging
- 12.5.7.5 Quad flat and dual-inline packaging
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Outsourced Semiconductor Assembly and Test (OSAT) End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Outsourced Semiconductor Assembly and Test (OSAT) Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Outsourced Semiconductor Assembly and Test (OSAT) Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Outsourced Semiconductor Assembly and Test (OSAT) Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 ASE Technology Holding Co., Ltd.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Amkor Technology, Inc.
- 18.4 Siliconware Precision Industries Co., Ltd.
- 18.5 JCET Group Co., Ltd.
- 18.6 Powertech Technology Inc.
- 18.7 ChipMOS Technologies Inc.
- 18.8 Tianshui Huatian Technology Co., Ltd.
- 18.9 STATS ChipPAC Pte. Ltd.
- 18.10 Chipbond Technology Corporation
- 18.11 Tongfu Microelectronics Co., Ltd.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

