
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Percutaneous Coronary Intervention (PCI) Devices Market Size 2024 | USD 8,289.5 Million |
| Percutaneous Coronary Intervention (PCI) Devices Market, CAGR | 5.40% |
| Percutaneous Coronary Intervention (PCI) Devices Market Size 2032 | USD 12,625.63 Million |
Market Overview
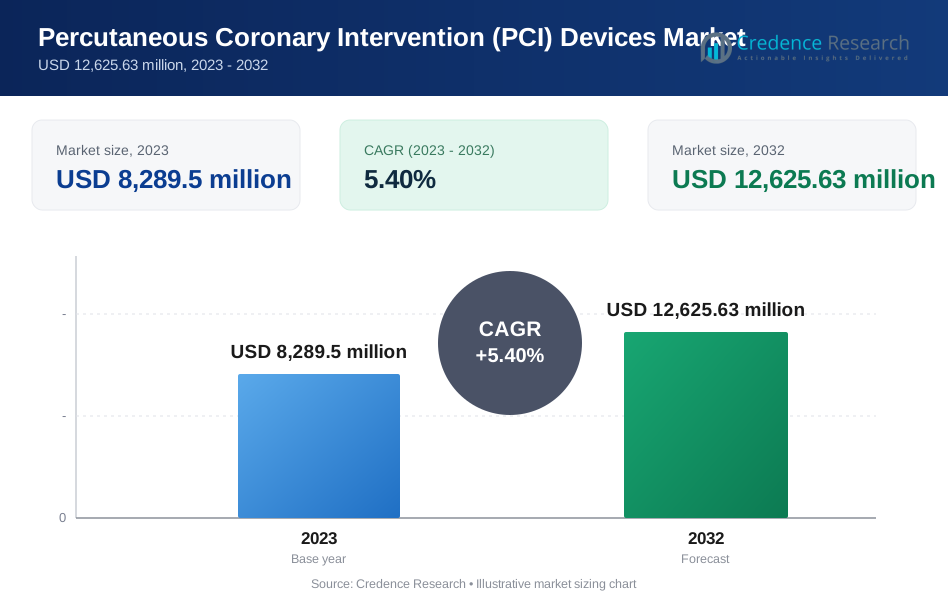
The Percutaneous Coronary Intervention (PCI) Devices Market is projected to grow from USD 8,289.5 million in 2023 to an estimated USD 12,625.63 million by 2032, with a compound annual growth rate (CAGR) of 5.40% from 2024 to 2032. This growth can be attributed to the rising prevalence of cardiovascular diseases globally, which is driving the demand for minimally invasive procedures like PCI.
Key market drivers include the rising incidence of lifestyle-related health issues, such as obesity and diabetes, which contribute to coronary artery disease. In response, the healthcare sector is increasingly adopting PCI as a preferred treatment option due to its efficiency and reduced recovery time. Emerging trends in this market include a growing focus on developing innovative and biocompatible devices, such as advanced balloon catheters and atherectomy devices, to improve patient outcomes and minimize procedure-related risks.
Geographically, North America currently holds a significant share of the PCI devices market, driven by high healthcare spending and a strong presence of major medical device companies. However, the Asia-Pacific region is anticipated to experience the fastest growth over the forecast period, fueled by rising healthcare investments, a growing patient pool, and increasing awareness of PCI procedures. Leading players in this market include Abbott Laboratories, Medtronic plc, Boston Scientific Corporation, and Terumo Corporation, all of which continuously strive to enhance their product offerings and strengthen their global footprint.
Market Drivers
Rising Incidence of Cardiovascular Diseases
The growing prevalence of cardiovascular diseases (CVDs), such as coronary artery disease (CAD), remains a primary driver for the PCI devices market. CVDs are among the leading causes of mortality worldwide, claiming millions of lives each year. As urbanization and sedentary lifestyles continue to spread globally, more people are adopting habits that elevate risk factors associated with cardiovascular diseases, including high blood pressure, obesity, and smoking. These lifestyle factors, coupled with an aging population, are anticipated to further drive the demand for PCI procedures. Consequently, healthcare providers increasingly turn to PCI devices to offer minimally invasive solutions that efficiently restore blood flow in blocked coronary arteries. For instance, cardiovascular diseases accounted for 20.5 million deaths globally in 2021, which is close to a third of all deaths worldwide. The continuous rise in CVD incidence underscores the critical need for PCI devices, which are pivotal in treating patients with coronary artery blockages and reducing associated morbidity and mortality rates.
Technological Advancements in PCI Devices
The PCI devices market has benefited substantially from rapid technological advancements that improve the precision, safety, and outcomes of procedures. Innovations in stent technology, such as drug-eluting stents (DES) and bioresorbable vascular scaffolds, have revolutionized PCI by reducing the risk of restenosis and allowing for more effective treatments. For instance, recent advances include the use of bioresorbable vascular scaffolds for coronary stenting and advanced 3D imaging for complex coronary and structural disease. Additionally, the development of atherectomy devices, which remove plaque from artery walls, has expanded the applicability of PCI to patients with complex or calcified lesions. Enhanced imaging and navigation systems, including optical coherence tomography (OCT) and intravascular ultrasound (IVUS), are now routinely integrated into PCI procedures, offering real-time visualization and detailed assessments that allow physicians to perform more accurate interventions. These technological advancements in PCI devices have boosted the confidence of healthcare professionals in using these tools, thereby driving greater adoption rates and fueling market growth.
Increased Preference for Minimally Invasive Procedures
As healthcare continues to prioritize patient-centered approaches, minimally invasive techniques like PCI have gained substantial traction. Traditional coronary artery bypass grafting (CABG) surgery, while effective, is invasive and requires extended recovery times, which can be challenging for patients. PCI, in contrast, offers shorter procedure times, reduced hospital stays, and quicker recovery periods, making it a more attractive option for both patients and healthcare providers. The market for PCI devices is bolstered by the growing demand for minimally invasive procedures, as they are associated with fewer complications, lower healthcare costs, and enhanced patient comfort. For instance, a study found that 76% of patients preferred minimally invasive surgery (MIS) over traditional surgery due to shorter recovery times and fewer complications. Furthermore, as patients become more informed and active in healthcare decision-making, they increasingly prefer options that minimize disruption to their lives. The favorable patient outcomes and improved quality of life offered by PCI have become significant factors in the growing preference for minimally invasive techniques over traditional surgical methods.
Expanding Healthcare Infrastructure and Growing Investments in Emerging Markets
Emerging markets, particularly in regions like Asia-Pacific and Latin America, are experiencing substantial growth in healthcare infrastructure. This expansion is driven by increasing investments from both governmental and private sectors aiming to improve access to advanced medical treatments. These regions have a high prevalence of cardiovascular diseases and an increasing demand for better healthcare services, positioning them as key growth areas for the PCI devices market. Governments in these areas are investing heavily in healthcare facilities, medical training, and technology adoption to address the rising healthcare needs of their populations. Moreover, global medical device manufacturers are actively seeking to establish a strong presence in these regions, recognizing the potential for significant market penetration. This expanding healthcare infrastructure, coupled with rising awareness of cardiovascular health and access to modern medical technologies, is set to drive further adoption of PCI devices across these emerging markets. By making PCI procedures more accessible, these investments will continue to propel the global PCI devices market forward.
Market Trends
Adoption of Advanced Imaging and Navigation Technologies
The PCI devices market is witnessing a growing trend towards incorporating advanced imaging and navigation technologies, such as optical coherence tomography (OCT) and intravascular ultrasound (IVUS), into PCI procedures. These tools provide real-time, high-resolution imaging of the coronary arteries, which enhances physicians’ ability to accurately assess blockages and position devices like stents with greater precision. OCT, in particular, is gaining popularity due to its capability to deliver highly detailed cross-sectional images, enabling better visualization of arterial walls and plaque composition. For instance, a study found that the use of intravascular imaging during PCI procedures can reduce the risk of major adverse cardiac events by 38% compared to angiography-guided PCI. This trend is being driven by the need for more accurate and effective interventions, especially in patients with complex lesions or calcified arteries. Moreover, integrating these advanced imaging modalities into PCI procedures has been shown to improve patient outcomes by reducing the risk of complications, such as stent malposition and restenosis. With increasing awareness of these benefits, healthcare providers are increasingly adopting these technologies to ensure high-quality care and optimal procedural success rates, further propelling the growth of the PCI devices market.
Rise in Demand for Bioabsorbable and Drug-Eluting Stents
The market is also seeing a significant shift towards bioabsorbable and drug-eluting stents, reflecting an ongoing trend towards improving long-term patient outcomes and reducing complications associated with traditional stents. Drug-eluting stents (DES) release medication over time to prevent the growth of scar tissue, thereby reducing the risk of restenosis-a common issue with bare-metal stents. Meanwhile, bioabsorbable stents are designed to naturally dissolve within the body over time, allowing the treated artery to regain its natural flexibility. This trend aligns with the increasing preference for innovative, biocompatible devices that address post-procedure concerns and enhance patient recovery. With several bioabsorbable stents currently undergoing clinical trials and some already approved for use in select markets, they represent a promising future direction for PCI treatments. As healthcare providers continue to prioritize patient safety and treatment efficacy, the demand for these advanced stent options is expected to grow, reinforcing their role as key components in the PCI devices market and driving further innovation and development in the field.
Market Restraints and Challenges
High Costs and Reimbursement Issues
One of the primary challenges facing the PCI devices market is the high cost associated with PCI procedures and the devices themselves, which include drug-eluting stents, advanced imaging tools, and bioabsorbable stents. These devices are often expensive due to the research and development costs required to ensure their safety, efficacy, and regulatory compliance. Additionally, hospitals and healthcare facilities may need to invest in specialized training for staff to properly utilize these devices and advanced imaging systems, further adding to the overall cost. In many regions, reimbursement policies for PCI procedures do not fully cover these expenses, particularly in emerging markets where healthcare systems are still developing. This can limit accessibility for patients and result in financial strain on healthcare providers, thereby restricting market growth. Consequently, manufacturers face the challenge of balancing innovation with cost-effective production to make PCI devices more affordable and accessible to a broader patient base.
Regulatory Hurdles and Product Recalls
Stringent regulatory requirements and the potential for product recalls present significant challenges in the PCI devices market. Due to the critical nature of PCI procedures, devices used in these interventions are subject to rigorous regulatory scrutiny to ensure patient safety and device effectiveness. Obtaining approval from regulatory bodies such as the U.S. Food and Drug Administration (FDA) and the European Medicines Agency (EMA) often requires extensive clinical trials and substantial investment, which can delay product launches and increase costs for manufacturers. Furthermore, product recalls due to safety concerns or device malfunctions can severely impact a company’s reputation and financial performance. Recalls can lead to decreased market confidence and prompt stricter regulatory oversight, thereby slowing down the overall pace of innovation in the market. As a result, companies in the PCI devices market must continually invest in quality control, post-market surveillance, and compliance initiatives to mitigate these challenges and maintain their competitive edge.
Market Segmentation Analysis
By Product
The PCI devices market comprises several key product segments, each playing a vital role in enhancing the efficacy and safety of procedures. Coronary catheters are central to PCI, guiding and delivering other devices, such as balloons and stents, with advancements in flexibility and miniaturization driving growth, especially for complex cases like chronic total occlusions. Coronary guidewires are crucial for precise device placement and are increasingly sought after due to enhanced features like hydrophilic coatings and shape-memory capabilities, which improve navigation through challenging coronary anatomy. Coronary stents-the largest segment, including drug-eluting, bare-metal, and bioabsorbable stents-continue to evolve, with DES leading the market by effectively reducing restenosis rates, while bioabsorbable stents gain traction for their ability to restore arterial flexibility over time. Lastly, accessories such as inflation devices, embolic protection devices, and introducer sheaths, though less prominent, play a supporting role that boosts procedural efficiency and safety, driven by rising PCI procedure volumes and the demand for comprehensive interventional solutions.
By End Use
Hospitals, as the primary end-users of PCI devices, account for a substantial share of the market due to their capacity to manage high patient volumes and provide comprehensive care. Hospitals worldwide are increasingly investing in PCI technology, driven by the rising prevalence of cardiovascular diseases and expanding healthcare infrastructure, particularly in emerging markets. Ambulatory Surgical Centers (ASCs) are also adopting PCI devices, offering a cost-effective, convenient setting for elective procedures where shorter recovery times are essential. ASCs cater to patients who do not require extended hospital stays, aligning with the healthcare industry's emphasis on cost-efficiency and patient convenience. Additionally, catheterization labs, both within hospitals and as independent facilities, are specialized for diagnostic and interventional cardiology procedures. These labs are equipped with advanced technology and skilled professionals, making them ideal for PCI. As public and private sector investments in cath labs increase globally, the demand for PCI devices in this segment is expected to grow, significantly contributing to overall market expansion.
Segments
Based on Product
- Coronary Catheters
- Coronary Guidewires
- Coronary Stents
- Accessories
Based on End Use
- Hospitals
- Ambulatory Surgical Centers
- Catherization Labs
Based on Region
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
Regional Analysis
North America (35%):
North America dominates the PCI devices market, accounting for approximately 35% of the global market share. This leadership is primarily driven by a well-established healthcare infrastructure, high healthcare spending, and a significant prevalence of cardiovascular diseases. The U.S. and Canada are key contributors, with the U.S. at the forefront due to a large aging population and the presence of major industry players such as Abbott Laboratories, Medtronic plc, and Boston Scientific Corporation. Additionally, strong reimbursement policies and increasing adoption of advanced PCI technologies, including drug-eluting stents and bioabsorbable scaffolds, further bolster North America's market position. The region continues to witness growth as healthcare providers adopt the latest innovations to improve patient outcomes.
Europe (28%):
Europe holds the second-largest market share, contributing around 28% to the global PCI devices market. The demand in this region is fueled by the high prevalence of cardiovascular diseases, particularly in countries like Germany, France, and the U.K. Favorable regulatory frameworks, combined with substantial investments in healthcare infrastructure, support the adoption of PCI devices across the region. European healthcare systems have also prioritized minimally invasive procedures, enhancing patient recovery and reducing costs. Additionally, initiatives by the European Union to raise awareness of heart disease prevention have positively impacted PCI device adoption. With ongoing advancements in PCI technologies and an aging population, Europe remains a key market for PCI devices.
Key players
- Abbott
- Braun
- ASAHI INTECC Company Limited
- Biosensors International Group, Ltd
- Boston Scientific Corporation
- R. Bard
- BIOTRONIK
- Comed BV
- Cook
- Meril Lifesciences
- Cordis
- Medtronic PLC
- Merit Medical System
- Terumo Corporation
Competitive Analysis
The Percutaneous Coronary Intervention (PCI) Devices Market is highly competitive, with several major players actively investing in research and development to enhance their product portfolios. Companies like Abbott, Boston Scientific Corporation, and Medtronic PLC lead the market due to their extensive product offerings and strong global presence. These companies consistently focus on technological advancements, such as drug-eluting and bioabsorbable stents, to improve patient outcomes and maintain competitive advantage. Terumo Corporation and ASAHI INTECC Company Limited have gained traction in the market through innovations in guidewires and catheters, catering to the rising demand for minimally invasive procedures. Biosensors International Group and BIOTRONIK also hold notable shares due to their specialized stent technologies. As companies continue to expand geographically and develop cost-effective solutions, competition is expected to intensify, driving further advancements in PCI devices.
Recent Developments
- In October 2023, Abbott’s structural heart portfolio reached new heights with the U.S. Food and Drug Administration (FDA) approval of the Amplatzer Amulet Left Atrial Appendage (LAA) Occluder and Portico with FlexNav transcatheter aortic valve replacement (TAVR) system.
- In May 2023, Biosensors International Group launched the BioFreedom Ultra, a novel thin strut CoCr polymer and carrier-free Drug Coated Stent with Biosensors’ proprietary limus BA9.
- In October 2023, Boston Scientific expects to receive FDA approval for its Agent drug-coated balloon and its Farapulse pulsed-field ablation system in 2024.
- In September 2023, Boston Scientific announced plans to buy Relievant Medsystems for $850 million, which would add a new low back pain treatment to its neuromodulation portfolio.
- In October 2023, BIOTRONIK’s Orsiro DES received approval for sale by the National Medical Products Administration in China.
Market Concentration and Characteristics
The Percutaneous Coronary Intervention (PCI) Devices Market is moderately concentrated, with a mix of prominent multinational corporations and specialized regional players. Major companies, including Abbott, Boston Scientific Corporation, and Medtronic PLC, dominate the market due to their strong brand recognition, extensive product portfolios, and continuous investment in research and development. These key players hold substantial market shares, leveraging their global reach and advanced technologies, such as drug-eluting stents and bioabsorbable scaffolds, to maintain competitive positions. However, smaller and mid-sized firms, particularly those focused on niche segments like coronary guidewires and advanced catheters, also play an essential role in regional markets, enhancing market diversity. The PCI devices market is characterized by high regulatory standards, rapid technological advancements, and a strong emphasis on quality and innovation, as companies strive to meet the growing demand for minimally invasive cardiovascular solutions.
Report Coverage
The research report offers an in-depth analysis based on Product, End Use and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for minimally invasive PCI procedures is expected to rise, driven by patients’ preferences for shorter recovery times and lower complication rates.
- As bioabsorbable stents gain regulatory approvals, they are poised to capture a larger share of the market, offering a safer, long-term alternative to traditional stents.
- The adoption of advanced imaging technologies like OCT and IVUS will continue to grow, enabling more precise diagnosis and improved procedural outcomes in PCI.
- With rising healthcare investments and increased access to cardiovascular care, emerging markets in Asia-Pacific and Latin America are expected to drive significant PCI market growth.
- Manufacturers will focus on developing cost-effective PCI devices to meet the demand in price-sensitive regions, making these devices more accessible to a broader population.
- The adoption of drug-eluting stents is projected to increase due to their efficacy in reducing restenosis, making them a preferred choice among healthcare providers.
- The incorporation of artificial intelligence and robotics is likely to enhance procedural precision, supporting improved outcomes and reducing procedure times in PCI interventions.
- The market is expected to see growth in customized PCI devices that cater to patient-specific needs, such as advanced guidewires and catheters tailored to unique anatomical challenges.
- Regulatory agencies will likely continue to enforce strict guidelines to ensure the safety and efficacy of PCI devices, pushing companies to invest more in compliance and quality assurance.
- Research and development activities will remain a priority as companies work to innovate and introduce next-generation PCI devices, enhancing performance and addressing unmet medical needs.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Incidence of Cardiovascular Diseases
The increasing prevalence of cardiovascular diseases, such as coronary artery disease, is fueling demand for PCI devices as minimally invasive interventions become essential for restoring blood flow and reducing mortality rates.
Technological Advancements in PCI Devices
Innovations such as drug-eluting stents, bioabsorbable scaffolds, and advanced imaging technologies like OCT and IVUS are improving procedural outcomes, safety, and expanding the applicability of PCI to more complex cases.
Increased Preference for Minimally Invasive Procedures
Patients and healthcare providers are increasingly opting for PCI over traditional surgery due to shorter recovery times, fewer complications, and lower overall healthcare costs, driving greater adoption of PCI devices.
Expanding Healthcare Infrastructure in Emerging Markets
Growing investments in healthcare facilities and technology in regions like Asia-Pacific and Latin America are increasing access to advanced cardiovascular treatments, boosting the uptake of PCI devices.
Shift Toward Bioabsorbable and Drug-Eluting Stents
The market is experiencing rising demand for innovative stent technologies that reduce restenosis and long-term complications, supporting sustained growth as these devices gain regulatory approvals and clinical acceptance.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the Percutaneous Coronary Intervention (PCI) Devices Market in 2023 and 2032, and what is its CAGR?
What factors are driving the growth of the PCI devices market?
Which regions are leading the PCI devices market?
How are technological advancements impacting the PCI devices market?
Who are the major players in this market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End Use
- 1.2.1 Hospitals
- 1.2.2 Ambulatory Surgical Centers
- 1.2.3 Catheterization Labs
- 1.3 By Product
- 1.3.1 Coronary Catheters
- 1.3.2 Coronary Guidewires
- 1.3.3 Coronary Stents
- 1.3.4 Accessories
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 8,289.5 million → 2032: USD 12,625.63 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Percutaneous Coronary Intervention (PCI) Devices Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Percutaneous Coronary Intervention (PCI) Devices Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Percutaneous Coronary Intervention (PCI) Devices Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Percutaneous Coronary Intervention (PCI) Devices Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Percutaneous Coronary Intervention (PCI) Devices Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Percutaneous Coronary Intervention (PCI) Devices Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Percutaneous Coronary Intervention (PCI) Devices Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Percutaneous Coronary Intervention (PCI) Devices Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 8,289.5 million → 2032: USD 12,625.63 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Percutaneous Coronary Intervention (PCI) Devices Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End Use - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hospitals
- 12.3.7.2 Ambulatory Surgical Centers
- 12.3.7.3 Catheterization Labs
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Coronary Catheters
- 12.4.7.2 Coronary Guidewires
- 12.4.7.3 Coronary Stents
- 12.4.7.4 Accessories
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Percutaneous Coronary Intervention (PCI) Devices End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Percutaneous Coronary Intervention (PCI) Devices Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Share, 2023
- 14.2 Regional Market Forecast, 2023-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Percutaneous Coronary Intervention (PCI) Devices Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Percutaneous Coronary Intervention (PCI) Devices Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Abbott
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Medtronic PLC
- 18.4 Boston Scientific Corporation
- 18.5 Terumo Corporation
- 18.6 ASAHI INTECC Company Limited
- 18.7 Biosensors International Group, Ltd
- 18.8 BIOTRONIK
- 18.9 Cordis
- 18.10 Meril Lifesciences
- 18.11 B. Braun
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

