
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Pillow Pouch Packaging Market Size 2024 | USD 8343 million |
| Pillow Pouch Packaging Market, CAGR | 6.7% |
| Pillow Pouch Packaging Market Size 2032 | USD 14016.4 million |
Market Overview:
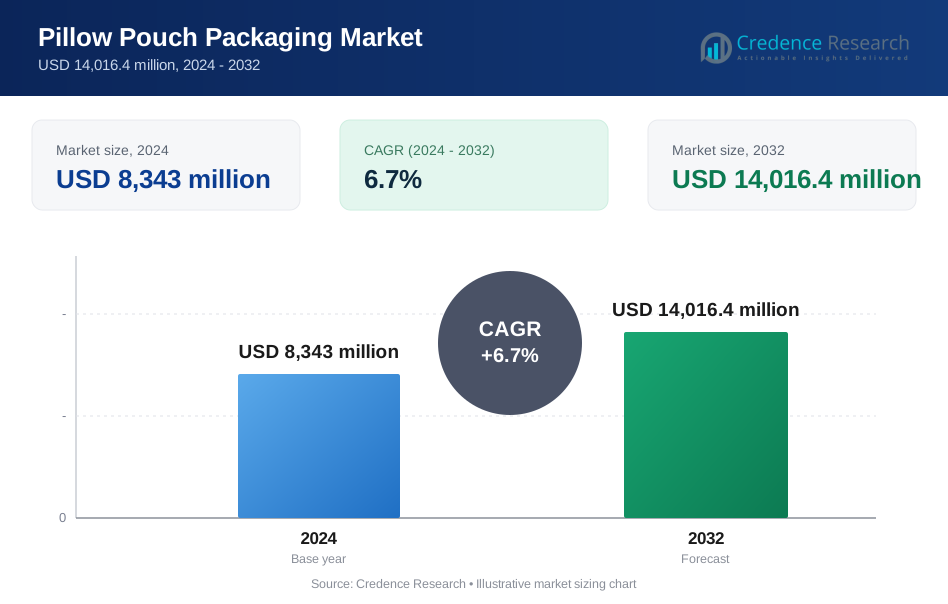
The Pillow pouch packaging market is projected to grow from USD 8343 million in 2024 to an estimated USD 14016.4 million by 2032, with a compound annual growth rate (CAGR) of 6.7% from 2024 to 2032.
Several factors are fueling the growth of the pillow pouch packaging market. Firstly, the increasing consumer preference for ready-to-eat and on-the-go products is driving demand for flexible packaging formats that are easy to open, reseal, and carry. Additionally, advancements in packaging materials and printing technologies have enabled manufacturers to develop pouches with improved barrier properties, longer shelf life, and vibrant visual designs, enhancing product differentiation and brand visibility. Sustainability has also emerged as a key driver, with a growing emphasis on reducing environmental impact through recyclable, biodegradable, and compostable film structures. Regulatory pressures across developed regions, alongside increasing awareness among consumers about eco-friendly packaging, are pushing manufacturers to innovate toward greener alternatives. Furthermore, the rapid expansion of e-commerce and organized retail is bolstering the demand for durable and efficient packaging solutions like pillow pouches, which offer both protection and aesthetic value during storage and transportation.
Regionally, Asia-Pacific dominates the global pillow pouch packaging market, driven by strong economic growth, urbanization, and increasing consumer spending in emerging countries such as China, India, Indonesia, and Vietnam. The region's booming food and beverage industry, coupled with advancements in manufacturing infrastructure, has created a fertile ground for flexible packaging innovations. North America follows closely, supported by high demand for convenient packaging formats in the food, healthcare, and personal care sectors, as well as the region’s strong emphasis on sustainability and product safety. Europe, too, represents a significant share of the market, propelled by stringent environmental regulations and growing adoption of recyclable and mono-material packaging. Meanwhile, Latin America and the Middle East & Africa are witnessing steady growth, owing to the expansion of retail networks, rising disposable incomes, and increasing demand for packaged food products. Although these regions currently account for a smaller market share, they offer substantial growth potential in the long term, especially with greater investment in packaging technology and sustainability initiatives.
Market Insights:
- The pillow pouch packaging market is projected to grow from USD 8,343 million in 2024 to approximately USD 14,016.4 million by 2032, registering a healthy CAGR of 6.7% due to rising global demand for convenient and lightweight packaging solutions.
- The increasing popularity of ready-to-eat and portable food products is driving the adoption of flexible pillow pouches that offer ease of use, resealability, and space efficiency, especially among urban consumers and busy lifestyles.
- Ongoing innovations in high-barrier films and digital printing technologies are enabling brands to offer better protection, enhanced shelf life, and visually engaging packaging, supporting both premium product positioning and operational agility.
- Sustainability remains a strong market influence, with regulatory mandates and consumer awareness accelerating the shift toward recyclable, biodegradable, and compostable pouch materials, particularly in North America and Europe.
- The rapid growth of e-commerce and omnichannel retail is increasing the need for packaging that combines durability, light weight, and visual appeal—pillow pouches meet these requirements across food, healthcare, and personal care segments.
- Recycling challenges related to multi-layered film structures pose a constraint to sustainability goals, prompting the need for material redesign and greater investment in recyclable mono-material solutions within the pillow pouch packaging market.
- Regionally, Asia-Pacific leads market growth, driven by rising consumer spending and industrial capacity in emerging economies, while North America and Europe remain key contributors due to high demand for eco-conscious and convenience-driven packaging.
Market Drivers:
Rising Demand for Convenient and Portable Packaging Solutions Across Consumer Goods:
Consumer preferences continue to shift toward products that offer ease of use, portability, and minimal waste. This trend is particularly evident in the food and beverage sector, where ready-to-eat meals, snacks, and beverages require packaging formats that are functional and user-friendly. Pillow pouch packaging meets these needs through its lightweight structure, resealability, and space-saving design. It appeals to both consumers and retailers by maximizing shelf space and enhancing on-the-go consumption. The growing pace of urban living and changing work patterns support the adoption of flexible packaging that aligns with fast-paced lifestyles. The pillow pouch packaging market benefits directly from this transformation in consumption behavior, especially in densely populated urban regions.
- For instance, Amcor’s AmLite Ultra Recyclable pillow pouch is used by over 200 food brands worldwide, reducing packaging weight by up to 64% compared to rigid packaging and supporting convenient snacking in more than 40 countries.
Technological Advancements in Film Materials and Digital Printing Capabilities:
The packaging industry is investing heavily in material innovation to improve durability, product preservation, and shelf life. Advances in high-barrier films and multilayer laminates allow pillow pouches to protect contents from moisture, oxygen, and contaminants without adding weight. Digital printing technologies enable faster turnaround times, personalized branding, and sharper graphics, which increase consumer engagement at the point of sale. These technological upgrades also reduce operational costs through shorter production runs and minimized material waste. It supports the growth of small and medium-sized brands that require flexibility in design and inventory management. The pillow pouch packaging market gains a competitive edge through these ongoing technological developments.
- For instance, ProAmpac’s ProActive Recyclable® pillow pouches are certified recyclable in more than 20 countries, and the company’s digital printing platform enables custom graphics with lead times as short as five days, allowing brands to respond rapidly to market trends.
Sustainability Pressures from Consumers and Regulatory Authorities Driving Material Innovation:
Governments and environmental organizations are imposing stricter guidelines on single-use plastics and packaging waste. In response, manufacturers are developing recyclable, compostable, and biodegradable pouch materials to reduce their environmental impact. Consumer demand for eco-conscious packaging choices is accelerating this shift, especially in North America and Europe. It compels producers to prioritize material traceability, lifecycle analysis, and end-of-life disposal solutions. Brands adopting sustainable pillow pouches often gain a competitive advantage through improved brand perception and customer loyalty. The pillow pouch packaging market is evolving rapidly to align with these environmental priorities and circular economy goals.
E-Commerce Expansion and Retail Transformation Creating New Opportunities for Flexible Packaging:
The rapid growth of e-commerce and online grocery platforms has changed the packaging landscape, placing greater emphasis on durability, product protection, and shipping efficiency. Pillow pouches offer strong resistance to handling and compression while maintaining a lightweight form, which reduces transportation costs and environmental impact. Retailers are also rethinking shelf design and packaging presentation, favoring formats that are flexible, stackable, and visually appealing. It provides an ideal solution for these evolving retail dynamics, supporting both digital and in-store product strategies. Demand is growing in tandem with omnichannel retail experiences that require packaging adaptable to multiple distribution points. The pillow pouch packaging market is positioned well to meet these diverse retail and logistics demands.
Market Trends:
Premiumization of Packaging Design to Enhance Shelf Appeal and Consumer Engagement:
Brands are increasingly turning to premium packaging formats to differentiate themselves in competitive retail environments. High-end finishes, matte textures, metallic foils, and clear windows are now being integrated into pillow pouches to elevate product perception. These visual and tactile enhancements help products stand out on shelves, especially in categories like snacks, pet food, and health supplements. Consumer behavior shows a growing willingness to pay more for products that appear to offer better quality through packaging cues. This shift is driving brands to reimagine pouch aesthetics not just for protection but as a tool for emotional and visual impact. The pillow pouch packaging market reflects this premiumization trend through expanded offerings that balance design sophistication with functionality.
- For instance, Glenroy Inc.’s TruRenu® sustainable pouch line features pillow pouches with high-clarity windows and soft-touch finishes.
Adoption of Smart Packaging Features to Improve Product Safety and Traceability:
Smart packaging is gaining traction across several industries, offering features like QR codes, tamper-evidence, and freshness indicators. These technologies provide consumers with added transparency and brands with deeper insights into supply chain behavior. In food and pharmaceutical sectors, smart elements within pillow pouches can alert users to product authenticity or environmental exposure. Brands are incorporating these elements to improve consumer trust and meet rising expectations around safety and traceability. It supports the growing need for interactive and intelligent packaging that connects physical products with digital experiences. The pillow pouch packaging market is responding to this shift with investments in embedded data technologies and sensor-ready materials.
- For instance, QR codes and RFID tags, are being integrated into pillow pouches to provide enhanced transparency, product safety, and supply chain traceability. These features are especially important in food and pharmaceuticals, where they help ensure authenticity and regulatory compliance while meeting rising consumer expectations for information and safety.
Growth of Single-Serve and Portion-Controlled Formats to Match Lifestyle Shifts:
There is a rising preference for portion-controlled and single-serve packaging formats that cater to individual consumption and dietary awareness. Consumers are seeking convenience without committing to larger volumes, especially in health-conscious and urban demographics. Pillow pouches are increasingly being designed in compact sizes that support this shift, providing ease of use while minimizing food waste. Brands use these formats to target specific use cases such as travel, office snacks, and fitness supplements. It allows greater product flexibility while aligning with consumer preferences for moderation and portability. The pillow pouch packaging market is expanding its portfolio to meet demand for these smaller, more personalized units.
Brand Diversification Across Niche Categories Encouraging Format Innovation:
New and emerging brands in niche categories—such as plant-based foods, artisanal snacks, and organic cosmetics—are adopting flexible pouches to express brand identity and functionality. These brands often prioritize minimalistic design, sustainable sourcing, and clean labelling, all of which are well-suited to the pillow pouch format. Pouch packaging offers the flexibility to test limited runs and seasonal variations without extensive upfront investment. It empowers start-ups and specialty manufacturers to compete in visually crowded marketplaces with agile, attractive, and cost-efficient packaging. The pillow pouch packaging market is evolving alongside this wave of niche product growth, supporting a wider range of creative and market-specific packaging solutions.
Market Challenges Analysis:
Complexity in Recycling Multi-Layered Materials Poses a Barrier to Sustainability Goals:
Many pillow pouches rely on multi-layered film structures that combine plastics, foils, and adhesives to deliver barrier performance, durability, and visual appeal. While effective for product protection, these layered materials are difficult to separate during recycling, often rendering the packaging non-recyclable through conventional systems. This creates tension between consumer demand for sustainability and the industry’s reliance on complex materials. Regulatory frameworks in several countries are tightening rules around single-use and non-recyclable packaging, forcing manufacturers to accelerate the shift toward recyclable or compostable alternatives. The pillow pouch packaging market faces a growing challenge in aligning with these regulations while maintaining functional integrity. It requires investment in material innovation and collaboration across the packaging value chain.
High Dependence on Specialized Machinery Increases Capital and Operational Constraints:
Production of pillow pouches requires specialized forming, filling, and sealing equipment, which involves high initial capital expenditure and ongoing maintenance. Smaller manufacturers may face barriers to entry due to limited access to advanced machinery or technical expertise. Operational challenges, such as changeover time, format flexibility, and film compatibility, can also impact production efficiency and profitability. Equipment downtime or errors in sealing can lead to product wastage and quality issues, directly affecting margins. The pillow pouch packaging market must address these equipment-related constraints to remain scalable and cost-efficient across different production environments. It places pressure on equipment manufacturers to deliver more flexible, user-friendly, and affordable systems to meet evolving market needs.
Market Opportunities:
Expansion into Emerging Markets Unlocks New Revenue Streams for Flexible Packaging:
Rapid urbanization, rising disposable income, and expanding retail infrastructure in emerging markets are creating strong demand for packaged goods. Countries in Asia, Africa, and Latin America are experiencing a shift toward modern trade channels, where convenience and hygiene drive packaging choices. Pillow pouches offer cost-effective solutions that align with these priorities, especially in food, beverage, and personal care segments. The pillow pouch packaging market stands to gain by expanding distribution networks and partnering with local manufacturers in these regions. It presents an opportunity to scale volume while tailoring formats to regional consumer preferences and price sensitivities. Brands that invest early in market education and localized innovation can build long-term competitive advantages.
Innovation in Eco-Friendly and Mono-Material Solutions Supports Regulatory Compliance:
The rising pressure to eliminate hard-to-recycle plastics creates a strong opportunity for companies investing in sustainable packaging technologies. Mono-material pillow pouches made from polyethylene or polypropylene are gaining interest for their recyclability and compatibility with circular economy models. Brands adopting these formats can meet environmental regulations while enhancing corporate responsibility narratives. The pillow pouch packaging market can capitalize on this shift by accelerating R&D and forming alliances with sustainable material suppliers. It allows packaging producers to offer differentiated, future-ready solutions that appeal to both consumers and regulators. This innovation pathway opens access to premium markets and long-term customer loyalty.
Market Segmentation Analysis:
By Material Type
Plastic dominates the material segment, due to its durability, flexibility, and cost efficiency. It supports a wide range of applications, especially in food and beverage packaging. Paper is gaining traction in response to sustainability trends, particularly for dry goods and organic products. Aluminum offers superior barrier protection, making it suitable for pharmaceuticals and high-sensitivity products.
- For example, Sealed Air Cryovac® pillow pouches use multilayer plastic films to extend shelf life by up to 50% for perishable foods.
By Type
Stand-up pillow pouches lead the design segment due to their shelf visibility and stability. Gusseted and flat pillow pouches serve as versatile formats for bulk and single-serve products. Zipper, spouted, window, and resealable pouches are growing in demand, especially in personal care and nutraceutical segments, where consumer convenience and product preservation are critical.
- For instance, Air pillows are inflatable packaging materials that protect fragile items during shipping and handling. They are typically made of plastic film and filled with air, creating a cushioning effect.
By Application
Food and beverages remain the largest application, accounting for 48.9% of the market in 2024, with snacks driving the segment. Pharmaceuticals and personal care follow, supported by the need for compact, hygienic packaging. Other growing areas include pet food, household products, powders, cereals, and liquids, where pillow pouches offer practical benefits.
By End Use Industry
The food and beverage industry dominates end use, driven by changing consumption patterns and the demand for portable packaging. Pharmaceuticals and retail sectors also contribute significantly, requiring packaging solutions that balance compliance, branding, and logistics efficiency.
By Distribution Channel
Retail and brick-and-mortar stores continue to hold a major share, though e-commerce is expanding rapidly. It supports the growth of pillow pouch formats that are lightweight and protective. Food service providers use pillow pouches for portion control and operational ease.
Segmentation:
By Material Type
- Plastic
- Paper
- Aluminum
By Type/Design
- Stand-up Pillow Pouches
- Gusseted Pillow Pouches
- Flat Pillow Pouches
- Zipper Pillow Pouches
- Spouted Pillow Pouches
- Window Pouches
- Re-sealable Pouches
By Application
- Food and Beverages
- Pharmaceuticals
- Personal Care
- Pet Food
- Household Products
- Nutraceuticals
- Toys
- Powders, Spices, Cereals, Liquids
By End Use Industry
- Food & Beverages (includes snacks, confectionery, ready-to-eat meals, beverages)
- Pharmaceuticals
- Retail
- Others
By Distribution Channel
- E-commerce/Online
- Retail/Brick-and-Mortar Stores
- Food Service Providers
By Geography/Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
Asia-Pacific Leads with Robust Consumption and Industrial Growth
Asia-Pacific holds the largest share in the pillow pouch packaging market, accounting for 38.6% in 2024. Rapid urbanization, rising disposable incomes, and strong demand for packaged food and beverages are key drivers across China, India, Indonesia, and Vietnam. These countries are witnessing significant expansion in organized retail and e-commerce, both of which rely on flexible packaging formats for product delivery and shelf visibility. Local manufacturers are scaling up capabilities to meet both domestic and export demand, supported by relatively low production costs and growing adoption of automated packaging systems. The food and beverage segment dominates regional usage, especially in snacks, ready meals, and powdered drinks. It is expected to maintain its leadership position through 2032 with sustained investment in material innovation and packaging infrastructure.
North America Prioritizes Convenience, Sustainability, and Branding
North America represents the second-largest regional market, capturing around 26.4% of global revenue in 2024. High demand for convenient, on-the-go food packaging continues to support growth across the U.S. and Canada. Strong regulatory frameworks and consumer awareness have accelerated the shift toward recyclable and compostable pillow pouch solutions. The region’s mature pharmaceutical and personal care sectors also contribute to increased demand for tamper-evident, resealable, and high-barrier pouch formats. E-commerce growth has strengthened the need for protective, lightweight packaging, making pillow pouches a preferred format for multiple product categories. It is poised for steady growth due to ongoing investments in digital printing, sustainable films, and flexible manufacturing systems.
Europe Emphasizes Eco-Friendly Materials and Compliance Standards
Europe holds 19.8% of the global pillow pouch packaging market in 2024, driven by stringent environmental regulations and high consumer preference for sustainable packaging. Countries like Germany, the UK, and France are at the forefront of adopting mono-material and recyclable pouch formats. Retailers and manufacturers are under pressure to meet EU directives aimed at reducing plastic waste, which boosts demand for paper-based and compostable pouch variants. The food and beverage sector remains dominant, while pharmaceuticals and household products also contribute to regional demand. It supports innovation through government-backed R&D programs and a strong focus on circular economy practices. Europe's growth is moderate yet stable, supported by regulatory clarity and high levels of sustainability compliance.
Key Player Analysis:
- Amcor Limited (Amcor Plc)
- Mondi Group (Mondi Plc)
- Berry Global
- Sealed Air Corporation
- Coveris
- Glenroy Inc.
Competitive Analysis:
The pillow pouch packaging market features a moderately consolidated competitive landscape, with key players focusing on material innovation, sustainability, and expansion into emerging markets. Leading companies such as Amcor Plc, Mondi Group, Berry Global, Sealed Air Corporation, and Coveris hold a significant share through established global supply chains and advanced manufacturing capabilities. These firms invest in recyclable and mono-material solutions to meet evolving regulatory and consumer demands. Mid-sized players like Glenroy Inc. and ProAmpac LLC emphasize product customization, digital printing, and short-run flexibility to serve niche and regional markets. Strategic partnerships, acquisitions, and capacity expansions are common strategies aimed at strengthening geographic reach and product portfolios. The pillow pouch packaging market remains competitive, driven by continuous technological advancement, pricing pressure, and the growing demand for lightweight, functional, and sustainable packaging formats. It encourages innovation across all company tiers to meet the rising expectations of food, pharmaceutical, and personal care brands worldwide.
Recent Developments:
- In June 2025, Amcor Limited (Amcor Plc) highlighted the ongoing success and expansion of its AmLite Ultra Recyclable pillow pouch product line. AmLite Ultra Recyclable pouches are now used by over 200 food brands globally, offering high-barrier protection and reducing packaging weight compared to rigid alternatives. These pillow pouches are available with features such as resealable zippers, clear windows, and wrap-around graphics, supporting both shelf appeal and on-the-go convenience for snacks and other food products. This innovation is part of Amcor’s commitment to making all packaging recyclable or reusable by 2025.
- In December 2024, Mondi Group (Mondi Plc) and Proquimia launched a new paper-based stand-up pouch for dishwashing tabs in Spain and Portugal. The pouch, made from Mondi’s re/cycle FunctionalBarrier Paper 95/5, contains more than 85% paper and is fully recyclable in local paper streams. This collaboration demonstrates Mondi’s continued focus on sustainable packaging solutions and its MAP2030 commitment to keeping valuable raw materials in circulation.
- In January 2025, Berry Global announced it would debut its latest packaging innovations at Cosmoprof 2025 in Bologna, Italy. The company is set to showcase new products including the Grace actuator for the Wave 2cc pump and an expanded Exclusive Stick and Refill range, now available in three new travel-friendly sizes. These launches highlight Berry Global’s emphasis on functional, refillable, and aesthetically advanced packaging for personal care and beauty applications.
- On January 23, 2025, Amcor and Berry Global jointly announced a major milestone toward the completion of their previously announced all-stock transaction. The companies filed a definitive joint proxy statement with the U.S. Securities and Exchange Commission, with shareholder meetings scheduled for February 25, 2025. The transaction is expected to create a global leader in consumer and healthcare packaging, with estimated synergies of $650 million and a combined annual cash flow of over $3 billion, significantly expanding the companies’ flexible packaging portfolios.
Market Concentration & Characteristics:
The pillow pouch packaging market exhibits moderate concentration, with a few dominant players accounting for a substantial share while numerous regional and specialized firms compete across niche segments. It is characterized by a strong emphasis on product innovation, sustainability compliance, and design flexibility. Companies differentiate through advancements in film technology, resealability features, and customized branding solutions. The market favors firms with integrated manufacturing, printing, and material sourcing capabilities. Growth opportunities exist across both high-volume commodity segments and premium, value-added formats. It responds quickly to evolving consumer trends and regulatory shifts, particularly in sustainability and packaging waste reduction.
Report Coverage:
The research report offers an in-depth analysis based on By Material Type, By Type, By Application, By End Use Industry, By Distribution Channel and By Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The market will continue to expand steadily, driven by rising demand for convenient, portable packaging across food and personal care sectors.
- Recyclable and mono-material pillow pouches will gain traction as sustainability regulations tighten globally.
- Demand for digitally printed pouches will increase, enabling short-run customization and brand differentiation.
- Emerging markets in Asia-Pacific, Latin America, and Africa will offer new growth avenues due to rising consumption and retail expansion.
- Technological advancements in barrier films will improve shelf life and product protection for sensitive goods.
- E-commerce growth will reinforce the need for durable, lightweight pillow pouch formats suitable for direct-to-consumer shipping.
- Pharmaceutical and nutraceutical applications will expand due to rising healthcare awareness and demand for hygienic packaging.
- Smaller players will adopt automation and flexible production systems to compete on cost and speed.
- Visual appeal and resealability features will influence consumer purchasing behavior, especially in premium segments.
- Strategic partnerships and acquisitions will accelerate innovation and market penetration across diverse regions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Pillow Pouch Packaging Market?
What are the key segments within the Pillow Pouch Packaging Market?
What are some challenges faced by the Pillow Pouch Packaging Market?
Who are the major players in the Pillow Pouch Packaging Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Pillow Pouch Packaging Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Pillow Pouch Packaging Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 8,343 million → 2032: USD 14,016.4 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Pillow Pouch Packaging Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Pillow Pouch Packaging Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Pillow Pouch Packaging Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Pillow Pouch Packaging Market Drivers
- 3.3 Pillow Pouch Packaging Market Restraints & Challenges
- 3.4 Pillow Pouch Packaging Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Pillow Pouch Packaging Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Pillow Pouch Packaging Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Pillow Pouch Packaging category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Pillow Pouch Packaging Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Pillow Pouch Packaging Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Pillow Pouch Packaging market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Pillow Pouch Packaging Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Pillow Pouch Packaging Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Pillow Pouch Packaging Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Pillow Pouch Packaging (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Pillow Pouch Packaging Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Pillow Pouch Packaging Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Pillow Pouch Packaging Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Pillow Pouch Packaging Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Pillow Pouch Packaging Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Pillow Pouch Packaging Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Pillow Pouch Packaging Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Pillow Pouch Packaging Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Pillow Pouch Packaging Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
