
Market Overview
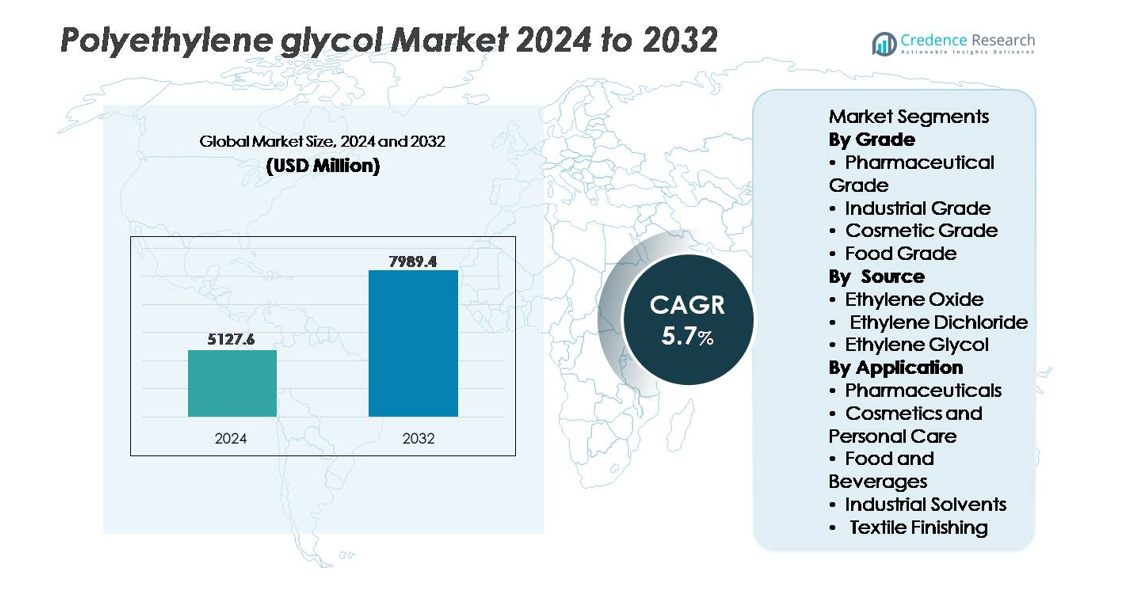
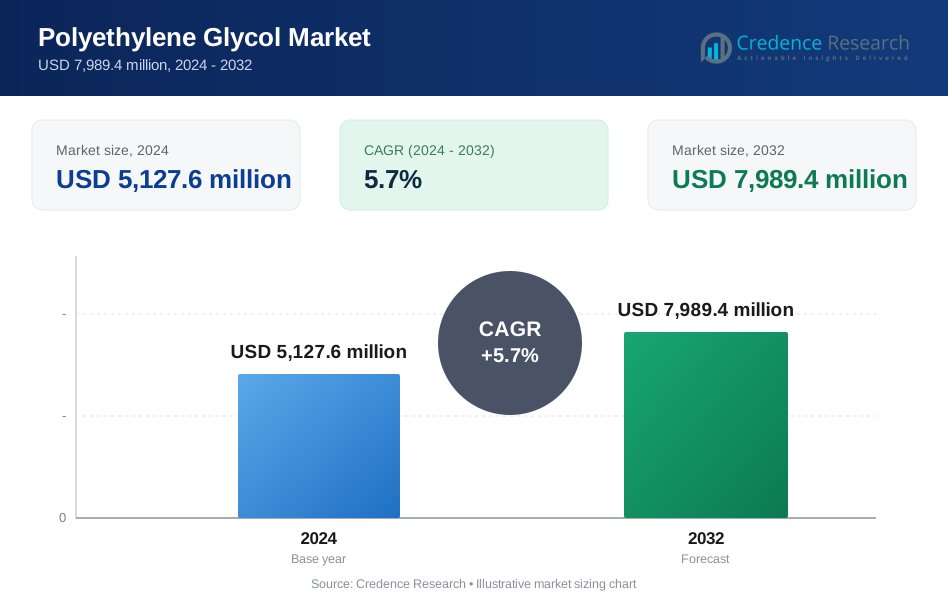
The global polyethylene glycol market was valued at USD 5,127.6 million in 2024 and is projected to reach USD 7,989.4 million by 2032, reflecting a CAGR of 5.7% over the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Polyethylene Glycol Market Size 2024 | USD 5,127.6 million |
| Polyethylene Glycol Market, CAGR | 5.7% |
| Polyethylene Glycol Market Size 2032 | USD 7,989.4 million |
The polyethylene glycol market is dominated by a mix of global chemical manufacturers and regional specialty producers, including Huntsman Corporation, BASF SE, Dow Chemicals, INEOS, Clariant, Croda International, AkzoNobel N.V., India Glycols, Liaoning Oxiranchem, and Jiangsu Haian Petrochemical Plant. Asia Pacific stands as the leading production and consumption hub, holding approximately 48% of the global market share, supported by large-scale pharmaceutical, cosmetics, and industrial manufacturing bases. North America and Europe follow, collectively accounting for about 44%, driven by demand for high-purity PEG grades used in biologics, drug delivery systems, and advanced personal care formulations. The competitive landscape increasingly emphasizes purity levels, molecular weight customization, and sustainable manufacturing innovation.
Market Insights
- The global polyethylene glycol market was valued at USD 5,127.6 million in 2024 and is projected to reach USD 7,989.4 million by 2032, reflecting a CAGR of 5.7%.
- Market growth is primarily driven by expanding pharmaceutical formulations, increasing PEG utilization in biologics and topical applications, and rising demand across cosmetics, personal care, and industrial processing.
- Key trends include customization of molecular weight PEG for drug delivery, rising investment in PEGylation technologies, and growing interest in bio-based PEG to support sustainable manufacturing.
- The market remains moderately consolidated with major players competing on purity grades, compliant production, and application-specific formulation support; strategic expansions and long-term supply contracts shape the competitive environment.
- Regionally, Asia Pacific leads with around 48% share, followed by North America and Europe jointly holding about 44%, while pharmaceutical grade PEG accounts for the dominant segment share, supported by regulated excipient demand and biologics-oriented applications.
Market Segmentation Analysis:
By Grade
Pharmaceutical grade polyethylene glycol holds the dominant market share, driven by its extensive use as a binder, plasticizer, and solubilizing agent in oral, ophthalmic, and injectable formulations. Its regulatory acceptance across USP, EP, and JP standards supports accelerated adoption in generics and biologics manufacturing. Industrial grade follows in demand for lubricants, coolants, and chemical intermediates, while cosmetic grade continues expanding in skin-conditioning products due to its non-irritant profile. Food-grade PEG maintains a niche position, primarily in food processing aids and packaging additives, restrained by strict compliance requirements.
- For instance, Clariant supplies Polyglykol 8000 P, a PEG with a mean molecular weight of 8,000 g/mol that meets IPEC-GMP standards for use in pharmaceutical excipients and drug processing.
By Source
Ethylene oxide remains the leading source for polyethylene glycol production, commanding the largest share due to its efficiency, high purity yield, and scalability for pharmaceutical and cosmetic-grade PEG. Its controlled polymerization process ensures consistent molecular weights essential for drug delivery and excipient functionality. Ethylene glycol contributes significantly as a cost-effective route for industrial applications but is less preferred for regulated uses. Ethylene dichloride represents the smallest share owing to environmental concerns and stricter emission standards, which continue to limit its utilization in modern PEG value chains.
- For instance, INEOS’ acquisition of LyondellBasell’s Bayport facility provides access to a 420,000-ton-per-year ethylene oxide unit and a 375,000-ton-per-year ethylene glycols unit, directly strengthening its PEG feedstock backbone.
By Application
Pharmaceuticals represent the dominant application segment, utilizing polyethylene glycol in laxatives, ointments, soft-gel coatings, and controlled-release systems, powered by rising chronic disease treatments and expanding biopharmaceutical pipelines. Cosmetics and personal care follow as PEG supports emulsification, moisture retention, and texture enhancement in creams, shampoos, and sun care formulations. In food and beverages, PEG is applied in processing aids and anti-foaming agents, while industrial solvents rely on PEG’s lubricity and chemical stability. Textile finishing demands PEG for fiber lubrication and antistatic properties, supporting efficiency in spinning and weaving operations.
Key Growth Drivers
Expanding Pharmaceutical and Biopharmaceutical Formulations
Polyethylene glycol (PEG) benefits significantly from the surge in pharmaceutical formulations, including oral dosage, injectables, topical applications, and controlled-release platforms. Its solubility enhancement, binding capacity, and tolerance profile position PEG as a preferred excipient across generics and specialty therapies. The rise of biologics and biosimilars fuels additional demand, particularly for PEGylation techniques that prolong half-life and improve bioavailability of therapeutic proteins. PEGylated drugs continue to gain approvals globally, reinforcing commercial visibility. Increasing population longevity, chronic disease prevalence, and healthcare expenditure collectively support the continued integration of PEG in advanced drug delivery, formulation stabilization, and biologic pipeline expansion.
- For instance, Nektar Therapeutics’ proprietary PEGylation platform has enabled PEG-modified proteins exceeding molecular weights of 20,000 g/mol to extend circulation time of biologics in oncology and immunology applications.
Growing Penetration in Cosmetic, Personal Care, and Dermatological Solutions
Rising consumer spending on skincare, dermo-cosmetics, and premium formulations drives the adoption of PEG as an emulsifier, moisturizer, and texture modifier. Its ability to enhance product feel, stabilize oil-water phases, and support non-greasy formulations enables PEG to align with evolving demand for lightweight, multifunctional products. PEG-based compounds play an important role in sunscreens, conditioners, cleansers, and anti-aging creams. The growing influence of clean beauty and ingredient transparency encourages manufacturers to reformulate using recognized and regulatory-compliant additives. With digital retail reshaping product cycles and customization trends advancing, PEG remains relevant across scalable manufacturing and specialized cosmetic product lines.
- For instance, Polyethylene glycol 6000 (PEG 6000) uses a polyethylene glycol with a molecular weight of 6,000 g/mol to improve viscosity stability and conditioning in haircare formulations from various suppliers. Croda International sells a similar product for home care and industrial uses called Renex™ PEG 6000.
Industrial Applications Supporting Process Efficiency and Specialty Manufacturing
Polyethylene glycol delivers performance advantages in industrial value chains, including lubricity, thermal stability, humectancy, and solvation. These characteristics make PEG integral to metalworking fluids, plasticizers, inks, resins, textile lubricants, and chemical processing aids. Demand accelerates with manufacturing automation, electronics assembly growth, and industrial equipment requiring precise thermal and mechanical stability. PEG’s compatibility with water-based systems also supports transition from solvent-heavy formulations. Its functional versatility across temperature resilience, viscosity modification, and anti-static performance reinforces its adoption in automotive coatings, adhesives, and textile finishing, aligning with productivity improvements and quality standardization across global industrial sectors.
Key Trends & Opportunities
Advancement in PEGylation and Biologic Drug Delivery Technologies
PEGylation creates opportunities in specialty drug delivery by improving molecular stability and reducing immunogenicity of biologics and peptides. Pharmaceutical innovators explore customized PEG chain lengths and architectures to fine-tune pharmacokinetics, enabling longer dose intervals and improved patient compliance. This trend expands into next-generation therapies including RNA-based medicines, antibody fragments, and gene delivery vectors. As biologics require enhanced shelf stability and controlled dispersion, PEG remains positioned as a critical enabling material. Increasing regulatory guidance specificity for modified excipients further promotes investment in PEG-based drug delivery innovation.
- For instance, Nektar Therapeutics has developed PEG polymers reaching molecular weights up to 40,000 g/mol for conjugation with peptide and protein therapeutics to extend systemic circulation time.
Sustainable Manufacturing and Bio-Based PEG Development
Sustainability-centered chemical production opens new pathways for bio-based PEG derived from renewable raw materials. With global directives on carbon reduction and lifecycle transparency, manufacturers explore green feedstock integration, energy-efficient polymerization methods, and low-VOC applications. Bio-based PEG offers opportunities in personal care, pharmaceuticals, and food processing where product labeling and environmental performance influence purchasing decisions. Technological advances in fermentation and catalytic conversion could improve cost competitiveness, increasing commercial viability. The shift toward circular polymers, packaging optimization, and end-of-life recyclability continues to frame bio-derived PEG as a strategic growth opportunity in the broader chemical sustainability landscape.
- For instance, India Glycols Limited produces bio-ethylene oxide and bio-ethylene glycol derived from molasses-based ethanol, enabling PEG production through renewable feedstock routes and supporting downstream PEG variants built on plant-based glycol inputs.
Key Challenges
Regulatory and Compliance Constraints Across End-Use Industries
Polyethylene glycol interacts with strict regulatory frameworks governing pharmaceuticals, food additives, and cosmetic ingredients. Variations in regional compliance standards, excipient certification, permissible concentration levels, and documentation requirements impose high validation costs. Manufacturers operating in multiple markets face complex approvals, stability testing obligations, and evolving ingredient labeling standards. Regulatory scrutiny intensifies for excipients used in biologics and pediatric formulations, increasing analytical testing expectations. These dynamics create market entry barriers, delay commercialization timelines, and increase operational overhead, particularly for small and mid-sized producers.
Feedstock Price Volatility and Supply Chain Dependence on Petrochemical Inputs
PEG production depends heavily on petrochemical derivatives such as ethylene oxide and ethylene glycol, exposing manufacturers to fluctuations in crude oil pricing, supply disruptions, and geopolitical risks. Instability in feedstock availability impacts production economics and margin predictability. Transportation costs, refinery maintenance cycles, and import dependence in emerging markets further compound volatility. These challenges influence the cost competitiveness of PEG against alternative polymers and additives. Unpredictable pricing also affects long-term contracts with pharmaceutical and industrial buyers, creating planning complexity and hindering capital investment for capacity expansion.
Regional Analysis
Asia Pacific
The Asia Pacific region leads the PEG market, commanding roughly 47%-48% of global revenue share in 2024. Rapid industrialization, growing pharmaceutical production, and rising demand for personal-care and cosmetic products drive this dominance. Expanding middle-class populations in key countries like China and India boost consumption of healthcare and skin-care items that use PEG. Additionally, growth in construction, textiles, and industrial manufacturing enhances demand for PEG in lubricants, solvents, and process aids making Asia Pacific the fastest-growing region for PEG globally.
North America
North America holds a significant share estimated at around 26%-28% in recent years. The region’s mature pharmaceutical sector, stringent regulatory standards, and high demand for high-purity PEG in medical formulations support strong adoption. Demand from personal care, cosmetics, and industrial segments such as specialty solvents and coatings further strengthens consumption. Technological innovation and regulatory compliance drive manufacturers to rely on PEG for drug delivery systems, topical applications, and industrial processes.
Europe
Europe accounts for approximately 18%-20% of the global PEG market share as of 2024. The demand is driven by regulatory emphasis on quality, biocompatibility, and increasingly, sustainability prompting adoption of high-purity and eco-conscious PEG variants. Growing demand in personal care, cosmetics, and pharmaceuticals under CE/REACH regulations sustains steady market consumption. Additionally, interest in “green chemistry” and bio-based PEG solutions particularly for cosmetics and healthcare creates opportunities for market expansion in the region.
Latin America (LAMEA)
Latin America (alongside Middle East & Africa) contributes a smaller slice of the global PEG market around 8%-9% in 2024. Growth in this region is modest due to lower industrial and pharmaceutical infrastructure compared with mature markets. However, demand exists in industries such as food processing, basic cosmetics, and light industrial applications, where PEG is used in solvents, processing aids, and personal-care products. As economic development and industrialization gradually improve, the region shows potential for incremental growth in PEG consumption.
Middle East & Africa
The Middle East & Africa region, though smaller in scale, constitutes part of the broad “LAMEA” category mentioned above contributing alongside Latin America to the roughly 8-9% market share. Demand in this region arises from industrial and chemical processing needs, basic personal care, and emerging pharmaceutical sectors. However, adoption levels remain constrained by lower per-capita consumption, variable regulatory frameworks, and limited high-purity PEG demand. As infrastructure and healthcare investments increase, this region may see gradual uptake, albeit at a slower pace compared to Asia Pacific or North America.
Market Segmentations:
By Grade
· Pharmaceutical Grade
- Industrial Grade
- Cosmetic Grade
- Food Grade
By Source
- Ethylene Oxide
- Ethylene Dichloride
- Ethylene Glycol
By Application
- Pharmaceuticals
- Cosmetics and Personal Care
- Food and Beverages
- Industrial Solvents
- Textile Finishing
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the polyethylene glycol (PEG) market is characterized by the presence of established chemical producers, specialized polymer manufacturers, and integrated petrochemical companies competing on product purity, customization capability, and global distribution strength. Leading participants focus on pharmaceutical-grade and high-purity PEG production to address rising demand from biologics, topical formulations, and controlled-release drug systems, while also targeting specialty applications in cosmetics, industrial solvents, and textile finishing. Strategic initiatives include capacity expansion, feedstock optimization, bio-based PEG research, and long-term supply partnerships with pharmaceutical and personal-care brands. Competitive differentiation increasingly relies on technical expertise, compliance with multi-regional regulatory standards, and ability to deliver consistent molecular weight PEG variants. Sustainability-centered innovation is emerging as a key competitive lever, with companies exploring green sourcing, reduced emissions, and recyclable formulations to align with evolving customer expectations and environmental policies.
Key Player Analysis
- Huntsman Corporation
- India Glycols
- BASF SE
- Liaoning Oxiranchem
- Clariant
- AkzoNobel N.V.
- Jiangsu Haian Petrochemical Plant
- Dow Chemicals
- INEOS
- Croda International
Recent Developments
- In May 2025, BASF introduced a new reactive polyethylene glycol product Pluriol® A 2400 I-for use in construction-industry superplasticizers in Europe, thus expanding its PEG-related portfolio.
- In October 2024, Clariant unveiled a portfolio expansion of high-performance excipients for pharmaceuticals at a major industry trade show, explicitly targeting applications such as injectables and other sensitive formulations signalling its commitment to PEG and excipient-grade polymer supply.
- In May 2024, INEOS completed acquisition of the ethylene oxides & derivatives business from LyondellBasell including the associated upstream feedstock capacity enhancing INEOS’s access to ethylene oxide/ethylene glycol feedstocks that are critical for PEG production.
Report Coverage
The research report offers an in-depth analysis based on Grade, Source, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for high-purity PEG will rise as biologics, biosimilars, and injectable therapies gain wider clinical adoption.
- PEGylation technologies will continue evolving to improve therapeutic stability and controlled drug release.
- Cosmetic and personal-care producers will integrate PEG into multifunctional, performance-centric formulations.
- Bio-based and sustainably sourced PEG alternatives will gain traction as environmental standards tighten.
- Industrial automation will increase consumption of PEG-based lubricants, solvents, and processing aids.
- Customized molecular weight PEG grades will expand precision applications in pharmaceuticals and specialty chemicals.
- Regulatory alignment across regions will shape competitive positioning and certification requirements.
- Strategic partnerships between chemical suppliers and pharma companies will accelerate formulation innovation.
- Emerging markets will contribute incremental growth driven by healthcare expansion and industrialization.
- Digital commerce and rapid product development cycles will fuel PEG demand in personal-care consumer brands.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Polyethylene Glycol, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Polyethylene Glycol market projected to grow between 2024 and 2032?
Which Polyethylene Glycol segment held the largest share in 2024?
What are the primary factors fueling the growth of the Polyethylene Glycol market?
Who are the leading companies in the Polyethylene Glycol market
Which region commanded the largest share of the Polyethylene Glycol market in 2024
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 5,127.6 million → 2032: USD 7,989.4 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Polyethylene Glycol Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Polyethylene Glycol Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Polyethylene Glycol Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Polyethylene Glycol Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Polyethylene Glycol Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Polyethylene Glycol Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Polyethylene Glycol Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Polyethylene Glycol Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 5,127.6 million → 2032: USD 7,989.4 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Polyethylene Glycol Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Polyethylene Glycol Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Polyethylene Glycol Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Polyethylene Glycol Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

