
Market Overview:
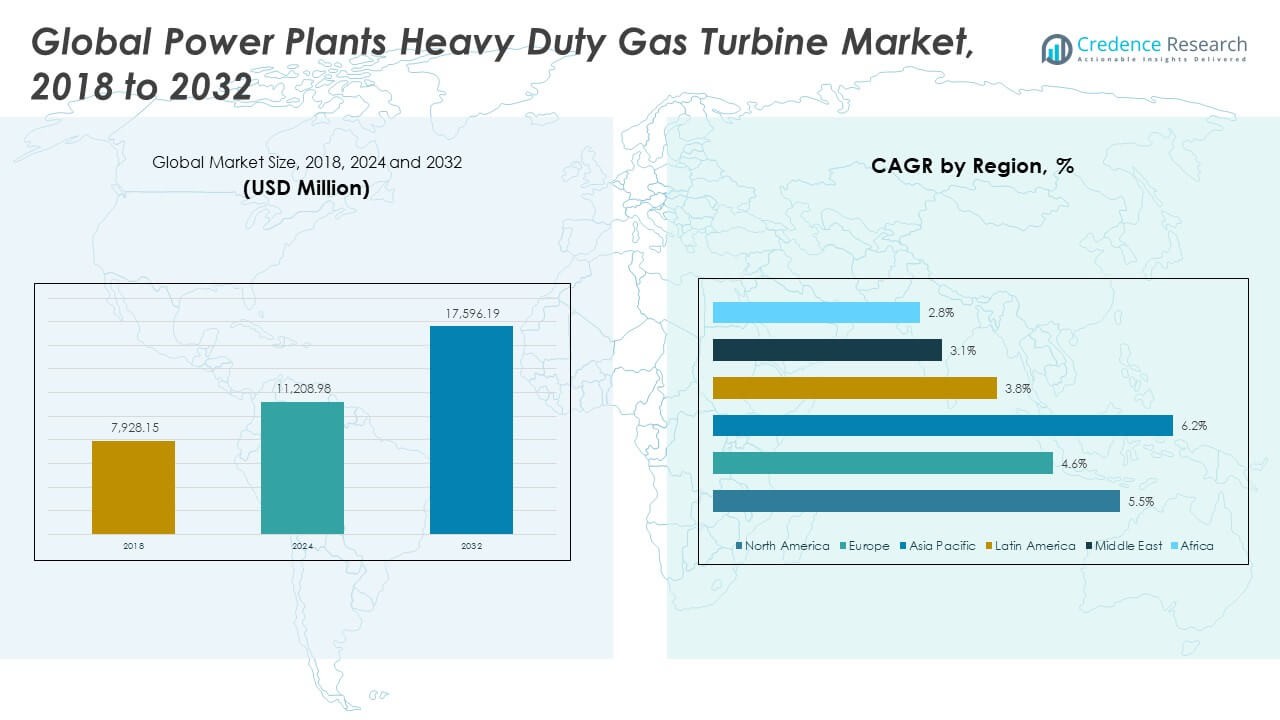
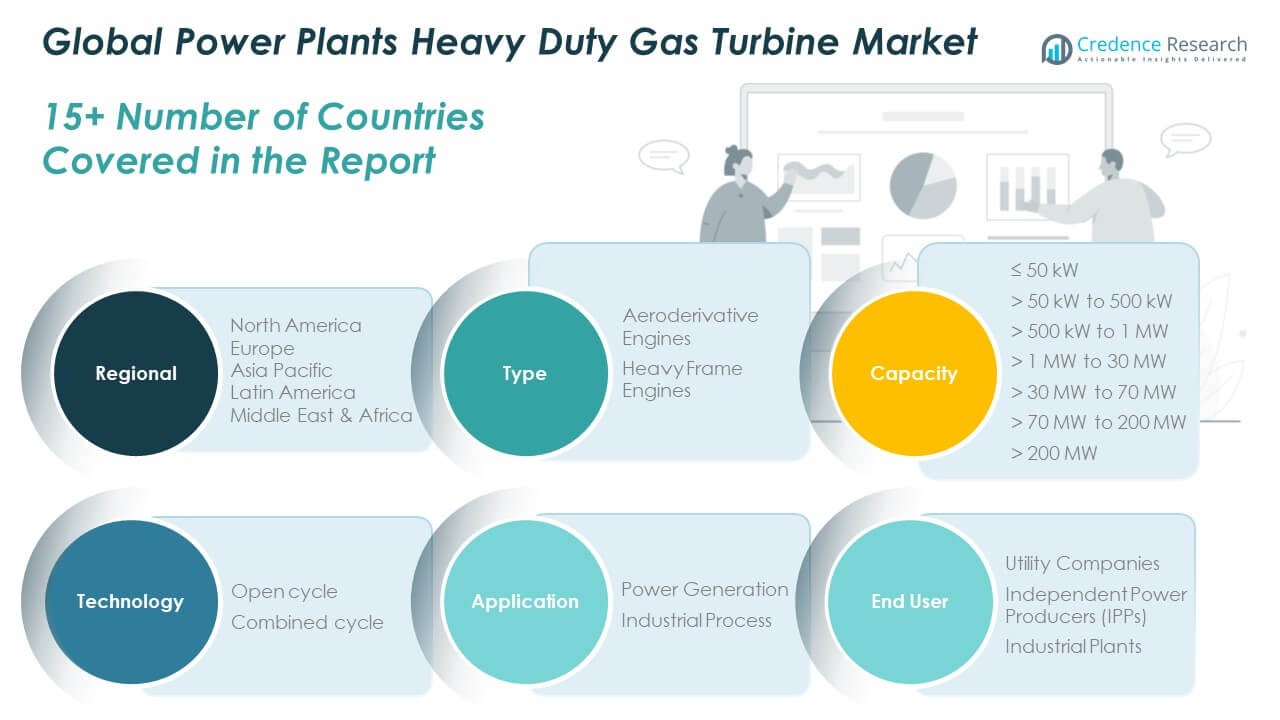
The Global Power Plants Heavy Duty Gas Turbine Market size was valued at USD 7,928.15 million in 2018 to USD 11,208.98 million in 2024 and is anticipated to reach USD 17,596.19 million by 2032, at a CAGR of 5.40% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Power Plants Heavy Duty Gas Turbine Market Size 2024 | USD 11,208.98 Million |
| Power Plants Heavy Duty Gas Turbine Market, CAGR | 5.40% |
| Power Plants Heavy Duty Gas Turbine Market Size 2032 | USD 17,596.19 Million |
Growing electricity demand and a global shift toward cleaner energy generation drive steady adoption of heavy-duty gas turbines. Power producers favor gas-based systems for their high efficiency, reliability, and lower emissions compared to coal-fired plants. Technological advancements, including hydrogen-ready designs and combined-cycle configurations, strengthen long-term deployment. Governments and utilities also focus on reducing carbon intensity through gas turbine modernization and integration into hybrid renewable systems.
Regionally, Asia Pacific leads due to rapid industrialization and strong investment in new generation capacity. North America and Europe follow with significant replacement demand from aging infrastructure and decarbonization targets. The Middle East shows strong opportunities through large-scale projects, while Latin America and Africa present emerging prospects driven by energy diversification and industrial growth.
Market Insights:
- The Global Power Plants Heavy Duty Gas Turbine Market was valued at USD 7,928.15 million in 2018, reaching USD 11,208.98 million in 2024, and is projected to hit USD 17,596.19 million by 2032, growing at a CAGR of 5.40%.
- Asia Pacific leads with 45.1% share, driven by rapid industrialization, infrastructure growth, and large-scale investments in gas-based combined-cycle power plants.
- Europe follows with 26.4% share, supported by stringent emission norms and strong adoption of hybrid and hydrogen-ready turbine systems, while North America holds 19.3% share due to modernization and replacement demand.
- Asia Pacific remains the fastest-growing region, fueled by expanding urban electrification, industrialization, and government incentives for cleaner energy generation.
- By type, heavy frame engines account for about 65% of total market share due to wide baseload adoption, while aeroderivative engines hold roughly 35%, favored for mobility and peaking power applications.
Key Market Drivers
Rising Demand for Reliable and Efficient Power Generation Technologies
The Global Power Plants Heavy Duty Gas Turbine Market benefits from the global shift toward efficient and cleaner power generation. Countries are moving away from coal-based systems, preferring advanced gas turbines that provide high efficiency and faster startup times. Governments promote gas-fired generation to reduce greenhouse gas emissions. Industrial and residential energy consumption growth drives new installations of combined-cycle plants. The rising need for uninterrupted electricity supports investments in heavy-duty gas turbines. Companies focus on upgrading existing units with digital control systems for operational efficiency. It is becoming a preferred solution for large-scale base-load and peak-load applications.
- For instance, Siemens Energy implemented an upgrade of the SGT6-5000F gas turbines at the High Desert Power Project, which successfully added around 12 MW of output per unit and enhanced efficiency through its advanced ULN combustor and F(X) ATEP package. This project was officially documented by Siemens Energy as part of its ongoing power plant modernization initiatives aimed at improving performance and reducing fuel consumption.
Technological Innovation Enhancing Performance and Durability of Gas Turbines
Continuous technological improvement plays a crucial role in expanding the Global Power Plants Heavy Duty Gas Turbine Market. Manufacturers develop high-temperature alloys and ceramic coatings that boost turbine efficiency and service life. The integration of digital twins, predictive analytics, and AI-based monitoring improves reliability and reduces maintenance costs. Fuel flexibility enables turbines to operate on hydrogen blends and biofuels, aligning with global decarbonization goals. Compact modular designs help reduce plant footprint and construction time. Operators gain higher efficiency from advanced cooling and combustion technologies. Power producers prefer newer turbine models for lower emissions and cost efficiency.
- For instance, Mitsubishi Power successfully operated its JAC gas turbine with a 30% hydrogen fuel blend, demonstrating stable combustion at a turbine inlet temperature of 1650°C, while achieving NOx emissions under 25 ppm validated in December 2023 at the company’s Takasago Hydrogen Park.
Government Policies Supporting Clean and Flexible Energy Infrastructure
Regulatory policies and environmental commitments drive adoption of modern gas turbines. Governments in Europe, Asia-Pacific, and North America introduce incentives for combined-cycle power plants. Many nations aim to achieve carbon neutrality by 2050, making gas turbines key transition tools. Investments in renewable-gas hybrid systems promote flexible and stable power generation. The market benefits from emission reduction regulations that discourage older fossil-fuel units. Energy diversification strategies favor natural gas due to its cleaner combustion and abundant supply. It gains support through international climate commitments and national modernization programs.
Growing Replacement of Ageing Thermal Power Plants Across Developing Regions
Developing countries replace outdated coal and oil-fired plants with advanced gas turbine systems. Rising industrialization and rapid urban expansion fuel the need for efficient electricity generation. Governments in Asia and the Middle East prioritize grid stability through combined-cycle installations. The Global Power Plants Heavy Duty Gas Turbine Market expands due to rising electricity consumption. Infrastructure upgrades in emerging economies ensure sustainable and flexible generation. Manufacturers benefit from regional partnerships and long-term service agreements. It continues to attract investment through modernization programs and international funding support.
Key Market Trends
Integration of Hydrogen-Based Fuel Systems in Heavy-Duty Gas Turbines
A major trend involves developing turbines compatible with hydrogen and alternative clean fuels. Manufacturers adapt combustion systems for hydrogen blends up to 50% or higher. This innovation supports the global transition toward carbon-free energy. Utilities invest in hybrid plants combining gas and renewable sources. The Global Power Plants Heavy Duty Gas Turbine Market sees growing collaboration between energy companies and OEMs for hydrogen-ready models. Pilot projects in Japan, the U.S., and Europe test turbines designed for full hydrogen operation. It reflects the industry’s direction toward long-term decarbonization and sustainability.
- For instance, Mitsubishi Power achieved a world-first 50% hydrogen fuel blend on an advanced-class M501GAC gas turbine (283 MW output) during trials at Georgia Power’s Plant McDonough-Atkinson (June 2025), providing a 22% reduction in CO₂ emissions compared to 100% natural gas operation, with full engineering documentation and partnership confirmation available from Mitsubishi Power and Georgia Power.
Expansion of Combined-Cycle Power Plants for High Efficiency and Low Emissions
Combined-cycle plants gain traction due to their superior thermal efficiency and operational flexibility. Integrating gas and steam turbines maximizes output while minimizing fuel costs. Many nations adopt these plants for stable baseload generation. The Global Power Plants Heavy Duty Gas Turbine Market grows through demand for dual-fuel and hybrid configurations. Investors view combined-cycle plants as transitional solutions before full renewable adoption. Upgraded turbines help reduce nitrogen oxide emissions and maintenance frequency. It strengthens energy portfolios by balancing renewable intermittency and ensuring stable supply.
Digitalization and Predictive Maintenance Transforming Operational Strategies
Digital technology plays a central role in modern turbine management. AI-driven monitoring systems forecast maintenance needs and minimize unplanned downtime. Operators use IoT-based analytics for performance optimization and cost reduction. The Global Power Plants Heavy Duty Gas Turbine Market benefits from digital twins that simulate turbine behavior. Remote diagnostics enable real-time decision-making for global operations. Cloud-based solutions support long-term service agreements between OEMs and utilities. It allows improved asset performance management and lifecycle cost savings.
- For instance, GE's Predix AI-driven predictive maintenance platform is widely used in power utilities to reduce unplanned downtime and improve operational reliability. GE Vernova’s APM solution, leveraging Predix, has shown significant improvements in reducing downtime and increasing efficiency across various power generation systems, particularly in thermal plants and gas turbines.
Strategic Collaborations and Mergers Strengthening OEM Market Presence
Leading companies pursue partnerships and acquisitions to expand their technology portfolios. OEMs form alliances with energy firms to co-develop hydrogen-ready turbines. Regional collaborations enhance aftersales services and local manufacturing capacity. The Global Power Plants Heavy Duty Gas Turbine Market witnesses growing consolidation for cost efficiency. Joint ventures in Asia-Pacific and the Middle East target rapid capacity additions. These alliances focus on achieving global emission and performance benchmarks. It ensures broader access to technical expertise and service support.
Market Challenges
Volatile Natural Gas Prices and Supply Chain Disruptions Impacting Profitability
Fluctuating fuel prices directly affect operational margins in gas-fired power generation. Supply uncertainties caused by geopolitical conflicts create instability in project planning. The Global Power Plants Heavy Duty Gas Turbine Market faces pressure from rising LNG prices. Limited long-term gas supply contracts hinder financial predictability for operators. Transport and logistics constraints delay new installations in developing nations. Manufacturers experience higher material costs, especially for advanced alloys and precision components. It challenges OEMs to maintain competitive pricing while meeting efficiency standards.
Increasing Competition from Renewable Energy Sources and Policy Uncertainty
Renewable energy expansion limits new gas turbine investments in several regions. Falling solar and wind energy costs make hybrid solutions more attractive. Governments adjust energy policies frequently, creating uncertainty in project financing. The Global Power Plants Heavy Duty Gas Turbine Market must adapt to changing power mix priorities. Public pressure to reduce fossil fuel dependency affects new approvals for gas-based projects. Grid operators prioritize flexible energy storage systems over turbine-based balancing. It pushes turbine manufacturers to innovate for hybrid and hydrogen-compatible systems.
Market Opportunities
Emerging Role of Hydrogen and Biofuel Integration in Next-Generation Turbines
The integration of hydrogen and biofuels provides new opportunities for manufacturers. Turbine designs are evolving to handle varied fuel compositions while maintaining efficiency. Countries investing in hydrogen infrastructure create demand for compatible gas turbines. The Global Power Plants Heavy Duty Gas Turbine Market can leverage these trends to enter new energy domains. OEMs that commercialize fuel-flexible turbines will gain an advantage in the transition economy. It positions gas technology as a bridge between fossil and renewable energy.
Rapid Urbanization and Power Demand Growth in Developing Economies
Expanding urban populations increase electricity demand in Asia-Pacific, Africa, and Latin America. National governments prioritize reliable power infrastructure to support industrialization. Investors fund large-scale gas turbine projects to ensure grid reliability. The Global Power Plants Heavy Duty Gas Turbine Market benefits from economic growth and infrastructure upgrades. Local manufacturing and service facilities reduce costs and enhance competitiveness. It enables OEMs to secure long-term contracts and regional partnerships.
Market Segmentation Analysis:
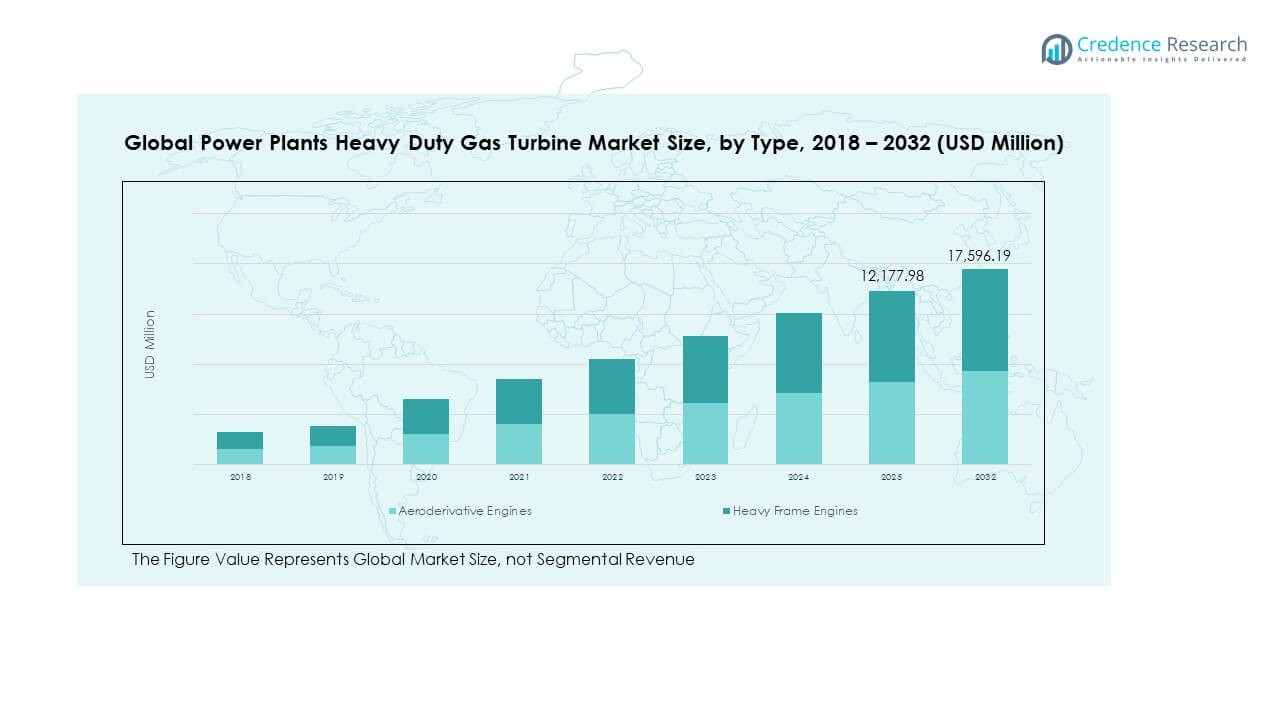
The Global Power Plants Heavy Duty Gas Turbine Market is segmented by type, capacity, technology, application, and end user.
By type, aeroderivative engines and heavy frame engines form the primary categories. Aeroderivative engines are valued for mobility, quick start, and high efficiency in peaking applications, while heavy frame engines dominate large-scale baseload power generation due to their durability and cost efficiency. It continues to witness strong demand from countries focusing on gas-based infrastructure expansion.
- For instance, General Electric’s LM6000 aeroderivative gas turbine achieves a simple-cycle efficiency of up to 41.3% (LHV) and can start up in as little as 5 minutes, supporting rapid response in peaking power applications.
By capacity, the market includes categories ranging from ≤ 50 kW to > 200 MW, addressing diverse power generation requirements. Smaller capacity turbines cater to industrial and localized applications, while high-capacity models above 70 MW serve utility-scale power stations.
By technology, the open cycle and combined cycle segments under technology demonstrate different operational strengths; combined cycle units lead in adoption because of their superior fuel efficiency and low emissions.
By application, power generation dominates due to rapid global electrification and transition from coal-based systems. The industrial process segment is gaining importance across petrochemical and manufacturing sectors that need continuous, reliable energy sources.
- For instance, Solar Turbines’ Taurus 60 industrial gas turbine delivers 5,670 kWe of electrical output and achieves a simple-cycle efficiency of 31.5–32%, with NOx emissions below 25 ppm (at 15% O₂), making it suitable for industrial cogeneration and process applications.
By end user, utility companies, independent power producers (IPPs), and industrial plants represent key customer groups. Utility companies lead adoption due to large network-scale projects, while IPPs contribute through new capacity additions and flexible grid supply initiatives. It continues to grow with expanding investments in high-efficiency, low-emission turbine technologies worldwide.
Segmentation:
By Type
- Aeroderivative Engines
- Heavy Frame Engines
By Capacity
- ≤ 50 kW
- 50 kW to 500 kW
- 500 kW to 1 MW
- 1 MW to 30 MW
- 30 MW to 70 MW
- 70 MW to 200 MW
- 200 MW
By Technology
- Open Cycle
- Combined Cycle
By Application
- Power Generation
- Industrial Process
By End User
- Utility Companies
- Independent Power Producers (IPPs)
- Industrial Plants
By Regional Outlook
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America Global Power Plants Heavy Duty Gas Turbine Market size was valued at USD 1,564.59 million in 2018 to USD 2,161.21 million in 2024 and is anticipated to reach USD 3,413.85 million by 2032, at a CAGR of 5.5% during the forecast period. North America holds around 19.3% of the total market share. The region maintains strong demand due to advanced energy infrastructure, growing focus on carbon-neutral generation, and continuous upgrades of existing thermal assets. The United States leads the market with new combined-cycle gas turbine projects supported by federal clean energy incentives. Canada and Mexico contribute through modernization of industrial power facilities. High reliability requirements across utilities drive adoption of large-capacity turbines. It also benefits from the integration of hydrogen-ready technologies and digital monitoring systems. Partnerships between OEMs and power producers ensure continuous operational efficiency across long-term projects.
Europe
The Europe Global Power Plants Heavy Duty Gas Turbine Market size was valued at USD 2,174.17 million in 2018 to USD 2,959.25 million in 2024 and is anticipated to reach USD 4,363.98 million by 2032, at a CAGR of 4.6% during the forecast period. Europe accounts for approximately 26.4% of the global share. The market is driven by the shift toward low-carbon energy systems and replacement of coal-fired capacity. Nations like Germany, France, and the United Kingdom deploy gas turbines to stabilize renewable-heavy grids. Investments in hydrogen infrastructure enhance the appeal of turbine-based generation. It focuses on efficiency upgrades and emission reduction technologies. OEMs engage in strategic alliances for fuel-flexible and hybrid turbine solutions. Stringent EU environmental policies and regional energy diversification strengthen the market outlook.
Asia Pacific
The Asia Pacific Global Power Plants Heavy Duty Gas Turbine Market size was valued at USD 3,450.60 million in 2018 to USD 5,059.39 million in 2024 and is anticipated to reach USD 8,428.73 million by 2032, at a CAGR of 6.2% during the forecast period. Asia Pacific dominates with around 45.1% of the global share. Rising industrialization, population growth, and urban electrification boost demand for efficient power generation. China, India, and Japan lead new capacity additions with large-scale combined-cycle installations. Governments emphasize reliability and energy diversification, supporting the transition from coal. It experiences strong investment from OEMs expanding local manufacturing and service networks. Southeast Asia presents emerging opportunities for distributed and industrial power generation. The region’s robust economic growth underpins long-term market potential.
Latin America
The Latin America Global Power Plants Heavy Duty Gas Turbine Market size was valued at USD 382.41 million in 2018 to USD 534.08 million in 2024 and is anticipated to reach USD 744.10 million by 2032, at a CAGR of 3.8% during the forecast period. Latin America contributes nearly 4.8% of the global market share. Brazil and Mexico dominate regional activity through energy transition programs and industrial demand. The modernization of thermal power assets drives steady turbine deployment. Governments aim to expand grid capacity and ensure stability during renewable integration. It witnesses growing adoption of mid-capacity turbines for flexible generation. OEMs collaborate with regional EPCs to improve project delivery and cost efficiency. Emerging economies like Chile and Colombia strengthen future growth prospects.
Middle East
The Middle East Global Power Plants Heavy Duty Gas Turbine Market size was valued at USD 215.92 million in 2018 to USD 278.30 million in 2024 and is anticipated to reach USD 366.49 million by 2032, at a CAGR of 3.1% during the forecast period. The region holds nearly 2.8% of the market share. Growth is driven by expanding power infrastructure in GCC nations and industrial diversification plans. Saudi Arabia and the UAE lead investments in gas-based combined-cycle plants. National energy policies support efficient and flexible generation systems. It benefits from large utility tenders and long-term service contracts. Rising electricity consumption from commercial and industrial sectors fuels demand. OEMs establish regional service centers to enhance reliability and performance.
Africa
The Africa Global Power Plants Heavy Duty Gas Turbine Market size was valued at USD 140.46 million in 2018 to USD 216.76 million in 2024 and is anticipated to reach USD 279.04 million by 2032, at a CAGR of 2.8% during the forecast period. Africa accounts for nearly 1.6% of the global market share. Power generation projects expand gradually due to infrastructure limitations and investment gaps. South Africa, Egypt, and Nigeria lead deployment in industrial and utility applications. Governments seek to enhance grid stability through gas-based capacity additions. It benefits from international funding and partnerships promoting clean generation. The region’s vast natural gas reserves support future turbine adoption. OEMs target modular and mobile turbine solutions to serve decentralized networks.
Key Player Analysis:
- GE Vernova
- Ansaldo Energia
- Baker Hughes
- Siemens Energy
- Mitsubishi Power
- Kawasaki Heavy Industries
- Solar Turbines Incorporated
- Harbin Electric Corporation
- MAN Energy Solutions
- MHPS Dongfang Turbine Co., Ltd.
- Rolls-Royce Holdings plc
- Doosan Heavy Industries & Construction Co., Ltd.
- OPRA Turbines B.V.
- Zorya-Mashproekt
Competitive Analysis:
The competitive landscape of the Global Power Plants Heavy Duty Gas Turbine Market is characterised by a handful of major original equipment manufacturers (OEMs) who hold significant market power. Companies like GE Vernova, Siemens Energy, and Mitsubishi Power dominate the global heavy-duty gas turbine arena with high-capacity models, extensive service networks and global project execution capabilities. They invest heavily in advanced materials, hydrogen-ready combustion systems, and digital solutions to differentiate their offerings and capture share. Pricing power remains strong due to limited competition, high barriers to entry, and long product lifecycles. Regional players and niche suppliers play supporting roles but face sizeable scale and technology gaps. Service agreements, aftermarket support and long-term performance contracts further lock in customer relationships. Innovation, strategic partnerships and geographic expansion will determine which firms maintain leadership.
Recent Developments:
- In November 2025, TotalEnergies entered into a major joint venture partnership with Energetický a průmyslový holding (EPH). The collaboration involves TotalEnergies acquiring a 50% stake in EPH’s 14 GW flexible power portfolio across Europe, including several large-scale gas-fired power plant sites.
- In July 2025, Fermi America agreed to a significant acquisition of over 600 MW of clean gas generation capacity from Firebird LNG, in conjunction with Siemens Energy. This transaction includes six SGT800 gas turbines, six heat recovery steam generators, and related equipment, all earmarked for efficient combined-cycle operations to deliver reliable and low-emission power.
Report Coverage:
The research report offers an in-depth analysis based on by type, capacity, technology, application, and end user. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Global Power Plants Heavy Duty Gas Turbine Market is expected to experience steady expansion driven by global electrification needs.
- Replacement of coal-based power plants with cleaner gas turbines will continue across major economies.
- Adoption of combined-cycle configurations will increase due to higher efficiency and lower carbon output.
- Integration of hydrogen and biofuel-ready turbines will reshape fuel flexibility and energy transition pathways.
- Governments will promote large-scale investments in grid modernization and gas-based infrastructure.
- Digital monitoring, AI diagnostics, and predictive maintenance will enhance operational reliability.
- Strategic alliances between OEMs and energy utilities will accelerate regional deployment.
- Asia Pacific will lead in new capacity additions, supported by urbanization and industrialization.
- North America and Europe will emphasize modernization and emission control through turbine upgrades.
- Continuous R&D efforts in turbine material science and heat recovery systems will strengthen long-term market competitiveness.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Global Power Plants Heavy Duty Gas Turbine Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Global Power Plants Heavy Duty Gas Turbine Market projected to grow between 2024 and 2032?
Which Global Power Plants Heavy Duty Gas Turbine Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Global Power Plants Heavy Duty Gas Turbine Market?
Who are the leading companies in the Global Power Plants Heavy Duty Gas Turbine Market?
Which region commanded the largest share of the Global Power Plants Heavy Duty Gas Turbine Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Power Plants Heavy Duty Gas Turbine Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Power Plants Heavy Duty Gas Turbine Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 11,208.98 million → 2032: USD 17,596.19 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Power Plants Heavy Duty Gas Turbine Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Power Plants Heavy Duty Gas Turbine Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Power Plants Heavy Duty Gas Turbine Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Power Plants Heavy Duty Gas Turbine Market Drivers
- 3.3 Power Plants Heavy Duty Gas Turbine Market Restraints & Challenges
- 3.4 Power Plants Heavy Duty Gas Turbine Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Power Plants Heavy Duty Gas Turbine Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Power Plants Heavy Duty Gas Turbine Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Power Plants Heavy Duty Gas Turbine category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Power Plants Heavy Duty Gas Turbine Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Power Plants Heavy Duty Gas Turbine Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Power Plants Heavy Duty Gas Turbine. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Power Plants Heavy Duty Gas Turbine Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – the historical period vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Power Plants Heavy Duty Gas Turbine Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution (the historical period vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Power Plants Heavy Duty Gas Turbine Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Power Plants Heavy Duty Gas Turbine (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Power Plants Heavy Duty Gas Turbine
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Power Plants Heavy Duty Gas Turbine Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Power Plants Heavy Duty Gas Turbine Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Power Plants Heavy Duty Gas Turbine Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Power Plants Heavy Duty Gas Turbine Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Power Plants Heavy Duty Gas Turbine Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Power Plants Heavy Duty Gas Turbine Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Power Plants Heavy Duty Gas Turbine Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Power Plants Heavy Duty Gas Turbine Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
