
Market Overview
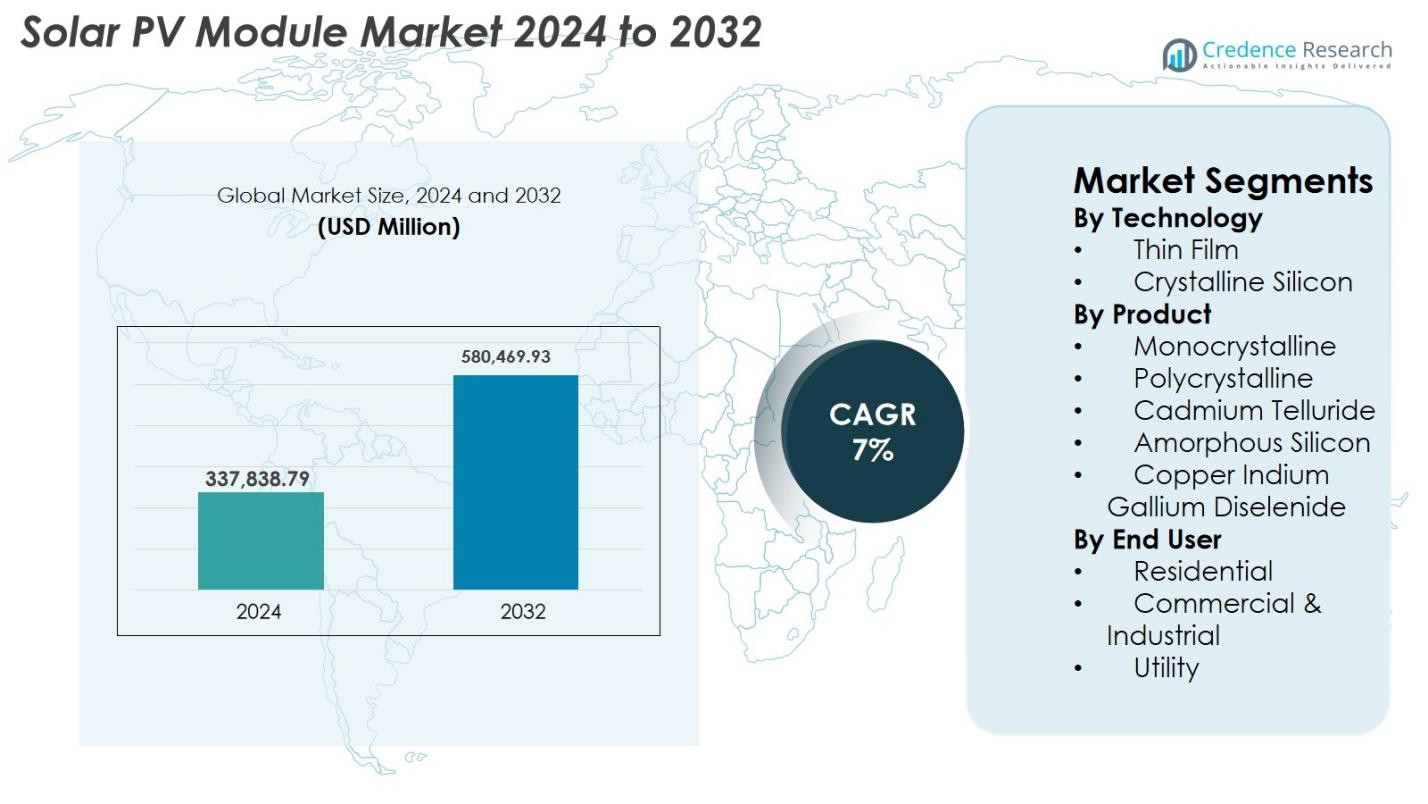
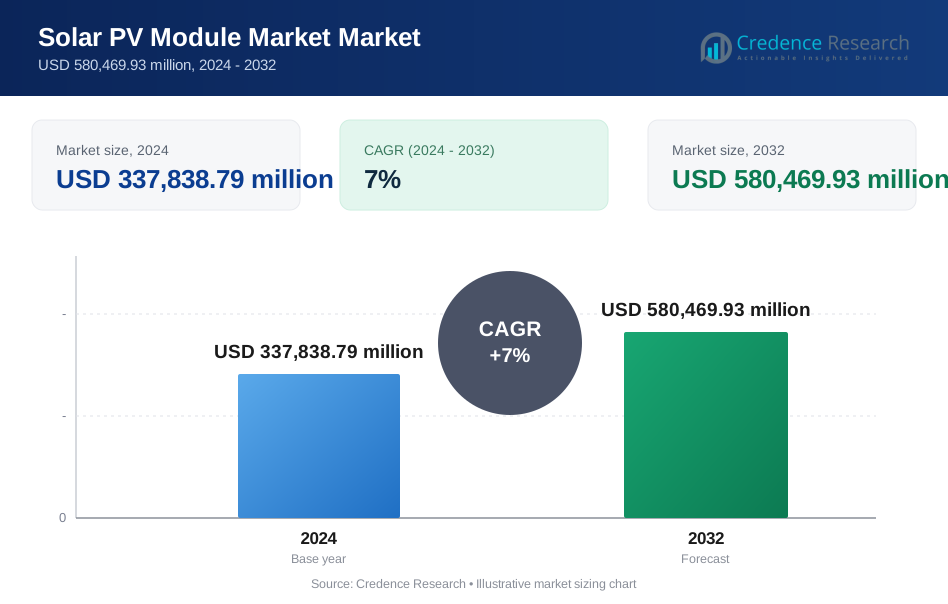
Solar PV Module Market size was valued at USD 337,838.79 Million in 2024 and is anticipated to reach USD 580,469.93 Million by 2032, at a CAGR of 7% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Solar PV Module Market Size 2024 | USD 337,838.79 Million |
| Solar PV Module Market, CAGR | 7% |
| Solar PV Module Market Size 2032 | USD 580,469.93 Million |
Solar PV Module Market is shaped by leading manufacturers such as LONGi, Jinko Solar, JA Solar Technology, Canadian Solar, First Solar, Hanwha Q CELLS, GCL-SI, Trina Solar, and Risen Energy, all of which compete through high-efficiency monocrystalline, bifacial, and advanced cell technologies. These companies continue expanding production capacity and global distribution networks to meet rising demand across utility, commercial, and residential sectors. Asia-Pacific remains the dominant region, commanding 41.6% of the global market in 2024, driven by large-scale installations in China and India. Europe follows with 25.7%, supported by strong sustainability mandates, while North America holds 21.4% through policy-backed deployment momentum.
Market Insights
- The Solar PV Module Market reached USD 337,838.79 million in 2024 and is projected to grow to USD 580,469.93 million by 2032, registering a CAGR of 7% during the forecast period.
- Market growth is driven by expanding utility-scale solar projects, declining module prices, and supportive government incentives promoting clean energy adoption across residential, commercial, and industrial sectors.
- Key trends include rising demand for high-efficiency monocrystalline modules, rapid adoption of bifacial and large-format panels, and increasing investment in automated, low-carbon manufacturing processes.
- The competitive landscape is led by major players such as LONGi, Jinko Solar, JA Solar Technology, Canadian Solar, First Solar, and Hanwha Q CELLS, focusing on technological innovation and global capacity expansion.
- Asia-Pacific dominates with a 41.6% share, followed by Europe at 25.7% and North America at 21.4%; the utility segment leads overall adoption with a 54.2% share due to large-scale project deployment.
 Market Segmentation Analysis
By Technology
Thin Film and Crystalline Silicon technologies form the core of the Solar PV Module Market, with crystalline silicon dominating the segment with a market share of 78.4% in 2024. Its leadership is driven by high energy conversion efficiency, long operational life, and broad suitability across residential, commercial, and utility-scale deployments. Thin Film technologies such as CdTe and CIGS continue to gain traction due to their lightweight structure, superior low-light performance, and lower manufacturing costs, making them attractive for large-scale utility installations and emerging applications like BIPV and flexible solar products.
- For instance, in 2024, First Solar’s CdTe modules achieved a certified 23.1% efficiency, reinforcing the competitiveness of thin-film architectures.
By Product
Among monocrystalline, polycrystalline, cadmium telluride, amorphous silicon, and CIGS modules, monocrystalline panels lead the Solar PV Module Market with a 62.7% share in 2024. Their dominance stems from superior efficiency, higher power density, and rapidly declining manufacturing costs due to technological improvements and large-scale production. Polycrystalline modules retain relevance in cost-sensitive markets, while thin-film variants such as CdTe and CIGS are favored for utility-scale deployments and projects requiring better temperature tolerance. The shift toward high-efficiency n-type TOPCon and HJT monocrystalline modules further reinforces their market leadership.
- For instance, First Solar’s Series 7 CdTe modules delivered up to 540 W output with enhanced thermal performance, making them the top choice for utility-scale plants.
By End User
The residential, commercial & industrial, and utility sectors collectively drive demand, with the utility segment commanding a 54.2% share in 2024, the highest within the Solar PV Module Market. Growth is driven by large-scale solar parks, favorable auction mechanisms, and rapid adoption of high-wattage bifacial and monocrystalline modules that maximize energy yield. The commercial & industrial segment expands steadily due to rising rooftop solar adoption, corporate decarbonization targets, and cost-saving initiatives. Residential demand benefits from supportive net-metering policies, energy independence goals, and increased affordability of distributed solar solutions.
Key Growth Drivers
Rising Global Renewable Energy Targets and Policy Support
Governments worldwide are accelerating solar adoption through ambitious renewable-energy targets, tax incentives, net-metering programs, and large-scale solar procurement auctions. These policy frameworks significantly reduce capital costs and offer long-term financial visibility for investors, driving the deployment of high-efficiency PV modules across residential, commercial, and utility-scale sectors. Countries such as China, India, and the U.S. continue to expand solar capacity additions, encouraged by climate commitments, decarbonization mandates, and energy security objectives. Additionally, the declining cost per watt of PV modules, improvement in manufacturing efficiencies, and expansion of domestic production under subsidy-driven schemes strengthen market growth. Subsidized rooftop programs, feed-in tariffs, and low-interest financing further enhance consumer adoption. Collectively, these regulatory and financial enablers create a favorable ecosystem that accelerates solar module demand globally and positions solar as a mainstream power source.
- For instance, in 2024, India’s PM-Surya Ghar initiative offered rooftop solar subsidies covering up to 40% of system costs, accelerating household installations.
Advancements in High-Efficiency Module Technologies
Continuous innovation in module design such as the evolution from p-type to n-type architectures, bifacial designs, and advanced cell technologies like TOPCon and HJT significantly boosts energy yield and performance in diverse climatic conditions. These high-efficiency modules reduce the levelized cost of electricity (LCOE), enabling more competitive solar projects, particularly in space-constrained installations where power density is critical. Manufacturers are scaling up larger module formats, increasing cell counts, and integrating multi-busbar and half-cut configurations to minimize resistive losses and enhance durability. Such innovations not only improve power output but also extend module lifespan and reduce degradation rates. Utility developers increasingly prefer high-efficiency modules for maximizing return on investment, while commercial and residential users benefit from lower installation costs and improved system productivity. The ongoing R&D focus ensures continuous performance gains that accelerate market adoption.
- For instance, JA Solar introduced DeepBlue 4.0 Pro modules with reinforced multi-busbar layouts to reduce resistance and enhance long-term reliability.
Expanding Utility-Scale Solar Projects and Corporate Sustainability Commitments
The rapid global rise in utility-scale solar developments represents one of the strongest demand catalysts for PV modules. Governments and private developers are commissioning gigawatt-scale solar parks to diversify energy portfolios, reduce fossil-fuel dependency, and meet long-term climate obligations. Simultaneously, corporate sustainability initiatives driven by ESG mandates and net-zero targets are accelerating investment in large commercial solar installations and power purchase agreements (PPAs). Major industries such as data centers, manufacturing, logistics, and retail are deploying on-site and off-site solar solutions to optimize energy costs and reduce carbon footprints. The integration of bifacial, high-wattage monocrystalline modules further enhances project viability by increasing yield per acre. As solar becomes a strategic asset for businesses and national grids, the sustained expansion of large-scale deployments significantly drives module demand worldwide.
Key Trends & Opportunities
Increasing Shift Toward Bifacial and Large-Format Modules
A major trend reshaping the Solar PV Module Market is the rapid transition to bifacial and large-format modules that deliver superior energy generation at lower LCOE. Bifacial modules capture sunlight from both sides, increasing energy output by 5–20% depending on installation conditions, making them highly attractive for utility-scale developers. Simultaneously, large-format modules such as 182 mm and 210 mm wafer-based designs enable higher wattage ratings, reduced BOS costs, and improved installation efficiencies. This shift also creates opportunities for innovations in module glass, encapsulants, and tracker systems. As global projects seek higher operational efficiency and lower lifecycle costs, demand for these advanced module formats continues to grow. The trend aligns with the increasing adoption of digital monitoring systems, smart inverters, and AI-driven optimization tools.
- For instance, in 2024, Trina Solar’s Vertex N 210 mm bifacial modules delivered up to 700 W output, improving energy yield for large utility plants.
Growing Role of Building-Integrated Photovoltaics (BIPV)
BIPV is emerging as a high-potential opportunity as urban infrastructure evolves toward sustainability and energy self-sufficiency. Solar modules integrated into building facades, rooftops, skylights, and shading structures transform architectural components into energy-generating assets, reducing grid dependence while improving aesthetics. The development of semi-transparent, colored, and customizable PV glass expands adoption possibilities for commercial buildings, metro stations, airports, and residential high-rises. This trend aligns strongly with green building certifications and net-zero construction mandates in regions such as Europe, North America, and Asia. Advancements in thin-film and perovskite materials further enhance BIPV viability by improving low-light performance and enabling lightweight designs. As cities accelerate the shift toward carbon-neutral infrastructure, BIPV offers a strong long-term growth opportunity for module manufacturers.
- For instance, in 2024, Onyx Solar installed semi-transparent PV glass at the Boston Logan Airport terminal, generating onsite renewable energy while maintaining natural daylighting.
Key Challenges
Volatility in Raw Material Prices and Supply Chain Constraints
The Solar PV Module Market faces significant pressure from fluctuations in raw materials such as polysilicon, silver, aluminum, and specialty glass, all of which strongly influence production costs. Supply chain disruptions driven by geopolitical tensions, logistics bottlenecks, and concentrated manufacturing hubs create uncertainty for developers and manufacturers. Price volatility affects long-term project planning, tender pricing, and procurement strategies, sometimes delaying project execution. Moreover, high dependence on a limited number of global polysilicon suppliers increases vulnerability during demand surges. These challenges call for diversified sourcing, alternative metallization technologies like copper, and expanded regional manufacturing to improve supply resilience and stabilize costs across the solar value chain.
Land Availability, Grid Integration, and Intermittency Issues
As solar installations expand rapidly, developers face increasing constraints in securing suitable, extensive land parcels for utility-scale projects, especially in densely populated regions. Grid integration challenges including transmission congestion, limited substation capacity, and the need for advanced grid-balancing infrastructure pose additional obstacles. Intermittency issues require supplementary investments in energy storage, hybrid systems, or modernized grid technologies to maintain reliability. Regulatory delays, environmental approvals, and community concerns can extend project timelines. These limitations highlight the need for coordinated grid expansion, improved policy frameworks, and accelerated adoption of storage technologies. Addressing these issues is critical for sustaining the long-term growth of large-scale solar deployment.
Regional Analysis
North America
North America holds 21.4% of the Solar PV Module Market in 2024, driven by strong federal incentives, renewable portfolio standards, and the rapid expansion of utility-scale solar projects in the U.S. The Inflation Reduction Act continues to catalyze domestic manufacturing, reducing import dependency and supporting large project pipelines. Growing corporate procurement of clean energy, rising residential rooftop adoption, and state-level net-metering programs further accelerate demand. Canada strengthens deployment through decarbonization commitments, while Mexico’s industrial sector increasingly adopts solar to lower energy costs. Technological advancements and grid modernization efforts reinforce steady growth.
Europe
Europe accounts for 25.7% of the Solar PV Module Market in 2024, supported by aggressive carbon-neutrality goals, rising electricity prices, and strong investments in distributed solar systems. Germany, Spain, the Netherlands, and France lead installations due to supportive feed-in tariffs, rebates, and sustainability mandates. The EU’s Green Deal and solar manufacturing resilience initiatives are encouraging regional production and reducing reliance on Asian imports. Rooftop solar adoption is rising across residential, commercial, and industrial sectors, while large-scale solar parks gain momentum. Demand for bifacial and BIPV modules continues to expand across the region.
Asia-Pacific
Asia-Pacific dominates the Solar PV Module Market with a 41.6% share in 2024, driven by massive solar expansion efforts in China, India, Japan, South Korea, and Australia. China leads global manufacturing and utility-scale deployment, supported by strong government incentives and low-cost production capabilities. India’s tender-driven installations, corporate PPAs, and rooftop programs continue accelerating adoption. Japan and South Korea favor high-efficiency modules for limited land environments, while Australia sees strong residential uptake. Rapid urbanization, expanding industrial demand, and supportive policy frameworks make Asia-Pacific the fastest-growing and most influential regional market.
Latin America
Latin America holds 6.8% of the Solar PV Module Market in 2024, with Brazil, Chile, and Mexico driving most installations. Competitive auction schemes, excellent solar resources, and rising private-sector investment support robust utility-scale deployment. Brazil’s distributed generation policy strongly boosts rooftop and commercial installations, while Chile advances toward carbon neutrality through large-scale solar development in the Atacama Desert. Mexico’s industrial sector increasingly adopts solar to reduce long-term energy costs. Falling module prices and expanding grid infrastructure improve regional project economics, supporting continued market expansion across Latin America.
Middle East & Africa (MEA)
The Middle East & Africa region captures 4.5% of the Solar PV Module Market in 2024, driven by major utility-scale projects in the UAE, Saudi Arabia, Egypt, Morocco, and South Africa. GCC nations prioritize solar to diversify energy systems and lower dependence on fossil fuels, with mega solar parks achieving world-leading tariff levels. Africa’s market grows through electrification programs, off-grid solar kits, and emerging commercial installations. Increasing investment in hybrid systems, declining module costs, and supportive government initiatives accelerate adoption across both urban and rural markets.
Market Segmentations
By Technology
- Thin Film
- Crystalline Silicon
By Product
- Monocrystalline
- Polycrystalline
- Cadmium Telluride
- Amorphous Silicon
- Copper Indium Gallium Diselenide
By End User
- Residential
- Commercial & Industrial
- Utility
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Solar PV Module Market features a highly dynamic and consolidated competitive landscape dominated by global manufacturers with extensive production capacities and strong technological capabilities. Leading players including LONGi, Jinko Solar, JA Solar Technology, Canadian Solar, First Solar, Hanwha Q CELLS, GCL-SI, Trina Solar, Risen Energy, and EMMVEE Solar compete through advancements in high-efficiency monocrystalline modules, bifacial technologies, and next-generation cell architectures such as TOPCon and HJT. Many companies are expanding manufacturing footprints across Asia, Europe, and North America to strengthen supply chain resilience and leverage emerging policy incentives. Strategic partnerships, capacity expansions, and investments in automated production lines remain central to maintaining cost competitiveness. Additionally, increasing focus on sustainability, low-carbon manufacturing, and recycling initiatives is shaping long-term competitive differentiation. As utility-scale, commercial, and residential demand accelerates, key players continue prioritizing innovation, global distribution networks, and integrated service offerings to secure greater market share.
Key Player Analysis
- JA SOLAR Technology
- Indosolar
- LONGi
- Hanwha Group
- GCL-SI
- Canadian Solar
- First Solar
- Jinko Solar
- CsunSolarTech
- EMMVEE SOLAR
Recent Developments
- In January 2025, Trina Solar set a new world record by achieving 25.44% conversion efficiency for its n-type fully passivated heterojunction (HJT) solar cell, highlighting the ongoing innovation potential within silicon-based solar technologies.
- In May 2024, LONGi launched the Hi-MO 5 Ice-Shield module, engineered to deliver superior durability and resilience against extreme hail and high-wind events. The design enhances overall reliability, maintains high energy output, and lowers both the levelized cost of energy and balance-of-system expenses compared with previous Hi-MO 5 models.
- In January 2024, First Solar, Inc. opened India’s first fully vertically integrated solar manufacturing facility, covering six acres with an annual output capacity of 3.3 GW and employing around 1,000 people.
Report Coverage
The research report offers an in-depth analysis based on Technology, Product, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will experience steady growth as countries accelerate solar adoption to meet long-term decarbonization and net-zero commitments.
- High-efficiency technologies such as TOPCon, HJT, and perovskite tandem modules will gain wider commercial adoption.
- Bifacial and large-format modules will increasingly dominate utility-scale installations due to higher energy yield and lower LCOE.
- Domestic manufacturing expansion will intensify as governments promote supply chain localization and reduce import dependency.
- Integration of energy storage with solar projects will rise, improving grid stability and enabling round-the-clock renewable power.
- Building-integrated photovoltaics will create new opportunities in urban infrastructure and green construction.
- Recycling and circular-economy initiatives will expand as end-of-life module volumes grow, driving sustainable material recovery.
- Digitalization through AI-based monitoring and predictive maintenance will enhance system performance and operational efficiency.
- Corporate renewable procurement will continue to surge, supporting commercial and industrial solar adoption.
- Emerging markets in Africa, Southeast Asia, and Latin America will become key contributors to global solar module demand.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Solar PV Module market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Solar PV Module market projected to grow between 2024 and 2032?
Which Solar PV Module market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Solar PV Module market?
Who are the leading companies in the Solar PV Module market?
Which region commanded the largest share of the Solar PV Module market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 337,838.79 million → 2032: USD 580,469.93 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Solar PV Module Market Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Solar PV Module Market Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Solar PV Module Market Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Solar PV Module Market Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Solar PV Module Market Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Solar PV Module Market Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Solar PV Module Market Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Solar PV Module Market Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 337,838.79 million → 2032: USD 580,469.93 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Solar PV Module Market Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Solar PV Module Market Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Solar PV Module Market Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Solar PV Module Market Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

