
Power System Analysis Software Market Overview:
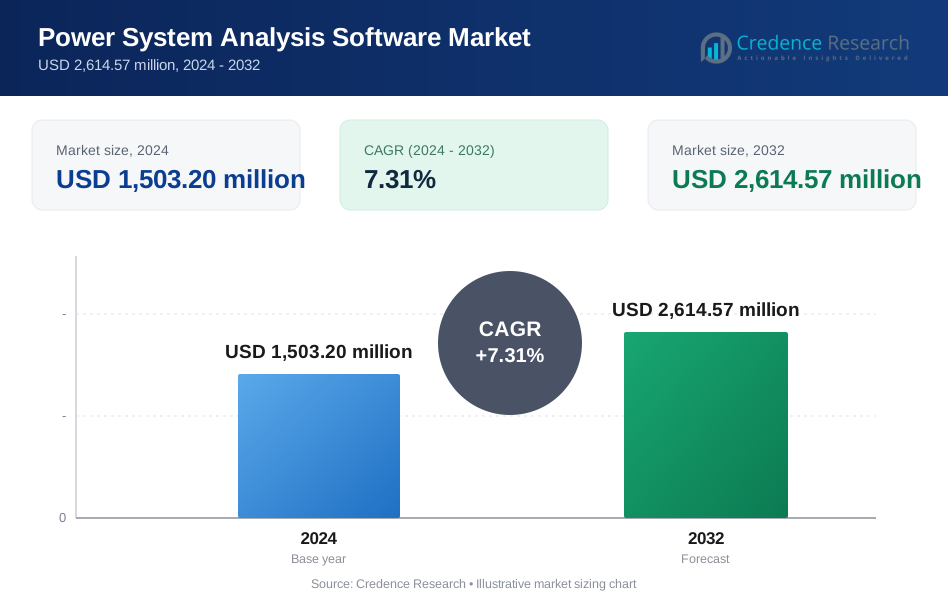
The Power System Analysis Software market size was valued at USD 1,230.00 million in 2018, reached USD 1,503.20 million in 2024, and is anticipated to reach USD 2,614.57 million by 2032, at a CAGR of 7.31% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Power System Analysis Software Market Size 2024 | USD 1,503.20 million |
| Power System Analysis Software Market, CAGR | 7.31% |
| Power System Analysis Software Market Size 2032 | USD 2,614.57 million |
The Power System Analysis Software market is led by major players including ABB Ltd., Siemens AG, General Electric Company, Eaton Corporation plc, and Schneider Electric DMS NS. These companies dominate through comprehensive product portfolios, global service networks, and continued investment in digital grid technologies. They focus on grid simulation, fault analysis, and renewable integration solutions to serve utilities and transmission operators. Regional specialists like DIgSILENT GmbH and Neplan AG cater to niche markets with customized software offerings. North America holds the largest regional share at 35.8% in 2024, driven by advanced grid infrastructure, strong regulatory support, and high smart grid adoption. Asia Pacific follows closely due to rapid industrialization and government-backed renewable energy programs. Leading players strengthen their regional positions through partnerships and tailored deployment models, aligning with local utility requirements and digitalization goals.

Power System Analysis Software Market Insights
- The Power System Analysis Software market was valued at USD 1,230.00 million in 2018, reached USD 1,503.20 million in 2024, and is projected to reach USD 2,614.57 million by 2032, growing at a CAGR of 7.31%.
- Increasing renewable energy integration and the need for accurate grid simulation drive strong demand across utilities and energy operators.
- Cloud-based deployment trends and AI-powered analytics gain momentum, offering flexibility, scalability, and real-time decision support.
- The market is highly competitive with players like ABB Ltd., Siemens AG, and GE dominating through extensive portfolios and regional expansion strategies.
- North America leads with a 35.8% market share in 2024, followed by Asia Pacific at 30%; the electric power distribution segment accounts for the highest share at 39%, driven by grid modernization and distributed energy systems.
Power System Analysis Software Market Segmentation Analysis:
By Deployment
The cloud segment dominates the Power System Analysis Software market with over 63% revenue share in 2024. Its growth is driven by the rising preference for scalable and cost-efficient platforms among utilities and industrial users. Cloud-based systems offer real-time data access, easier updates, and remote collaboration across geographically distributed teams. The increasing integration of renewable energy and demand for smart grid analytics further support cloud adoption. In contrast, on-premises deployment remains relevant for utilities prioritizing data sovereignty, cybersecurity, and infrastructure control, though its market share continues to decline as cloud usage expands.
- For instance, Siemens operates its cloud-based PSS®E and PSS®SINCAL solutions on secure data centers that process grid models with more than 1 million network nodes.
By Application
Electric power distribution leads the application segment, accounting for approximately 39% of total market share in 2024. The sub-segment benefits from grid modernization projects, high DER (distributed energy resource) penetration, and demand-side management requirements. Utilities deploy analysis tools to improve outage response, load balancing, and distribution automation. Transmission applications also see steady uptake due to grid interconnection upgrades and cross-border electricity trade. Power generation applications leverage the software for load forecasting and operational efficiency in thermal and renewable plants. The “Others” segment includes microgrids, industrial power systems, and campus-level energy setups, contributing to niche but growing demand.
- For instance, Schneider Electric deploys its EcoStruxure Grid solutions (such as EcoStruxure Power Monitoring Expert or EcoStruxure ArcFM) which are used by utilities to manage vast distribution networks, some of which exceed 100,000 kilometers of power lines.
Power System Analysis Software Market Key Growth Drivers
Integration of Renewable Energy Sources
The increasing integration of renewable energy into global power grids is a primary driver for power system analysis software. Solar, wind, and hydro introduce variability that challenges grid stability and forecasting. Utilities and operators rely on advanced modeling and simulation tools to analyze grid behavior, optimize load flow, and ensure balance between generation and demand. As governments enforce clean energy targets and carbon neutrality goals, renewable capacity expansions surge, especially in Asia-Pacific, Europe, and North America. This trend boosts demand for power system analysis software to support grid planning, interconnection studies, and real-time management of renewable assets. The software helps identify bottlenecks, simulate contingencies, and guide investment in transmission and storage infrastructure, making it indispensable in the energy transition landscape.
- For instance, GE Vernova uses its GridOS and PSLF power system analysis software to model renewable-heavy grids with more than 500,000 buses in a single simulation.
Rising Investments in Grid Modernization
Aging infrastructure and rising electricity demand push countries to invest in modernizing their transmission and distribution networks. Smart grids, digital substations, and automated demand response systems form the foundation of these upgrades. Power system analysis software supports the planning, design, and validation of such digital transformations. Utilities use the software to simulate future load scenarios, assess the impact of automation, and evaluate cost-benefit strategies. In regions like North America and Western Europe, grid modernization budgets are backed by regulatory support and public-private partnerships. Emerging economies are also adopting advanced grid modeling tools to build resilient power systems. This growing focus on reliability, efficiency, and sustainability accelerates software adoption, especially for long-term network planning and predictive maintenance.
- For instance, ABB deploys its Ability™ Power Network Manager software for utilities operating distribution systems with over 100,000 substations.
Growing Adoption of Smart Grids and IoT
The shift toward smart grids and IoT-enabled infrastructure drives the need for dynamic system analysis. Smart sensors, meters, and automation tools generate large volumes of operational data, which power system analysis software processes to deliver actionable insights. Real-time grid monitoring, fault detection, and energy efficiency optimization become possible with seamless data integration. Utilities increasingly adopt software with AI and machine learning features to improve predictive analytics. The demand for intelligent network planning and faster decision-making further propels adoption. In densely populated and industrialized regions, smart grid deployment is a strategic priority, reinforcing the need for advanced software tools that enable secure, reliable, and efficient energy delivery in complex environments.
Power System Analysis Software Market Key Trends & Opportunities
Transition Toward Cloud-Based Solutions
Cloud-based power system analysis software is gaining momentum due to its scalability, cost-effectiveness, and flexibility. Traditional on-premises systems require significant upfront investment, while cloud platforms offer subscription models and faster deployment. Users benefit from automatic updates, seamless remote access, and integration with other cloud-based tools. As utilities face increasing complexity in energy management, cloud-based analytics allow distributed teams to collaborate in real time. This model also supports disaster recovery and cybersecurity enhancements. Market players are expanding cloud-native offerings to serve small utilities and large grid operators alike. The shift opens opportunities for new entrants and SaaS-based models targeting underserved regional markets.
- For instance, Siemens offers its PSS®SINCAL power system analysis software through cloud-enabled deployments that support simulations with over 1 million grid elements.
Emergence of AI and Advanced Analytics
The integration of AI and machine learning into power system analysis tools presents a major opportunity. These technologies enhance forecasting accuracy, identify hidden patterns in load and fault data, and automate anomaly detection. AI-powered solutions enable predictive maintenance, reducing unplanned outages and operational costs. They also support decision-making in network planning by analyzing massive datasets with speed and precision. As grid operations grow more complex with the influx of renewables and electric vehicles, AI helps utilities adapt dynamically. Vendors increasingly embed advanced analytics in their platforms, creating a competitive edge and meeting the evolving needs of modern energy systems.

Power System Analysis Software Market Key Challenges
High Cost of Implementation and Integration
Despite long-term savings, the initial cost of deploying power system analysis software remains a significant barrier, especially for small utilities and operators in developing regions. Expenses include software licensing, system integration, staff training, and infrastructure upgrades. Customization to fit existing grid conditions and interoperability with legacy systems adds to the complexity. For cloud solutions, ongoing subscription fees and data security concerns may also deter adoption. Utilities with limited technical expertise face challenges in leveraging full capabilities, which may lead to underutilization. This financial burden slows down digital transformation, creating uneven adoption across geographies and utility sizes.
Cybersecurity and Data Privacy Concerns
As power grids become more digitized and interconnected, cybersecurity risks grow more severe. Power system analysis software often deals with sensitive operational data, and any breach could disrupt critical infrastructure. The use of cloud-based platforms increases vulnerability to attacks if security protocols are not robust. Utilities must comply with strict data protection regulations, adding complexity to deployment. Limited awareness and preparedness in some regions heighten the threat. Cyber threats like ransomware, phishing, and supply chain attacks force software vendors to invest heavily in secure architectures. Addressing these risks while maintaining software performance poses a key challenge for long-term growth.
Power System Analysis Software Market Regional Analysis
North America
North America led the Power System Analysis Software market in 2024, holding a dominant 35.8% revenue share with a value of USD 537.53 million, up from USD 445.26 million in 2018. The market is expected to reach USD 933.67 million by 2032, expanding at a CAGR of 7.3%. This growth is driven by grid modernization programs, high smart grid penetration, and increased investment in renewable integration and automation. The U.S. leads regional demand, supported by robust utility spending and government-backed digital transformation initiatives across transmission and distribution infrastructure.
Europe
Europe accounted for a 21.5% share of the Power System Analysis Software market in 2024, rising from USD 276.75 million in 2018 to USD 322.85 million. It is projected to reach USD 524.88 million by 2032, growing at a CAGR of 6.4%. The region benefits from strong regulatory frameworks promoting energy transition, smart metering deployment, and cross-border transmission planning. Countries such as Germany, France, and the UK are major contributors, as utilities adopt advanced analytics to support decentralized power generation and improve system reliability.
Asia Pacific
Asia Pacific held a 30% market share in 2024, reaching USD 450.73 million from USD 355.47 million in 2018. The region is expected to surge to USD 853.14 million by 2032, registering the fastest CAGR of 8.4%. Rapid urbanization, industrialization, and rising electricity consumption in countries like China, India, and Southeast Asia drive demand. Governments in the region invest heavily in transmission expansion, smart grid deployment, and renewable energy integration, creating strong growth opportunities for software providers focused on scalable and AI-enhanced power system analysis solutions.
Latin America
Latin America contributed 6.2% of the global market in 2024, growing from USD 76.26 million in 2018 to USD 92.28 million. The market is forecasted to reach USD 148.69 million by 2032 at a CAGR of 6.3%. Rising energy access programs, grid digitalization, and integration of distributed renewable sources support adoption in countries such as Brazil, Chile, and Colombia. Regional utilities are increasingly investing in load flow analysis and reliability tools to reduce energy losses and improve operational efficiency in aging grid infrastructures.
Middle East
The Middle East represented a 3.2% share of the market in 2024, increasing from USD 41.82 million in 2018 to USD 47.49 million. It is projected to reach USD 73.48 million by 2032 at a CAGR of 5.8%. Growing electricity demand from urban development and industrial expansion supports demand for advanced grid modeling tools. Gulf countries are modernizing grid systems to align with energy diversification strategies. Investments in renewable energy and smart city projects across Saudi Arabia and the UAE further boost regional software deployment.
Africa
Africa captured 3.5% of the global market in 2024, with market size rising from USD 34.44 million in 2018 to USD 52.32 million. The market is projected to reach USD 80.71 million by 2032, growing at a CAGR of 5.4%. Efforts to expand electricity access, improve transmission reliability, and integrate solar and hydro-based generation are key drivers. Countries such as South Africa, Kenya, and Egypt are gradually adopting power system analysis tools to support infrastructure development, manage distributed energy systems, and plan for long-term grid stability amid rising energy needs.
Power System Analysis Software Market Segmentations:
By Deployment:
- Cloud
- On-premises
By Application:
- Electric Power Distribution
- Electric Power Transmission
- Electric Power Generation
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa

Competitive Landscape
The Power System Analysis Software market features a mix of global technology leaders and specialized solution providers competing on innovation, scalability, and regional presence. Major players such as ABB Ltd., Siemens AG, and General Electric Company hold strong positions due to broad product portfolios, legacy client bases, and deep industry expertise. These companies continue investing in smart grid technologies, cloud-based platforms, and AI-powered analytics to maintain their edge. Meanwhile, firms like PSI AG, DIgSILENT GmbH, and Neplan AG offer niche and highly customizable software tailored to specific utility needs. Startups and regional players also gain traction through SaaS models and localized deployment. Strategic collaborations, acquisitions, and cloud migration support ongoing consolidation and diversification efforts. The competitive focus remains on enhancing simulation accuracy, interoperability with legacy systems, and integration with IoT and renewable infrastructure. Vendors that combine domain knowledge with strong technical capabilities are expected to sustain leadership in this evolving market.
Key Player Analysis
- ABB Ltd.
- General Electric Company
- Siemens AG
- PSI AG
- Eaton Corporation plc
- Unicorn Systems
- Open Systems International Inc. (OSI)
- Neplan AG
- Electrocon International Inc.
- Schneider Electric DMS NS
- DIgSILENT GmbH
Recent Developments
- In October 2022, ETAP, a provider of operation and automation solutions for electrical power systems, unveiled ETAP 22, an electrical digital twin solution, which empowers operators and engineers to operate, design, and automate safe, compliant, reliable power systems.
- In January 2022, PSI AG, an integrator and developer of software systems, released PSI Control 4.9 control system featuring new capabilities of protocol extension, allowing flexible management of the connections and parallel operations of control centers.
Report Coverage
The research report offers an in-depth analysis based on Deployment, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Cloud-based software adoption will continue to accelerate due to cost efficiency and scalability.
- AI and machine learning integration will improve forecasting and real-time grid decision-making.
- Utilities will increase spending on digital tools to support grid modernization and automation.
- Rising penetration of renewable energy will boost demand for advanced grid simulation solutions.
- Small and mid-sized utilities will adopt SaaS-based platforms for flexible deployment.
- Cybersecurity features will become a critical focus in software development and procurement.
- Governments will support digital infrastructure upgrades through energy transition policies.
- Regional vendors will expand through localized offerings and strategic partnerships.
- Power distribution applications will remain dominant with growing investment in smart grids.
- Demand will grow steadily in emerging markets due to electrification and infrastructure expansion.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Power System Analysis Software market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Power System Analysis Software market projected to grow between 2024 and 2032?
Which Power System Analysis Software market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Power System Analysis Software market?
Who are the leading companies in the Power System Analysis Software market?
Which region commanded the largest share of the Power System Analysis Software market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Power System Analysis Software Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Power System Analysis Software Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 1,503.20 million → 2032: USD 2,614.57 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Power System Analysis Software Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Power System Analysis Software Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Power System Analysis Software Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Power System Analysis Software Market Drivers
- 3.3 Power System Analysis Software Market Restraints & Challenges
- 3.4 Power System Analysis Software Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Power System Analysis Software Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Power System Analysis Software Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Power System Analysis Software category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Power System Analysis Software Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Power System Analysis Software Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Power System Analysis Software market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Power System Analysis Software Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Power System Analysis Software Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Power System Analysis Software Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Power System Analysis Software (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Power System Analysis Software Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Power System Analysis Software Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Power System Analysis Software Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Power System Analysis Software Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Power System Analysis Software Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Power System Analysis Software Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Power System Analysis Software Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Power System Analysis Software Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Power System Analysis Software Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
