
Refuse-Derived Fuel (RDF) Market Overview:
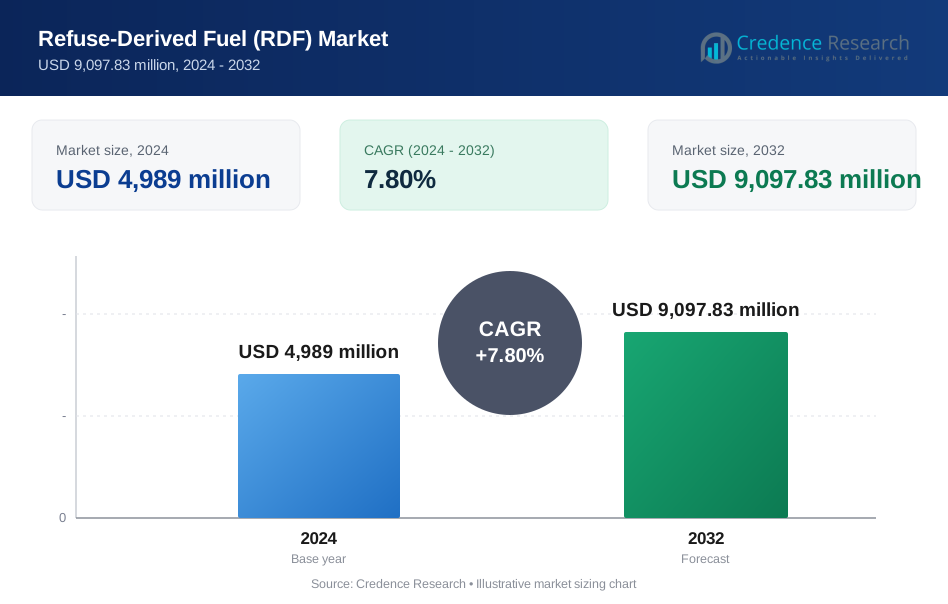
The Refuse-Derived Fuel (RDF) Market size was valued at USD 4,989 million in 2024 and is anticipated to reach USD 9097.83 million by 2032, at a CAGR of 7.8% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Refuse-Derived Fuel (RDF) Market Size 2024 | USD 4,989 million |
| Refuse-Derived Fuel (RDF) Market, CAGR | 7.8 % |
| Refuse-Derived Fuel (RDF) Market Size 2032 | USD 9097.83 million |
Refuse-Derived Fuel (RDF) Market Insights:
- Europe (~38%), Asia-Pacific (~32%), and North America (~22%) represent the top three regional shares due to strict landfill regulations, high municipal waste generation, mature waste-to-energy infrastructure, and strong demand from cement and power industries.
- Asia-Pacific (~32%) stands as the fastest-growing region, supported by rapid urbanization, expanding industrial base, rising waste volumes, and government investment in modern waste processing and alternative fuel infrastructure.
- By fuel type, fluff RDF (~48%) holds the largest share due to lower processing cost and ease of co-combustion, while pelletized and briquetted RDF (~52% combined) gain traction for higher energy density and improved handling efficiency.
- By end user, cement manufacturing (~44%) dominates segment share due to high thermal demand and fuel flexibility, followed by power generation and industrial boilers (~36% combined) supported by decarbonization targets and fuel cost optimization.

Refuse-Derived Fuel (RDF) Market Drivers:
Rising Regulatory Pressure to Reduce Landfill Dependency and Emissions
The Refuse-Derived Fuel (RDF) Market benefits from strict regulations that target landfill reduction and emission control. Governments enforce waste diversion mandates and carbon limits that favor fuel recovery over disposal. It supports compliance by converting non-recyclable waste into usable energy. Policy frameworks across developed and emerging economies continue to prioritize waste-to-energy pathways. These measures strengthen long-term demand for RDF across industrial users.
- For instance, Suez advanced its RDF production with Near-Infrared (NIR) sorting technology, processing 500,000 tons annually while cutting emissions by 40%.
Growing Industrial Demand for Cost-Effective Alternative Fuels
Industrial sectors increasingly seek fuel options that lower operating costs and reduce reliance on fossil resources, supporting the Refuse-Derived Fuel (RDF) Market. Cement plants, power generators, and district heating systems adopt RDF due to stable calorific value and supply security. It delivers predictable performance under controlled combustion conditions. Fuel substitution strategies align with corporate sustainability targets. Industrial uptake remains a central growth driver.
- For Instance, global co-processing technology, Heidelberg Materials' Zuari Cement plant in Andhra Pradesh, India, utilizes a state-of-the-art RDF processing line featuring UNTHA XR3000C shredders to achieve a 20 t/h throughput.
Escalating Municipal Solid Waste Generation Across Urban Regions
Rapid urban expansion and population growth reinforce the Refuse-Derived Fuel (RDF) Market by increasing waste feedstock availability. Municipalities face capacity constraints in landfills and waste transport systems. It enables efficient conversion of residual waste into energy value. Urban waste management strategies increasingly integrate RDF production. Feedstock consistency supports scalable fuel output.
Advancements in Waste Processing and Fuel Quality Optimization
Technological progress strengthens the Refuse-Derived Fuel (RDF) Market through improved sorting, shredding, and homogenization systems. Modern mechanical biological treatment enhances fuel consistency and combustion efficiency. It meets stringent quality specifications required by industrial end users. Automation and process control reduce contamination risks. Technology investment improves operational reliability and market confidence.
Refuse-Derived Fuel (RDF) Market Trends:
Integration of RDF Within Industrial Decarbonization and Fuel Substitution Strategies
The Refuse-Derived Fuel (RDF) Market shows a clear trend toward deeper integration within industrial decarbonization programs. Heavy industries prioritize fuel substitution to reduce carbon exposure and manage energy costs. It gains preference due to compatibility with existing combustion systems, particularly in cement kilns and thermal plants. Long-term offtake agreements between RDF producers and industrial users increase supply certainty. Corporate sustainability targets reinforce demand for alternative fuels with lower lifecycle emissions. Regulatory disclosure requirements push industries to document fuel transitions. This alignment supports consistent market expansion.
- For instance, Heidelberg Materials at its German facility signed a 10-year RDF supply deal, utilizing 200,000 tonnes per year to maintain stable combustion efficiency.
Shift Toward Advanced Processing, Quality Standardization, and Regional Supply Hubs
Operational sophistication defines the evolving Refuse-Derived Fuel (RDF) Market landscape across developed and emerging regions. Producers focus on advanced sorting, drying, and pelletization to deliver uniform fuel quality. It benefits from standardization initiatives that align RDF specifications with industrial performance requirements. Regional RDF hubs emerge near urban waste centers to reduce logistics costs and ensure feedstock continuity. Public-private partnerships support infrastructure development and long-term capacity planning. Investment interest rises due to predictable demand profiles. Market participants prioritize scale and reliability over fragmented production models.
- For instance, Jinjiang Environment in China leverages advanced pyrolysis systems to convert scheduled wastes into RDF with a net calorific value exceeding 18 MJ/kg, supporting large-scale industrial applications.
Refuse-Derived Fuel (RDF) Market Challenges Analysis:
Feedstock Variability and Operational Consistency Constraints
The Refuse-Derived Fuel (RDF) Market faces persistent challenges related to inconsistent waste composition and feedstock quality. Municipal solid waste streams vary by region, season, and consumer behavior. It complicates sorting and processing efficiency at treatment facilities. Fuel calorific value and moisture levels often fluctuate beyond preferred industrial specifications. Quality variation limits acceptance among high-precision industrial users. Operational adjustments increase processing costs. These constraints affect supply reliability.
Regulatory Complexity and Infrastructure Capital Intensity
Policy fragmentation across jurisdictions challenges the Refuse-Derived Fuel (RDF) Market with uneven compliance requirements. Permitting processes for waste processing and combustion facilities remain complex and time intensive. It increases project development timelines and financial risk. High capital requirements for advanced treatment, emission control, and logistics infrastructure restrict new market entry. Financing depends on long-term offtake security and policy stability. Limited public acceptance in certain regions further slows facility approvals.
Refuse-Derived Fuel (RDF) Market Opportunities:
Expansion of Circular Economy Frameworks and Waste-to-Energy Mandates
The Refuse-Derived Fuel (RDF) Market gains strong opportunity from national circular economy policies and waste diversion targets. Governments promote material recovery and energy generation from residual waste. It aligns with landfill reduction goals and emission control strategies. Public authorities support long-term supply contracts for recovered fuels. Policy incentives encourage private investment in processing capacity. Municipal partnerships strengthen feedstock access. Regulatory clarity improves project bankability.
Industrial Decarbonization Demand and Emerging Market Adoption
Industrial decarbonization initiatives create new opportunity for the Refuse-Derived Fuel (RDF) Market across energy-intensive sectors. Cement, steel, and power producers seek alternatives to coal and petroleum coke. It provides cost stability and measurable emission reduction. Emerging economies invest in waste management infrastructure to support urban growth. Regional supply hubs support efficient distribution. Cross-border technology transfer accelerates market penetration.
Refuse-Derived Fuel (RDF) Market Segmentation Analysis:
By Fuel Type
The Refuse-Derived Fuel (RDF) Market segments by fuel type into fluff RDF, pelletized RDF, and densified briquettes, each serving distinct industrial needs. Fluff RDF holds strong adoption due to lower processing cost and suitability for co-combustion. Pelletized and briquetted forms support higher energy density and improved handling efficiency. It enables consistent combustion performance across industrial systems. Fuel form selection depends on logistics, storage, and combustion technology compatibility.
- For Instance, Enerkem Alberta Biofuels facility at the Edmonton Waste Management Centre was designed to process approximately 100,000 tonnes (Mg) per year of municipal solid waste (MSW) feedstock.
By Technology
Technology segmentation within the Refuse-Derived Fuel (RDF) Market includes mechanical biological treatment, thermal treatment, and advanced sorting systems. Mechanical biological treatment dominates due to effective separation and fuel homogenization. Thermal processing supports moisture reduction and calorific value improvement. It enhances fuel quality and operational reliability for industrial users. Automation and sensor-based sorting improve contamination control. Technology choice directly influences fuel consistency and regulatory compliance.
- For instance, Veolia’s VESTA facility in Rouen recovers approximately 325,000 tons of municipal waste annually.
By End-User
End-user segmentation of the Refuse-Derived Fuel (RDF) Market includes cement manufacturing, power generation, industrial boilers, and district heating facilities. Cement plants represent the largest share due to high thermal demand and flexible fuel acceptance. Power generation facilities adopt RDF for partial fuel substitution. It supports emission reduction targets and energy cost management. Industrial boilers show steady adoption in regions with strong waste infrastructure. End-user demand aligns with decarbonization strategies.
Segmentations:
By Fuel Type
- Fluff Refuse-Derived Fuel
- Pelletized Refuse-Derived Fuel
- Briquetted Refuse-Derived Fuel
By Technology
- Mechanical Biological Treatment
- Advanced Mechanical Sorting
- Thermal Drying and Conditioning
- Automated Optical and Sensor-Based Sorting
By End-User
- Cement Manufacturing
- Power Generation
- Industrial Boilers
- District Heating Systems
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
Europe and North America: Regulatory Maturity and Industrial Adoption
The Refuse-Derived Fuel (RDF) Market records strong penetration across Europe due to strict landfill diversion policies and advanced waste treatment infrastructure. Industrial users integrate RDF into cement kilns and district heating systems. It supports emission reduction targets and energy diversification strategies. Standardized fuel specifications improve operational confidence among end users. North America shows steady expansion supported by waste-to-energy mandates and landfill capacity constraints. Public and private investment strengthens regional processing capacity.
Asia-Pacific: Rapid Urbanization and Infrastructure Expansion
The Refuse-Derived Fuel (RDF) Market experiences accelerated growth in Asia-Pacific driven by urban population expansion and rising municipal waste volumes. Governments promote fuel recovery to reduce landfill dependence. It aligns with industrial growth in cement and power generation sectors. Developing economies invest in modern waste processing facilities. Policy frameworks increasingly support alternative fuel use. Regional partnerships enhance technology transfer and operational expertise.
Latin America, Middle East, and Africa: Emerging Adoption Landscape
The Refuse-Derived Fuel (RDF) Market gains momentum across Latin America and the Middle East due to increasing waste management reforms. Urban centers seek cost-effective solutions for residual waste treatment. It supports energy diversification goals in fuel-importing economies. Infrastructure development remains gradual but consistent. Africa shows early-stage adoption with pilot projects in major cities. Long-term potential depends on regulatory clarity and investment continuity.
Key Player Analysis:
- RenewEco Energy Ltd.
- GreenFuel Technologies
- Enviro-Power Solutions
- BioWaste Energy Corp.
- EarthCycle Industries
- Global RDF Group
- Waste2Energy Inc.
- CleanPath Energy
- TerraFuel Systems
- RecyclePower Holdings
Competitive Analysis:
The Refuse-Derived Fuel (RDF) Market features a competitive landscape shaped by integrated waste management firms, regional processors, and energy recovery specialists. Leading participants focus on long-term municipal contracts to secure consistent feedstock supply. It strengthens market position through investment in advanced sorting and fuel conditioning systems. Companies emphasize fuel quality, calorific stability, and regulatory compliance to meet industrial standards. Strategic partnerships with cement producers and power generators support demand stability. Capacity expansion near urban centers reduces logistics cost and improves supply reliability. Market players pursue operational scale to enhance margins and bidding competitiveness. Regional firms compete through localized expertise and regulatory alignment. Technological capability and contract tenure define differentiation. Competitive intensity remains moderate, with entry barriers tied to capital requirements, permitting complexity, and infrastructure access.
Recent Developments:
- In September 2024, Lumax Auto Technologies announced its agreement to acquire a majority stake in GreenFuel Technologies (also known as Greenfuel Energy Solutions), marking entry into the green and alternate fuels sector including CNG and hydrogen systems.
- In November 2024, Lumax Auto Technologies completed the acquisition of a 60% stake in GreenFuel Technologies for INR 153.09 crores through its subsidiary Lumax Resources Pvt Ltd.
Report Coverage:
The research report offers an in-depth analysis based on Fuel Type, Technology, End-User and Region. It details leading Market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current Market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven Market expansion in recent years. The report also explores Market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on Market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the Market.
Future Outlook:
- The Refuse-Derived Fuel (RDF) Market will benefit from sustained policy focus on landfill reduction and waste diversion across developed and emerging economies.
- Industrial decarbonization strategies will continue to increase RDF adoption within cement, power, and industrial heat applications.
- Governments will expand waste-to-energy frameworks that prioritize fuel recovery over disposal.
- Municipal authorities will strengthen public-private partnerships to secure long-term feedstock and processing capacity.
- Technology upgrades in sorting, drying, and fuel conditioning will improve consistency and industrial acceptance.
- Standardization of RDF quality specifications will support broader cross-regional trade and offtake agreements.
- Urbanization trends will ensure steady availability of municipal solid waste as a core input stream.
- Infrastructure investments near major cities will reduce logistics costs and improve supply reliability.
- Corporate sustainability reporting requirements will reinforce demand for alternative fuels with lower lifecycle emissions.
- Market participants will focus on scale, reliability, and regulatory alignment to sustain competitive advantage.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Regulatory Pressure to Reduce Landfill Dependency and Emissions
Strict landfill diversion mandates and emission control regulations in both developed and emerging economies are driving the adoption of RDF as a preferred alternative to landfill disposal. These policies incentivize the conversion of non-recyclable waste into usable fuel, supporting compliance and long-term demand.
Growing Industrial Demand for Cost-Effective Alternative Fuels
Industries such as cement manufacturing and power generation are increasingly substituting fossil fuels with RDF to lower operating costs and meet sustainability targets. RDF offers stable calorific value and supply security, making it attractive for large-scale industrial applications.
Escalating Municipal Solid Waste Generation Across Urban Regions
Rapid urbanization and population growth are increasing municipal solid waste volumes, providing abundant feedstock for RDF production. Municipalities are integrating RDF into waste management strategies to address landfill capacity constraints and extract energy value from residual waste.
Advancements in Waste Processing and Fuel Quality Optimization
Technological improvements in sorting, shredding, and homogenization are enhancing the consistency and quality of RDF, making it more suitable for industrial use. Automation and process control reduce contamination risks and improve operational reliability, boosting market confidence.
Expansion of Circular Economy Frameworks and Waste-to-Energy Mandates
National and regional policies promoting circular economy principles and waste-to-energy initiatives are encouraging investment in RDF infrastructure. These frameworks support long-term supply contracts and public-private partnerships, strengthening feedstock access and market growth.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size of the Refuse-Derived Fuel (RDF) Market and what value is expected by 2032?
What factors are driving growth in the Refuse-Derived Fuel (RDF) Market?
Which fuel type segment holds significant importance in the Refuse-Derived Fuel (RDF) Market?
Which end-user segment dominates the Refuse-Derived Fuel (RDF) Market?
Which region leads the Refuse-Derived Fuel (RDF) Market?
What future trends will influence the Refuse-Derived Fuel (RDF) Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-User
- 1.2.1 Cement Manufacturing
- 1.2.2 Power Generation
- 1.2.3 Industrial Boilers
- 1.2.4 District Heating Systems
- 1.3 By Fuel Type
- 1.3.1 Fluff Refuse-Derived Fuel
- 1.3.2 Pelletized Refuse-Derived Fuel
- 1.3.3 Briquetted Refuse-Derived Fuel
- 1.4 By Technology
- 1.4.1 Mechanical Biological Treatment
- 1.4.2 Advanced Mechanical Sorting
- 1.4.3 Thermal Drying and Conditioning
- 1.4.4 Automated Optical and Sensor-Based Sorting
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 4,989 million → 2032: USD 9,097.83 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Refuse-Derived Fuel (RDF) Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Refuse-Derived Fuel (RDF) Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Refuse-Derived Fuel (RDF) Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Refuse-Derived Fuel (RDF) Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Refuse-Derived Fuel (RDF) Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Refuse-Derived Fuel (RDF) Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Refuse-Derived Fuel (RDF) Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Refuse-Derived Fuel (RDF) Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 4,989 million → 2032: USD 9,097.83 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Refuse-Derived Fuel (RDF) Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Cement Manufacturing
- 12.3.7.2 Power Generation
- 12.3.7.3 Industrial Boilers
- 12.3.7.4 District Heating Systems
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Fuel Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Fluff Refuse-Derived Fuel
- 12.4.7.2 Pelletized Refuse-Derived Fuel
- 12.4.7.3 Briquetted Refuse-Derived Fuel
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Technology - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Mechanical Biological Treatment
- 12.5.7.2 Advanced Mechanical Sorting
- 12.5.7.3 Thermal Drying and Conditioning
- 12.5.7.4 Automated Optical and Sensor-Based Sorting
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Refuse-Derived Fuel (RDF) End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Refuse-Derived Fuel (RDF) Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Refuse-Derived Fuel (RDF) Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Refuse-Derived Fuel (RDF) Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Suez
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Veolia
- 18.4 Heidelberg Materials
- 18.5 Jinjiang Environment
- 18.6 Enerkem
- 18.7 RenewEco Energy Ltd.
- 18.8 GreenFuel Technologies
- 18.9 Enviro-Power Solutions
- 18.10 BioWaste Energy Corp.
- 18.11 Waste2Energy Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

