
Market Overview:
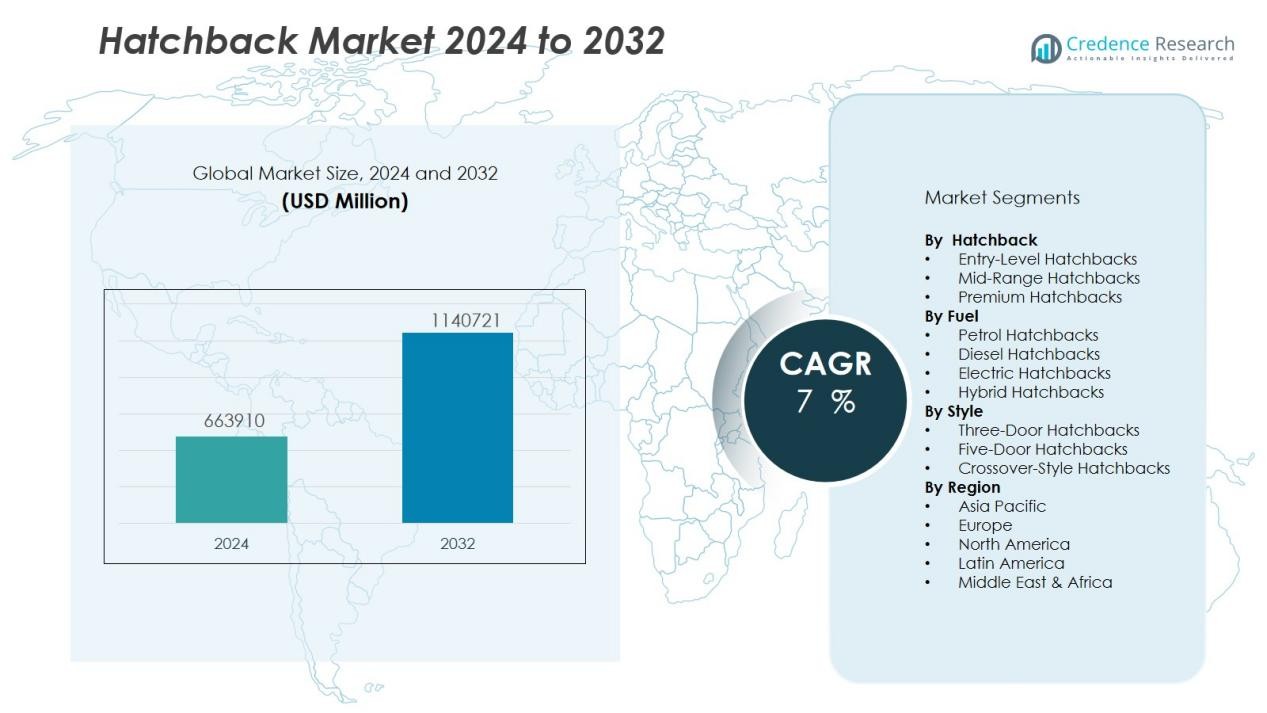
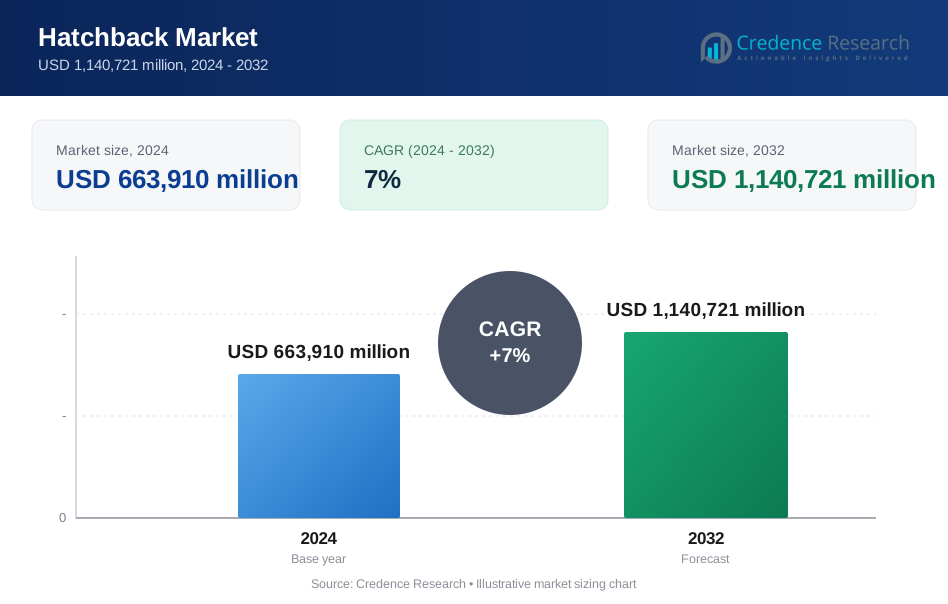
The hatchback market size was valued at USD 663910 million in 2024 and is anticipated to reach USD 1140721 million by 2032, at a CAGR of 7 % during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Hatchback Market Size 2024 | USD 663910 Million |
| Hatchback Market, CAGR | 7 % |
| Hatchback Market Size 2032 | USD 1140721 Million |
Market growth is primarily fueled by rising demand for affordable, fuel-efficient vehicles, especially in densely populated cities. Increasing adoption of electric and hybrid hatchbacks, supported by government incentives and emission regulations, is expanding the customer base. Additionally, continuous innovations in infotainment systems, driver-assistance technologies, and customizable interiors have strengthened the hatchback’s position in both developed and emerging markets. Competitive pricing and strong resale value further bolster demand in this segment.
Regionally, Asia-Pacific dominates the hatchback market due to high sales volumes in countries such as India, Japan, and China, supported by a strong preference for small cars and growing middle-class purchasing power. Europe follows closely, driven by demand for compact, efficient vehicles in urban areas, while North America exhibits moderate growth, supported by the increasing introduction of crossover-style hatchbacks.
Market Insights:
- The hatchback market was valued at USD 663,910 million in 2024 and is projected to reach USD 1,140,721 million by 2032, registering a CAGR of 7% from 2024 to 2032.
- Rising demand for affordable, fuel-efficient vehicles, particularly in urban and high-density areas, remains a core growth driver.
- Expanding adoption of electric and hybrid hatchbacks, supported by government incentives and emission compliance policies, is strengthening the segment’s long-term outlook.
- Advancements in infotainment systems, driver-assistance technologies, and customizable interiors are enhancing product appeal in both developed and emerging markets.
- Competitive pricing, strong resale value, and attractive financing schemes continue to secure customer loyalty and expand the buyer base.
- Asia-Pacific leads with 48.6% market share, followed by Europe at 27.4% and North America at 15.9%, each driven by distinct consumer and regulatory trends.
- Growing competition from compact SUVs and crossovers, coupled with rising production costs due to safety and emission requirements, remains a critical challenge for manufacturers.
Market Drivers:
Growing Demand for Compact and Fuel-Efficient Vehicles:
Urbanization and rising congestion levels have increased consumer preference for compact, fuel-efficient cars. The hatchback market benefits from its ability to offer maneuverability, reduced parking space requirements, and lower running costs. Consumers in metropolitan regions increasingly opt for hatchbacks due to their practicality without compromising passenger comfort. Manufacturers are focusing on improving engine efficiency to meet stringent emission norms while maintaining performance. This combination of affordability and convenience continues to drive strong demand globally.
- For instance, Toyota’s Yaris 1.5 HEV 130 achieved an average urban fuel consumption of 2.9 L/100 km (81.1 mpg US) in real-world city tests.
Advancements in Electric and Hybrid Hatchback Models:
The shift toward sustainable mobility has accelerated the adoption of electric and hybrid hatchbacks. Governments worldwide provide tax benefits, purchase subsidies, and charging infrastructure support to encourage eco-friendly vehicle purchases. It is also supported by automakers investing in long-range battery technology, faster charging solutions, and improved energy efficiency. These developments have expanded the appeal of hatchbacks to environmentally conscious buyers. The segment’s adaptability to electrification positions it well in the evolving automotive landscape.
- For instance, Toyota debuted the 2026 C-HR Battery Electric Vehicle, which features a 74.7kWh lithium-ion battery, a manufacturer-estimated all-electric range of 290 miles, and the ability to charge from 10–80% in around 30 minutes using DC fast-charging.
Enhanced Safety, Connectivity, and Comfort Features:
Consumers expect modern vehicles to deliver advanced safety systems, seamless connectivity, and high comfort levels. The hatchback segment integrates features such as adaptive cruise control, lane-keeping assistance, and smartphone-based infotainment systems. It attracts buyers seeking value through technology-rich offerings at competitive prices. Upgraded cabin materials, noise insulation, and ergonomic seating designs enhance the driving experience. This blend of safety, convenience, and comfort reinforces brand loyalty.
Competitive Pricing and Strong Resale Value:
Affordability remains a decisive factor for buyers in both developed and emerging markets. The hatchback market retains strong resale value due to consistent demand and lower depreciation rates compared to larger vehicles. It appeals to budget-conscious customers who prioritize long-term value alongside upfront savings. Attractive financing schemes and promotional offers by manufacturers further stimulate sales. The balance of price competitiveness and investment security sustains the segment’s growth momentum.
Market Trends:
Rising Popularity of Electrified and Performance-Oriented Hatchbacks:
The hatchback market is witnessing a surge in demand for electric, hybrid, and performance-oriented models. Automakers are introducing battery-electric hatchbacks with extended driving ranges, faster charging capabilities, and competitive pricing to attract eco-conscious buyers. It is also seeing an increase in hot hatch variants that combine compact practicality with high-performance engines, sport-tuned suspensions, and advanced aerodynamics. This dual appeal of sustainability and performance expands the segment’s reach to both green mobility enthusiasts and driving purists. Stronger investments in battery technology and lightweight materials enhance efficiency without compromising structural safety. These developments are reshaping consumer perceptions, positioning hatchbacks as versatile vehicles that meet diverse lifestyle needs.
- For instance, the Renault Zoe ZE50 features a 52 kWh battery pack providing up to 245 miles of WLTP range and supports 50 kW DC charging that replenishes 80% capacity in 70 minutes.
Integration of Advanced Technology and Personalization Features:
Automakers are embedding advanced driver-assistance systems, AI-powered infotainment, and connected car technologies into modern hatchbacks. It enables seamless smartphone integration, over-the-air software updates, and real-time navigation services, appealing to tech-savvy customers. The market is also experiencing a rise in personalization options, including customizable interiors, exterior finishes, and performance packages. Manufacturers leverage data analytics to predict customer preferences and tailor offerings to specific markets. Enhanced comfort features such as improved cabin ergonomics, noise reduction, and climate control systems further elevate user experience. This convergence of technology and personalization strengthens brand differentiation and customer loyalty in an increasingly competitive landscape.
- For instance, Tesla's Model Y incorporates a 15.4-inch touchscreen with AI-powered learning algorithms that adapt to user preferences and driving patterns.
Market Challenges Analysis:
Intensifying Competition from SUVs and Crossovers:
The hatchback market faces growing pressure from the rising popularity of compact SUVs and crossovers, which offer higher ground clearance, a commanding driving position, and perceived versatility. Consumer preference is gradually shifting toward these segments, particularly in urban and semi-urban areas. It challenges hatchback sales despite their advantages in fuel efficiency and maneuverability. Automakers must invest in differentiated styling, advanced features, and value-driven pricing to maintain market share. The competitive environment requires constant innovation to prevent customer migration. Failure to adapt could reduce the segment’s relevance in key markets.
Regulatory Pressures and Rising Production Costs:
Stricter emission norms and safety regulations are increasing the cost of manufacturing hatchbacks, impacting affordability in price-sensitive markets. The adoption of advanced safety systems, lightweight materials, and electrified powertrains adds to production expenses. It forces manufacturers to balance compliance with competitive pricing without compromising quality. Supply chain disruptions and fluctuating raw material costs further strain profitability. Meeting environmental targets while retaining mass-market appeal remains a critical challenge. The segment must navigate these pressures while sustaining consumer interest and brand loyalty.
Market Opportunities:
Expansion of Electric and Hybrid Hatchback Segment:
The hatchback market holds significant potential in the electrification space, with growing consumer interest in eco-friendly mobility solutions. Governments are incentivizing electric and hybrid vehicle adoption through subsidies, tax benefits, and charging infrastructure investments. It allows manufacturers to position hatchbacks as affordable entry points into the electric vehicle market. Compact size, lower weight, and aerodynamic efficiency make hatchbacks ideal platforms for electrified powertrains. Emerging markets offer untapped demand, especially where small cars dominate urban mobility. Strategic partnerships in battery technology and charging solutions can accelerate adoption.
Rising Demand for Connected and Customizable Models:
Increasing consumer appetite for advanced technology integration presents strong growth opportunities. Hatchbacks equipped with AI-driven infotainment, advanced driver-assistance systems, and seamless connectivity appeal to tech-savvy buyers. It enables automakers to offer personalized driving experiences through customizable interiors, trims, and performance packages. Digital retail channels also open new avenues for targeted marketing and direct-to-consumer sales. Growing interest in stylish, feature-rich compact cars among younger demographics supports premiumization within the segment. Leveraging these trends can enhance brand positioning and profitability
Market Segmentation Analysis:
By Hatchback:
The hatchback market is segmented into entry-level, mid-range, and premium models. Entry-level hatchbacks dominate due to affordability, low maintenance costs, and suitability for first-time buyers. Mid-range models attract urban professionals seeking better performance, enhanced interiors, and advanced safety features. Premium hatchbacks target niche customers with performance-tuned engines, luxury finishes, and cutting-edge technology. It benefits from broad coverage across income groups, enabling manufacturers to cater to diverse consumer segments.
- For instance, Xpeng achieved a 97% OTA update adoption rate in just 10 days after launching 40 new cabin functions and 200 user experience optimizations in early 2021, allowing owners to personalize features rapidly.
By Fuel:
The market includes petrol, diesel, electric, and hybrid hatchbacks. Petrol variants lead in sales, driven by lower initial costs and wide availability in most markets. Diesel hatchbacks hold a smaller but consistent share in regions with higher mileage requirements. Electric and hybrid models are gaining momentum, supported by emission regulations, government incentives, and advancements in battery technology. It positions the segment for long-term growth in the sustainable mobility space.
- For instance, BMW Group posted record sales of electric and hybrid vehicles in 2023, delivering 2,555,341 units globally-representing a 6.5% increase year-over-year and improved penetration in sustainable mobility.
By Style:
Hatchbacks are offered in three-door and five-door configurations. Five-door models dominate global sales, offering better accessibility and practicality for families. Three-door variants appeal to younger buyers and enthusiasts who prioritize sportier styling. The market also sees rising demand for crossover-style hatchbacks, blending SUV-inspired design with compact efficiency. It allows automakers to address shifting consumer preferences while retaining the core benefits of hatchback practicality.
Segmentations:
By Hatchback:
- Entry-Level Hatchbacks
- Mid-Range Hatchbacks
- Premium Hatchbacks
By Fuel:
- Petrol Hatchbacks
- Diesel Hatchbacks
- Electric Hatchbacks
- Hybrid Hatchbacks
By Style:
- Three-Door Hatchbacks
- Five-Door Hatchbacks
- Crossover-Style Hatchbacks
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
Asia-Pacific :
Asia-Pacific accounts for 48.6% market share, driven by high demand in India, Japan, and China. Rapid urbanization, dense population centers, and rising disposable incomes sustain the dominance of this region. The hatchback market benefits from the preference for compact, fuel-efficient models suited to congested urban environments. It is further supported by government incentives for electric and hybrid variants, particularly in China and Japan. Manufacturers are expanding production capacities and launching region-specific models to meet diverse consumer preferences. Strong dealer networks and competitive pricing strategies reinforce long-term growth potential.
Europe :
Europe holds 27.4% market share, supported by stringent emission regulations and a well-established urban mobility culture. The region’s consumers favor hatchbacks for their practicality, fuel efficiency, and suitability for narrow streets. The hatchback market in Europe is evolving with a shift toward electric and hybrid powertrains in line with EU decarbonization goals. Automakers leverage advanced safety technologies, premium interiors, and customizable features to attract buyers. It benefits from consistent demand in countries such as Germany, France, and the UK. Government incentives and investments in EV charging infrastructure further enhance market expansion.
North America :
North America commands 15.9% market share, with growth driven by younger buyers seeking affordable, stylish, and tech-equipped compact cars. The market is gradually diversifying with crossover-style hatchbacks that appeal to SUV-oriented consumers while retaining compact practicality. It benefits from increasing adoption of fuel-efficient models as fuel prices fluctuate. Automakers are focusing on infotainment-rich cabins, sporty designs, and flexible financing plans to strengthen demand. The segment’s expansion is aided by targeted marketing strategies and broader dealership coverage. Electric and hybrid hatchback launches are expected to further boost regional adoption.
Key Player Analysis:
Competitive Analysis:
The hatchback market is characterized by intense competition among global automakers that leverage brand strength, innovation, and extensive distribution networks to secure market share. Leading players such as Chevrolet, Ford, Honda, Hyundai, Kia, Mitsubishi, and Nissan maintain strong positions through diverse product portfolios tailored to varying consumer needs. It is driven by continuous advancements in fuel efficiency, electrification, and connectivity features to meet evolving regulatory and customer demands. Manufacturers focus on balancing affordability with premium features to appeal to both entry-level and mid-range buyers. Competitive strategies include frequent model upgrades, localized production, and targeted marketing to strengthen brand loyalty. The market’s dynamic nature compels participants to invest in research, design, and technology integration to differentiate their offerings. Strategic emphasis on electric and hybrid hatchbacks, combined with value-driven pricing, positions leading brands to sustain growth in both mature and emerging regions.
Recent Developments:
- In August 2025, Honda officially launched the Fastport eQuad, an all-electric micromobility vehicle designed for last-mile delivery, which won a major Red Dot Design Award.
- In October 2024, Hyundai entered a multi-year partnership with Waymo to integrate Waymo’s autonomous technology into the all-electric Hyundai IONIQ 5 SUV, with fleet rollout and rider testing expected by late 2025.
- In June 2025, Ford launched the 2025 F-150, offering new engine options and advanced tech features.
Market Concentration & Characteristics:
The hatchback market exhibits moderate concentration, with leading global and regional manufacturers competing through brand strength, diverse model portfolios, and technological innovation. It is characterized by high product differentiation in terms of design, powertrain options, and feature integration. The segment caters to varied consumer groups, from budget-conscious buyers to premium-performance enthusiasts. Competitive dynamics are shaped by frequent model upgrades, aggressive pricing strategies, and strong aftersales support. Growing emphasis on electric and hybrid variants reflects a shift toward sustainable mobility. Regional preferences and regulatory requirements influence product development, creating a competitive environment that rewards adaptability and innovation.
Report Coverage:
The research report offers an in-depth analysis based on Hatchback, Fuel, Style and Region. It details leading Market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current Market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven Market expansion in recent years. The report also explores Market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on Market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the Market.
Future Outlook:
- The hatchback market will continue benefiting from rising urbanization and demand for compact, fuel-efficient vehicles.
- Automakers will expand electric and hybrid hatchback offerings to align with stricter emission regulations and consumer preference for sustainable mobility.
- Technological integration, including AI-powered infotainment and advanced driver-assistance systems, will enhance buyer appeal.
- Manufacturers will invest in lightweight materials and aerodynamic designs to improve performance and efficiency.
- Emerging markets will witness stronger adoption due to affordability, increasing middle-class incomes, and expanding urban infrastructure.
- Personalization trends will drive demand for customizable interiors, premium finishes, and tailored performance options.
- Crossover-style hatchbacks will attract buyers seeking SUV-like aesthetics with compact practicality.
- Strategic partnerships in battery technology and charging infrastructure will accelerate the adoption of electric hatchbacks.
- Competitive pricing and attractive financing schemes will remain key tools to capture budget-conscious segments.
- Strong emphasis on safety standards and comfort upgrades will sustain brand loyalty and long-term market growth.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Urbanization and Demand for Compact, Fuel-Efficient Vehicles
Increasing urban congestion and limited parking in cities are driving consumers toward compact, fuel-efficient hatchbacks that offer maneuverability and lower running costs, making them ideal for metropolitan environments.
Adoption of Electric and Hybrid Hatchbacks
Government incentives, emission regulations, and advancements in battery technology are accelerating the adoption of electric and hybrid hatchbacks, expanding the market to environmentally conscious buyers and supporting long-term growth.
Technological Advancements in Safety and Connectivity
Integration of advanced infotainment systems, driver-assistance technologies, and customizable interiors is enhancing the appeal of hatchbacks, attracting tech-savvy consumers and differentiating products in a competitive market.
Competitive Pricing and Strong Resale Value
Hatchbacks maintain strong resale value and are often priced competitively, appealing to budget-conscious buyers and first-time car owners, which sustains steady demand across both developed and emerging markets.
Expansion of Crossover-Style and Performance Hatchbacks
The introduction of crossover-inspired and performance-oriented hatchbacks is broadening the segment’s appeal, attracting buyers who seek a blend of sporty aesthetics, practicality, and enhanced driving dynamics.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the hatchback market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the hatchback market projected to grow between 2024 and 2032?
Which hatchback market segment held the largest share in 2024?
What are the primary factors fueling the growth of the hatchback market?
Who are the leading companies in the hatchback market?
Which region commanded the largest share of the hatchback market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Fuel
- 1.2.1 Petrol Hatchbacks
- 1.2.2 Diesel Hatchbacks
- 1.2.3 Electric Hatchbacks
- 1.2.4 Hybrid Hatchbacks
- 1.3 By Style
- 1.3.1 Three-Door Hatchbacks
- 1.3.2 Five-Door Hatchbacks
- 1.3.3 Crossover-Style Hatchbacks
- 1.4 By Hatchback
- 1.4.1 Entry-Level Hatchbacks
- 1.4.2 Mid-Range Hatchbacks
- 1.4.3 Premium Hatchbacks
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 663,910 million → 2032: USD 1,140,721 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Hatchback Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Hatchback Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Hatchback Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Hatchback Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Hatchback Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Hatchback Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Hatchback Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Hatchback Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 663,910 million → 2032: USD 1,140,721 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Hatchback Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Fuel - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Petrol Hatchbacks
- 12.3.7.2 Diesel Hatchbacks
- 12.3.7.3 Electric Hatchbacks
- 12.3.7.4 Hybrid Hatchbacks
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Style - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Three-Door Hatchbacks
- 12.4.7.2 Five-Door Hatchbacks
- 12.4.7.3 Crossover-Style Hatchbacks
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Hatchback - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Entry-Level Hatchbacks
- 12.5.7.2 Mid-Range Hatchbacks
- 12.5.7.3 Premium Hatchbacks
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Hatchback Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Hatchback Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Hatchback Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Honda
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Chevrolet
- 17.4 Hyundai
- 17.5 Ford
- 17.6 Kia
- 17.7 Nissan
- 17.8 Mitsubishi
- 17.9 Toyota
- 17.10 Stellantis
- 17.11 Volkswagen
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

