
Market Overview:
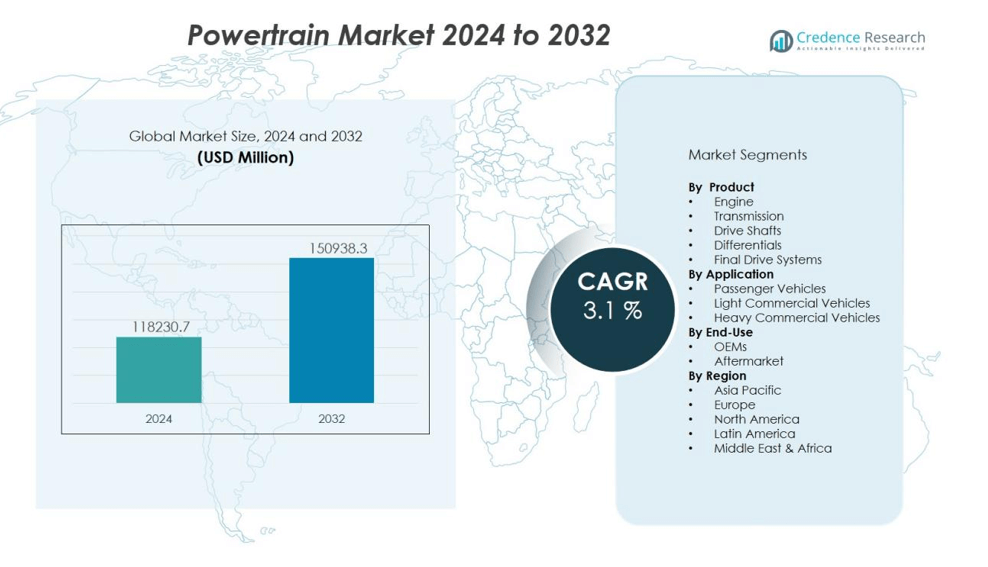
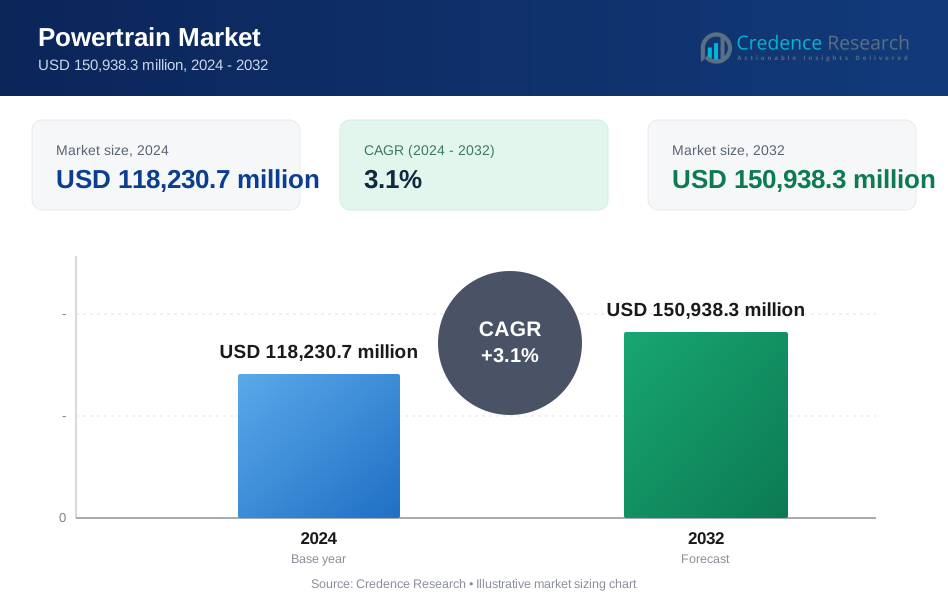
The powertrain market size was valued at USD 118230.7 million in 2024 and is anticipated to reach USD 150938.3 million by 2032, at a CAGR of 3.1 % during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Powertrain Market Size 2024 | USD 118230.7 million |
| Powertrain Market, CAGR | 3.1% |
| Powertrain Market Size 2032 | USD 150938.3 million |
Key market drivers include stringent emission norms worldwide, the rapid adoption of electric mobility, and consumer demand for high-performance and fuel-efficient vehicles. Automakers are increasingly focusing on lightweight materials, advanced transmission systems, and electrification technologies to meet environmental and efficiency targets. Integration of digital control systems and enhanced thermal management solutions further boosts efficiency, while government incentives for electric vehicles accelerate the shift toward sustainable powertrain solutions.
Regionally, Asia-Pacific dominates the global powertrain market, supported by high vehicle production in China, Japan, and India, coupled with strong EV adoption policies. Europe remains a key market due to strict environmental regulations and rapid electrification initiatives, while North America benefits from robust technological innovation and growing demand for hybrid and electric vehicles.
Market Insights:
- The powertrain market was valued at USD 118,230.7 million in 2024 and is expected to reach USD 150,938.3 million by 2032, growing at a CAGR of 3.1%.
- Stringent global emission norms such as Euro 7, CAFE, and China VI are driving investment in hybrid and electric powertrain systems.
- Rising adoption of electric and hybrid vehicles is boosting demand for advanced battery technologies, efficient motors, and flexible vehicle platforms.
- Automakers are focusing on lightweight materials, optimized transmissions, and improved aerodynamics to balance efficiency with performance.
- Integration of AI, machine learning, and connected systems is enabling predictive maintenance, real-time optimization, and enhanced compatibility with autonomous vehicles.
- Asia-Pacific leads with 52% market share, supported by strong EV policies, high vehicle production, and a robust supply chain ecosystem.
- Europe and North America are expanding through strict emission regulations, advanced R&D capabilities, and rising consumer demand for low-emission mobility solutions.
Market Drivers:
Stringent Emission Regulations Driving Technological Advancements:
The powertrain market is experiencing significant transformation due to tightening global emission regulations. Governments are enforcing stricter standards such as Euro 7, CAFE, and China VI, compelling manufacturers to adopt cleaner and more efficient technologies. It is prompting increased investment in hybrid and electric powertrain systems to reduce greenhouse gas emissions. Automakers are integrating advanced combustion techniques, turbocharging, and aftertreatment systems to meet compliance targets without compromising performance. This regulatory pressure is accelerating innovation and reshaping product development strategies.
- For instance, Bosch’s latest diesel powertrain technology has enabled vehicles to achieve average real driving nitrogen oxide (NOx) emissions as low as 13mg/km-just one-tenth of the Euro 6 limit-thanks to innovations in injection systems and exhaust-gas treatment.
Rising Demand for Electric and Hybrid Vehicles:
Global interest in electric and hybrid vehicles is a major catalyst for growth in the powertrain market. It is driving rapid advancements in battery technology, electric motors, and power electronics to deliver improved efficiency and extended driving ranges. Consumer awareness of environmental concerns, coupled with government incentives, is influencing purchasing decisions toward low-emission mobility solutions. Automakers are developing flexible platforms capable of supporting multiple powertrain configurations to meet diverse market demands. This shift is fostering a competitive landscape where technological differentiation is essential.
- For instance, Tesla Model S Plaid’s tri-motor 760 kW powertrain achieves 0–60 mph in just 1.98 seconds.
Focus on Fuel Efficiency and Performance Optimization:
Fuel efficiency remains a core priority, with the powertrain market leveraging lightweight materials, advanced transmission designs, and optimized engine calibration. It is enabling manufacturers to balance stringent efficiency requirements with customer expectations for high performance. Variable valve timing, cylinder deactivation, and improved aerodynamics are increasingly common in modern powertrain systems. Manufacturers are also enhancing driveline integration to reduce energy losses and maximize output. These innovations are strengthening product competitiveness across global markets.
Integration of Digital and Intelligent Control Systems:
The adoption of digital technologies is redefining operational capabilities within the powertrain market. It is enabling predictive maintenance, real-time performance monitoring, and adaptive control strategies through advanced software. Connected systems are facilitating over-the-air updates and enhancing compatibility with autonomous driving technologies. Integration of artificial intelligence and machine learning is improving system responsiveness and efficiency. This digital evolution is positioning powertrain solutions for the next phase of intelligent mobility.
Market Trends:
Electrification and Hybridization Reshaping Product Portfolios:
The powertrain market is undergoing a fundamental shift toward electrification and hybridization, with manufacturers expanding offerings to include battery electric, plug-in hybrid, and fuel cell systems. It is influencing supply chains, component design, and manufacturing processes to align with sustainable mobility goals. The focus is on developing scalable architectures that can accommodate multiple propulsion types without significant redesign. Battery technology improvements, such as higher energy density and faster charging, are supporting wider adoption. Automakers are also prioritizing cost reduction to make electric powertrains more competitive with internal combustion options. Partnerships between OEMs and technology firms are accelerating innovation in this segment. The transition is positioning manufacturers to capture emerging demand in both mature and developing markets.
- For instance, Tesla achieved production of over 1.77 million electric vehicles globally in 2024, with their 4680 battery cells reaching over 50 million units produced at Gigafactory Texas by June 2024.
Advanced Materials and Intelligent Systems Enhancing Efficiency:
The integration of advanced materials and intelligent systems is becoming a defining trend in the powertrain market. It is driving weight reduction, thermal efficiency, and improved durability across various propulsion technologies. Lightweight composites, high-strength alloys, and innovative lubrication solutions are enabling better performance while meeting environmental standards. Intelligent control systems are optimizing torque distribution, energy recovery, and power delivery based on driving conditions. Over-the-air software updates are extending product lifecycles and maintaining regulatory compliance. The combination of material science and digital intelligence is delivering higher efficiency and reliability. This convergence is establishing a new benchmark for competitiveness in global automotive manufacturing.
- For instance, Volkswagen’s ID.4 utilizes hot-formed boron steel in its body-in-white, boosting torsional stiffness by 25 percent, while an over-the-air calibration tweak to its drive inverter reduced energy losses by 1.8 percent.
Market Challenges Analysis:
High Development Costs and Complex Regulatory Compliance:
The powertrain market faces significant challenges due to the high costs associated with research, development, and compliance. It is becoming increasingly expensive to design systems that meet stringent global emission and efficiency standards. Manufacturers must invest heavily in advanced materials, precision engineering, and new manufacturing capabilities to remain competitive. Diverse regulatory requirements across regions add complexity, requiring multiple adaptations of the same platform. The financial burden is particularly high for smaller players with limited capital. This dynamic is driving consolidation and strategic alliances within the industry.
Technological Transition and Supply Chain Disruptions:
The rapid shift toward electrification is creating technological and operational hurdles in the powertrain market. It demands a complete transformation of supply chains, with increased dependence on rare earth elements, advanced electronics, and battery components. Shortages of critical materials and geopolitical uncertainties are disrupting production schedules. The pace of technological change also increases the risk of product obsolescence, pressuring manufacturers to accelerate development cycles. Skilled labor shortages in software, electronics, and advanced manufacturing are intensifying competition for talent. These factors are challenging the ability of companies to scale efficiently while maintaining profitability.
Market Opportunities:
Expansion in Electric and Hybrid Vehicle Segments:
The powertrain market holds significant opportunities in the expanding electric and hybrid vehicle segments. It benefits from increasing government incentives, rising fuel costs, and growing environmental awareness among consumers. Demand for high-efficiency, low-emission mobility solutions is encouraging investment in advanced battery systems, electric motors, and integrated power electronics. Automakers can leverage modular and flexible platforms to cater to both developed and emerging markets. Collaboration with technology providers enables faster deployment of next-generation powertrains. This segment offers long-term growth potential as electrification becomes mainstream across global markets.
Advancements in Connected and Intelligent Powertrain Systems:
Integration of connectivity and intelligent control systems is creating new avenues for value creation in the powertrain market. It enables predictive maintenance, remote diagnostics, and real-time optimization of performance, enhancing customer satisfaction and operational efficiency. The adoption of AI and machine learning supports adaptive energy management and seamless integration with autonomous driving technologies. Lightweight materials combined with advanced analytics can deliver both performance gains and sustainability benefits. Expanding adoption in commercial fleets presents opportunities for efficiency-driven solutions. This trend is positioning manufacturers to lead in the era of intelligent and sustainable mobility.
Market Segmentation Analysis:
By Product:
The powertrain market is segmented into engine, transmission, drive shafts, differentials, and final drive systems. It covers both internal combustion engine (ICE) and electrified powertrains, including hybrid and fully electric systems. Demand for advanced engines with turbocharging, direct injection, and variable valve timing remains strong, while electric powertrains are gaining market share through improved battery and motor technologies. Transmissions are evolving toward multi-speed and continuously variable systems to enhance fuel efficiency. Drive shafts and differentials are being optimized for lightweight performance and durability.
- For instance, ZF Friedrichshafen’s elecTrac front e-axle delivers 160 kW of peak power and 300 Nm of torque in a 28 kg unit, achieving a 97% efficiency rating and reducing system weight by 15%.
By Application:
Applications span passenger vehicles, light commercial vehicles, and heavy commercial vehicles. The passenger vehicle segment leads due to high production volumes and strong consumer demand for fuel-efficient and high-performance vehicles. It benefits from the rapid integration of hybrid and electric technologies. Light commercial vehicles are focusing on durability, load capacity, and cost efficiency, while heavy commercial vehicles emphasize torque delivery and fuel optimization.
- For instance, toyota’s prius models have delivered more than a 10% fuel efficiency improvement with each generation, and the brand surpassed 10 million global hybrid vehicle sales by 2021, demonstrating large-scale technological advancement.
By End-Use:
End-use segments include OEMs and aftermarket. OEMs dominate due to large-scale production and integration of advanced technologies at the manufacturing stage. It is driving innovation through collaborations with technology providers and material suppliers. The aftermarket segment is expanding, driven by maintenance, repair, and replacement needs, especially for aging ICE fleets. Growth in electric and hybrid models is creating opportunities for specialized aftermarket services and components.
Segmentations:
By Product:
- Engine
- Transmission
- Drive Shafts
- Differentials
- Final Drive Systems
By Application:
- Passenger Vehicles
- Light Commercial Vehicles
- Heavy Commercial Vehicles
By End-Use:
- OEMs
- Aftermarket
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis:
Asia-Pacific :
Asia-Pacific holds 52% market share in the global powertrain market, supported by its position as the largest automotive manufacturing hub. China, Japan, and India drive the region’s dominance through high production volumes and rapid electric vehicle adoption. It benefits from strong government incentives, expanding charging infrastructure, and competitive manufacturing costs. Local suppliers are enhancing capabilities in both internal combustion and electric powertrains to meet diverse demand. The presence of major automakers and battery manufacturers strengthens the supply chain ecosystem. Regional growth is further supported by rising consumer demand for fuel-efficient and low-emission vehicles.
Europe :
Europe accounts for 26% market share, driven by stringent environmental regulations and aggressive electrification strategies. The European Union’s emission standards are accelerating adoption of hybrid and fully electric powertrain technologies. It is fostering significant R&D investment in lightweight materials, advanced transmissions, and battery efficiency. Leading automotive nations such as Germany, France, and the UK are focusing on premium, high-performance, and sustainable mobility solutions. Collaborative initiatives between governments, research institutions, and automakers are promoting innovation. The region’s mature automotive industry and strong engineering expertise provide a competitive advantage.
North America :
North America holds 18% market share, supported by robust technological innovation and growing interest in hybrid and electric vehicles. The United States leads regional development with strong investments in advanced propulsion technologies. It is witnessing rapid integration of intelligent control systems, AI-driven performance optimization, and connected vehicle solutions. Consumer demand for high-performance, fuel-efficient vehicles is influencing product strategies. The presence of major OEMs and a well-developed aftermarket supports continued growth. Government policies promoting clean energy and sustainable transportation are strengthening the market outlook.
Key Player Analysis:
- Bosch Limited
- Mitsubishi Electric Corp.
- BorgWarner
- Schaeffler AG
- ZF Friedrichshafen AG
- Magna International Inc.
- Nidec Corporation
- Continental AG
- Valeo
- Magneti Marelli Ck Holdings
Competitive Analysis:
The powertrain market is highly competitive, with established global players leveraging technological expertise, extensive product portfolios, and strong supply chain networks to maintain market leadership. Key companies include Bosch Limited, Mitsubishi Electric Corp., BorgWarner, Schaeffler AG, ZF Friedrichshafen AG, Magna International Inc., and Nidec Corporation. It is characterized by rapid innovation in electrification, hybrid systems, and intelligent control technologies to meet evolving regulatory and consumer demands. Leading manufacturers are investing in R&D to enhance efficiency, performance, and sustainability, while expanding capabilities in electric and hybrid powertrains. Strategic partnerships, mergers, and acquisitions are common to strengthen market position and access advanced technologies. Companies are also focusing on cost optimization, modular platform development, and regional production hubs to improve competitiveness. The market’s dynamic nature requires continuous adaptation to technological shifts and changing mobility trends.
Recent Developments:
- In February 2025, Mitsubishi Electric signed an agreement to form a joint venture and acquire a minority stake in HD Renewable Energy, a Taipei-based developer, aiming to aggregate distributed energy resources in Japan.
- In April 2025, BorgWarner introduced the iM-575 integrated inverter-motor drive module engineered for commercial electric vehicles at the ACT Expo 2025 in Anaheim.
- In August 2025, Bosch Limited finalized the acquisition of the global residential and light commercial HVAC business from Johnson Controls and its stake in the Johnson Controls-Hitachi joint venture, a transaction valued at $8billion aimed at expanding Bosch’s Home Comfort division.
Market Concentration & Characteristics:
The powertrain market demonstrates a moderately high level of concentration, with leading global OEMs and Tier-1 suppliers holding significant influence over technology development, production, and supply chains. It is characterized by strong competition driven by rapid innovation, regulatory compliance, and the transition toward electrified mobility. Key players focus on strategic alliances, vertical integration, and R&D investment to secure market position. The industry features a mix of established combustion powertrain providers and emerging electric mobility specialists, creating a dynamic competitive landscape. Continuous advancements in efficiency, performance, and sustainability define product differentiation. Regional manufacturing hubs and localized supply networks enhance responsiveness to market-specific demands.
Report Coverage:
The research report offers an in-depth analysis based on Segment 1, Segment 2, Segment 3, and Segment 3. It details leading Market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current Market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven Market expansion in recent years. The report also explores Market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on Market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the Market.
Future Outlook:
- Electrification will remain the primary growth driver, with increasing adoption of battery electric, plug-in hybrid, and fuel cell powertrains across global markets.
- It will see significant advancements in battery technology, improving energy density, charging speed, and lifecycle performance.
- Integration of intelligent control systems and AI-driven energy management will enhance efficiency and adaptability.
- Lightweight materials and advanced manufacturing processes will reduce vehicle weight and improve power-to-weight ratios.
- Hybrid powertrains will continue to evolve as a transitional solution, balancing performance, range, and emissions compliance.
- Demand for modular and flexible platforms capable of supporting multiple propulsion types will rise among automakers.
- Growth in connected and autonomous vehicles will drive innovation in integrated powertrain and vehicle control systems.
- It will benefit from expanding government incentives and infrastructure investment for electric mobility.
- Supply chain localization and diversification will become critical to mitigate risks related to critical materials and geopolitical factors.
- Collaboration between automotive OEMs, technology firms, and energy providers will accelerate innovation and commercialization of next-generation powertrain solutions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Stringent Emission Regulations
Global implementation of stricter emission standards such as Euro 7, CAFE, and China VI is compelling automakers to invest in cleaner, more efficient powertrain technologies, accelerating the shift toward hybrid and electric systems.
Rapid Electrification and Hybridization
The growing adoption of electric and hybrid vehicles, supported by government incentives and consumer environmental awareness, is driving demand for advanced battery systems, electric motors, and flexible vehicle platforms.
Focus on Fuel Efficiency and Performance
Automakers are prioritizing lightweight materials, optimized transmissions, and advanced engine technologies to meet consumer expectations for high performance while complying with fuel efficiency mandates.
Integration of Digital and Intelligent Control Systems
The adoption of AI, machine learning, and connected systems is enabling predictive maintenance, real-time optimization, and compatibility with autonomous vehicles, enhancing the value proposition of modern powertrains.
Government Incentives and Infrastructure Investment
Expanding government support for electric mobility, including subsidies and charging infrastructure development, is accelerating the commercialization and adoption of next-generation powertrain solutions.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the powertrain market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the powertrain market projected to grow between 2024 and 2032?
What are the primary factors fueling the growth of the powertrain market?
Who are the leading companies in the powertrain market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-Use
- 1.2.1 OEMs
- 1.2.2 Aftermarket
- 1.3 By Product
- 1.3.1 Engine
- 1.3.2 Transmission
- 1.3.3 Drive Shafts
- 1.3.4 Differentials
- 1.3.5 Final Drive Systems
- 1.4 By Application
- 1.4.1 Passenger Vehicles
- 1.4.2 Light Commercial Vehicles
- 1.4.3 Heavy Commercial Vehicles
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 118,230.7 million → 2032: USD 150,938.3 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Powertrain Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Powertrain Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Powertrain Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Powertrain Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Powertrain Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Powertrain Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Powertrain Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Powertrain Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 118,230.7 million → 2032: USD 150,938.3 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Powertrain Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-Use - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 OEMs
- 12.3.7.2 Aftermarket
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Engine
- 12.4.7.2 Transmission
- 12.4.7.3 Drive Shafts
- 12.4.7.4 Differentials
- 12.4.7.5 Final Drive Systems
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Passenger Vehicles
- 12.5.7.2 Light Commercial Vehicles
- 12.5.7.3 Heavy Commercial Vehicles
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Powertrain End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Powertrain Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Powertrain Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Powertrain Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Bosch Limited
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Mitsubishi Electric Corp.
- 18.4 BorgWarner
- 18.5 Schaeffler AG
- 18.6 ZF Friedrichshafen AG
- 18.7 Magna International Inc.
- 18.8 Nidec Corporation
- 18.9 Continental AG
- 18.10 Valeo
- 18.11 Magneti Marelli CK Holdings
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

