
Market Overview
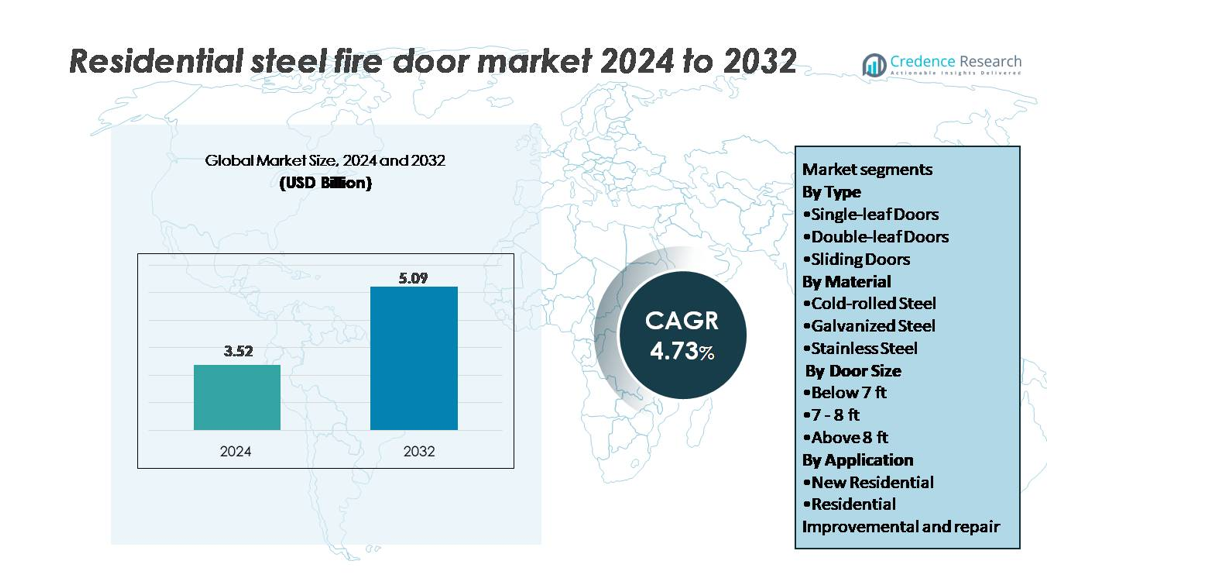
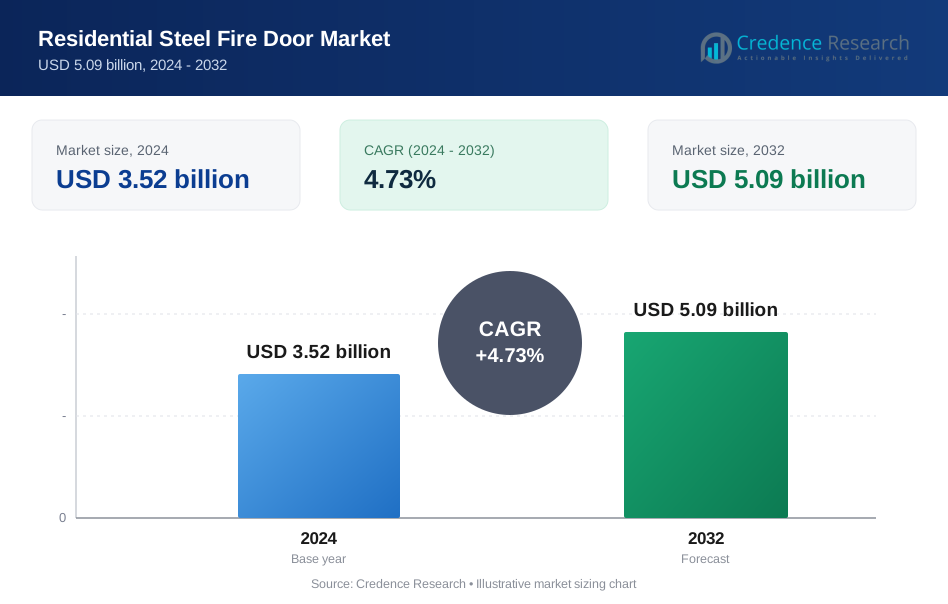
The Residential Steel Fire Door Market size was valued at USD 3.52 billion in 2024 and is projected to reach USD 5.09 billion by 2032, growing at a CAGR of 4.73% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Residential Steel Fire Door Market Size 2024 | USD 3.52 billion |
| Residential Steel Fire Door Market, CAGR | 4.73% |
| Residential Steel Fire Door Market Size 2032 | USD 5.09 billion |
The residential steel fire door market is led by major players including Masonite International Corporation, ASSA ABLOY, Hormann LLC, Allegion PLC, Kingspan Group Plc., JELD-WEN Holdings Inc., Apex Industries, Therma-Tru Corp, De La Fontaine Industries, and Deansteel Manufacturing Co., Inc. These companies emphasize certified fire protection, design innovation, and material durability to strengthen their competitive position. Strategic expansions and technological advancements, such as smart-closing mechanisms and energy-efficient steel doors, drive their market leadership. North America dominates the market with a 37.6% share, driven by large-scale housing developments, rising safety awareness, and stricter building codes in China, Japan, and India.
Market Insights
- The Residential Steel Fire Door Market size was valued at USD 3.52 billion in 2024 and is projected to reach USD 5.09 billion by 2032, growing at a CAGR of 4.73% during the forecast period.
- Demand is driven by stringent fire safety regulations and growing adoption of durable, low-maintenance materials in modern residential buildings.
- The market is witnessing trends toward smart, automated fire door systems and eco-friendly manufacturing using recycled steel and low-VOC coatings.
- Leading players such as Masonite International Corporation, ASSA ABLOY, Hormann LLC, Allegion PLC, and Kingspan Group Plc. focus on expanding product portfolios through certified and energy-efficient solutions.
- North America leads with a 37.6% regional share, while the single-leaf door segment dominates with 54.2% share, supported by widespread use in compact residential spaces and growing high-rise housing construction across China and India.
Market Segmentation Analysis:
By Type
The single-leaf door segment held the dominant market share of 54.2% in 2024. Its popularity stems from cost-effectiveness, easy installation, and suitability for standard residential entrances. These doors offer reliable fire resistance while maintaining aesthetic flexibility. Demand continues to grow in urban housing projects emphasizing compact layouts and efficient safety solutions.
- For instance, ASSA ABLOY introduced a single-leaf fire door series featuring 90-minute fire resistance and enhanced smoke control seals, ensuring compliance with EN 1634-1 standards for multi-family residences.
By Material
Galvanized steel accounted for the largest share of 48.9% in 2024 due to its superior corrosion resistance and durability. It is widely adopted for exterior applications where exposure to moisture is common. The segment benefits from low maintenance and longer lifespan compared to cold-rolled or stainless steel variants. For instance, Hormann launched galvanized fire-rated doors using zinc-coated sheets of 1.5 mm thickness, offering protection against rust and ensuring over 240 minutes of fire endurance under BS 476 Part 22 certification.
- For instance, Tata Steel introduced its Galvano range of zero-spangle galvanized sheets with coating thickness up to 275 g/m² and tensile strength reaching 550 MPa, providing enhanced corrosion resistance for industrial enclosures and roofing systems.
By Application, Door Size, and End Use
In terms of application, new residential construction dominated with a 57.4% market share, supported by stricter building codes requiring certified fire doors in new projects. Doors between 7–8 ft led the size segment due to their compatibility with modern architectural designs and ease of installation. Exterior use also held a notable share, driven by demand for weather-resistant models in high-rise and independent homes. For instance, Saint-Gobain Sejin developed an exterior fire door with a dual-layer steel core rated for 120 minutes fire integrity and tested at 1,000°C, meeting urban residential safety standards.
Key Growth Drivers
Stricter Fire Safety Regulations
Governments across major markets are mandating certified fire‐rated doors in residential buildings. The rising number of fire‐related incidents and enhanced public safety norms compel construction and renovation projects to install steel fire doors that meet international standards. Manufacturers of the residential steel fire door segment benefit from these regulatory changes, which drive demand and increase adoption across new builds and retrofit applications.
- For instance, JELD-WEN’s FD60 doorset is CERTIFIRE CF179 and rated 60 minutes. Hörmann’s BS-standard steel doors use hinges durability tested for 200,000 cycles.
Urbanisation & Residential Construction Growth
Rapid urbanisation, especially in Asia‐Pacific and the Middle East, fuels demand for multi‐storey residential projects and gated communities. These developments require robust fire protection elements, including steel fire doors, to comply with building safety codes. As developers scale residential projects and upgrade older housing stock, the market for residential steel fire doors expands accordingly, benefiting material suppliers and fabricators.
- For instance, Hormann Middle East (or its group company Shakti Hormann) supplies fire-rated steel doors that are engineered for 240 minutes of fire resistance and tested under the BS 476 Parts 20 & 22 standards.
Preference for Durable, Low‐Maintenance Materials
Homeowners and developers increasingly favour steel fire doors over timber variants due to better durability, lower maintenance and resistance to fire, moisture and termites. Steel fire doors provide longer lifespan and stronger structural integrity, which aligns with a trend toward long‐term quality investments in housing. This material shift advantages manufacturers offering cold‐rolled, galvanized or stainless steel fire door solutions and supports premiumisation in the segment.
Key Trends & Opportunities
Smart & Automated Fire Door Technologies
Manufacturers are integrating sensors, IoT connectivity and automatic closing systems into residential steel fire doors, enabling real‐time monitoring and enhanced safety. These smart doors can trigger notifications or integration with home automation platforms. As smart homes become mainstream, this presents an opportunity to differentiate products and capture premium segments in residencies seeking both aesthetics and functional safety.
- For instance, ASSA ABLOY’s SMARTair system integrates RFID and BLE-enabled sensors for access tracking and automatic locking during emergency alerts, operating on a 56 MHz frequency with <1 s activation latency.
Sustainable Materials & Eco-Friendly Manufacturing
Environmental concerns and circular economy mandates are pushing production toward recycled steel, eco‐coatings and low-VOC materials in fire door manufacturing. Sustainable product attributes appeal to environmentally conscious homeowners and developers and can satisfy green building certifications. Producers that offer steel fire doors made from high recycled‐content steel or use low-emission processes can tap into a growing sustainability‐driven market segment.
- For instance, ASSA ABLOY uses over 90% recycled steel content in its EcoDoor series, achieving an Environmental Product Declaration (EPD) verified under ISO 14025 and reducing embodied carbon by up to 2.1 kg CO₂ per door compared to conventional steel units.
Key Challenges
High Initial Cost and Installation Complexity
Steel fire doors require higher upfront costs than standard doors and need installation by skilled labour to meet certification standards. In cost-sensitive residential markets and lower-income segments, this cost barrier limits adoption. Developers and homeowners may delay or avoid specifying certified steel fire doors due to budget constraints, impacting market penetration.
Fragmented Standards & Competition from Non-Certified Products
The market faces inconsistencies in fire door certification across regions and a proliferation of non-compliant or counterfeit products. This undermines trust and complicates specification by architects or builders. Manufacturers adhering to high certification standards face price pressure from cheaper alternatives, which can erode margins and challenge the value proposition of genuine certified steel fire doors.
Regional Analysis
North America
North America dominated the residential steel fire door market in 2024 with a 37.6% share. The region’s growth stems from stringent fire safety regulations and widespread adoption of energy-efficient building materials. The U.S. leads the market due to strong construction activity and retrofit demand in urban housing. Canada is also witnessing growth through government-backed fire safety upgrades and green building initiatives. Leading manufacturers such as ASSA ABLOY and Allegion continue expanding their fire-rated door portfolios, focusing on smart and sustainable steel solutions tailored for modern residential architecture.
Europe
Europe accounted for a 29.4% share of the residential steel fire door market in 2024. The market benefits from well-established safety codes and increasing adoption of EN 1634-1 certified doors in residential complexes. The U.K., Germany, and France represent the largest consumers, driven by rising multi-family construction and refurbishment projects. Ongoing energy-efficiency standards and fire safety modernization further support market expansion. European players like Hörmann and Teckentrup emphasize R&D for corrosion-resistant and acoustic-rated steel fire doors to enhance performance and sustainability.
Asia-Pacific
Asia-Pacific held a 23.8% share in 2024 and is projected to be the fastest-growing region. Rapid urbanization, infrastructure expansion, and tightening building codes in China, India, and Japan drive demand. Governments in these countries are enforcing mandatory fire safety standards in high-rise and smart residential projects. Rising middle-class housing demand and increased awareness of fire-resistant construction also contribute to growth. Regional manufacturers, including Sanwa Holdings and dormakaba, are introducing lightweight, thermally insulated steel fire door models for large-scale residential developments.
Latin America
Latin America captured a 5.7% share in the residential steel fire door market in 2024. Brazil and Mexico dominate due to steady growth in urban residential construction and greater emphasis on occupant safety. Government-led programs encouraging safer housing designs are improving adoption rates. Economic recovery and construction modernization projects are also supporting market expansion. Local manufacturers focus on cost-effective steel door solutions with enhanced durability to meet diverse building needs in middle-income residential segments.
Middle East & Africa
The Middle East & Africa region accounted for a 3.5% share in 2024. Increasing investment in residential complexes and smart city projects is driving steady demand for fire-rated steel doors. The United Arab Emirates and Saudi Arabia are key markets due to strong adherence to building safety codes. Africa’s emerging urban centers, including South Africa and Kenya, are witnessing rising awareness of fire protection standards. The region’s market growth is further supported by international manufacturers expanding partnerships with local distributors to meet rising construction demands.
Market Segmentations:
By Type
- Single-leaf Doors
- Double-leaf Doors
- Sliding Doors
By Material
- Cold-rolled Steel
- Galvanized Steel
- Stainless Steel
By Door Size
- Below 7 ft
- 7 - 8 ft
- Above 8 ft
By Application
- New Residential
- Residential Improvement & Repair
By End Use
- Exterior
- Interior
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Key Player analysis
- Masonite International Corporation
- HMX, LLC
- Cambridge Doors and Windows
- Kingspan Group Plc.
- Apex Industries
- Therma-Tru Corp
- MPI Custom Steel Doors and Frames
- Hormann LLC
- TruDoor, LLC
- ASSA ABLOY
- Allegion PLC
- De La Fontaine Industries
- Titan Metal Products
- Deansteel Manufacturing Co., Inc.
- Safex Fire Services Ltd.
- JELD-WEN Holdings Inc.
Competitive Landscape
The residential steel fire door market features a competitive landscape dominated by leading manufacturers such as Masonite International Corporation, HMX, LLC, Cambridge Doors and Windows, Kingspan Group Plc., Apex Industries, Therma-Tru Corp, MPI Custom Steel Doors and Frames, Hormann LLC, TruDoor, LLC, ASSA ABLOY, Allegion PLC, De La Fontaine Industries, Titan Metal Products, Deansteel Manufacturing Co., Inc., Safex Fire Services Ltd., and JELD-WEN Holdings Inc. These companies compete through innovation in design, fire-resistance certification, and energy efficiency. Firms are investing in automated production lines, corrosion-resistant coatings, and smart locking systems to enhance performance and safety standards. For instance, ASSA ABLOY launched a residential-grade fire door series featuring smart close technology and integrated thermal seals, improving both safety and insulation efficiency. Partnerships with construction firms and expansion into emerging residential markets further strengthen their global presence and market share leadership.
Recent Developments
- In October 2023, ASSA ABLOY launched the OH1142P Dual Drive doors. The Dual Drive, embedded within the door, relies on two motors. These motors, working on either side of the door, smoothly lift and lower it using a fixed chain. It also offers smart connectivity for ongoing optimization.
- In January 2023, Therma-Tru launched its fiberglass and steel product lineup for 2023, which included an innovative, integrated storm & entry door system, decorative glass designs, paint & stain color options, additional sizes for popular styles, and more.
Report Coverage
The research report offers an in-depth analysis based on Type, Material, Door size, Application, End use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for certified steel fire doors will continue to rise due to stricter residential safety regulations.
- Manufacturers will invest in automation and digital monitoring technologies to enhance product quality.
- Smart fire doors with IoT sensors and self-closing mechanisms will gain strong adoption in modern homes.
- Sustainable and recyclable steel materials will become standard in future product lines.
- Prefabricated housing and modular construction projects will increase the need for ready-to-install fire doors.
- Asia-Pacific will remain the key growth region supported by rapid urbanization and housing expansion.
- Companies will expand partnerships with real estate developers to secure long-term installation contracts.
- Innovation in lightweight, thermally insulated steel doors will improve energy efficiency in homes.
- Growing home renovation and retrofit activities will sustain aftermarket demand.
- Enhanced certification standards and testing protocols will improve consumer trust and product reliability globally.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Residential Steel Fire Door, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Residential Steel Fire Door Market projected to grow between 2025 and 2032?
Which Residential Steel Fire Door segment held the largest share in 2024?
What are the primary factors fueling the growth of the Residential Steel Fire Door Market?
Who are the leading companies in the Residential Steel Fire Door Market?
Which region commanded the largest share of the Residential Steel Fire Door Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 3.52 billion → 2032: USD 5.09 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Residential Steel Fire Door Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Residential Steel Fire Door Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Residential Steel Fire Door Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Residential Steel Fire Door Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Residential Steel Fire Door Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Residential Steel Fire Door Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Residential Steel Fire Door Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Residential Steel Fire Door Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 3.52 billion → 2032: USD 5.09 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Residential Steel Fire Door Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Residential Steel Fire Door Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Residential Steel Fire Door Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Residential Steel Fire Door Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

