
Market Overview:
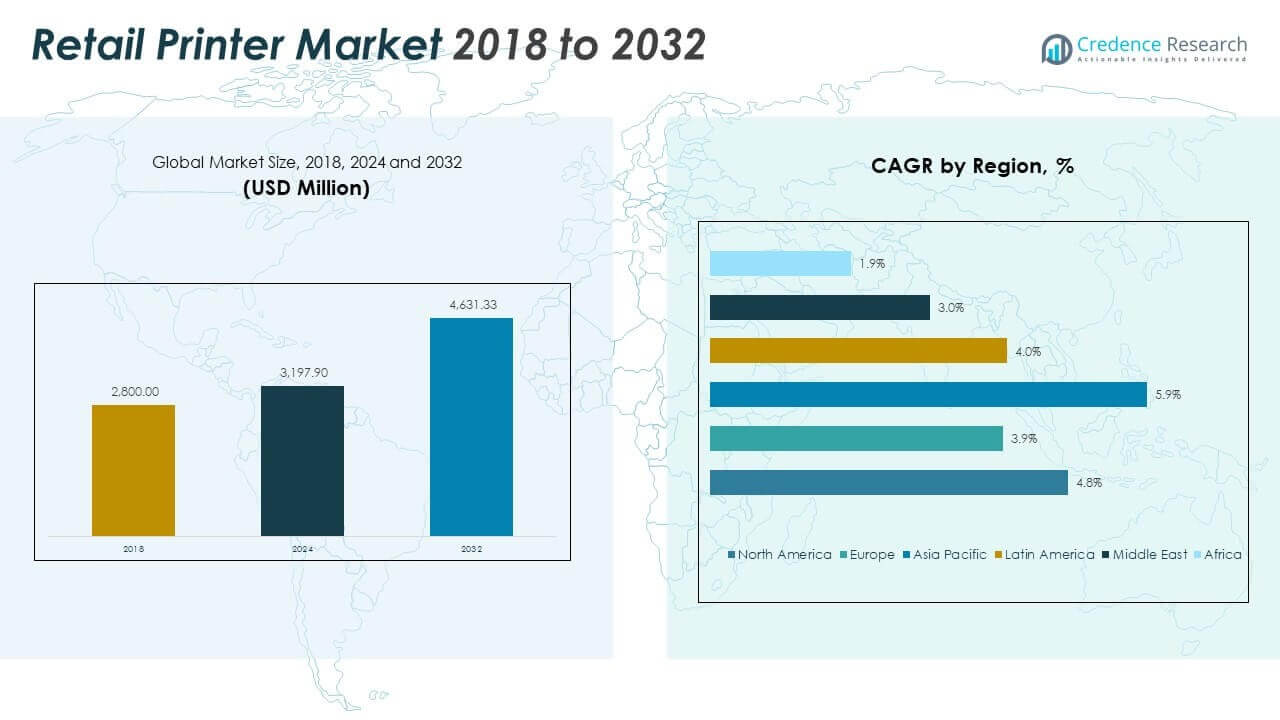
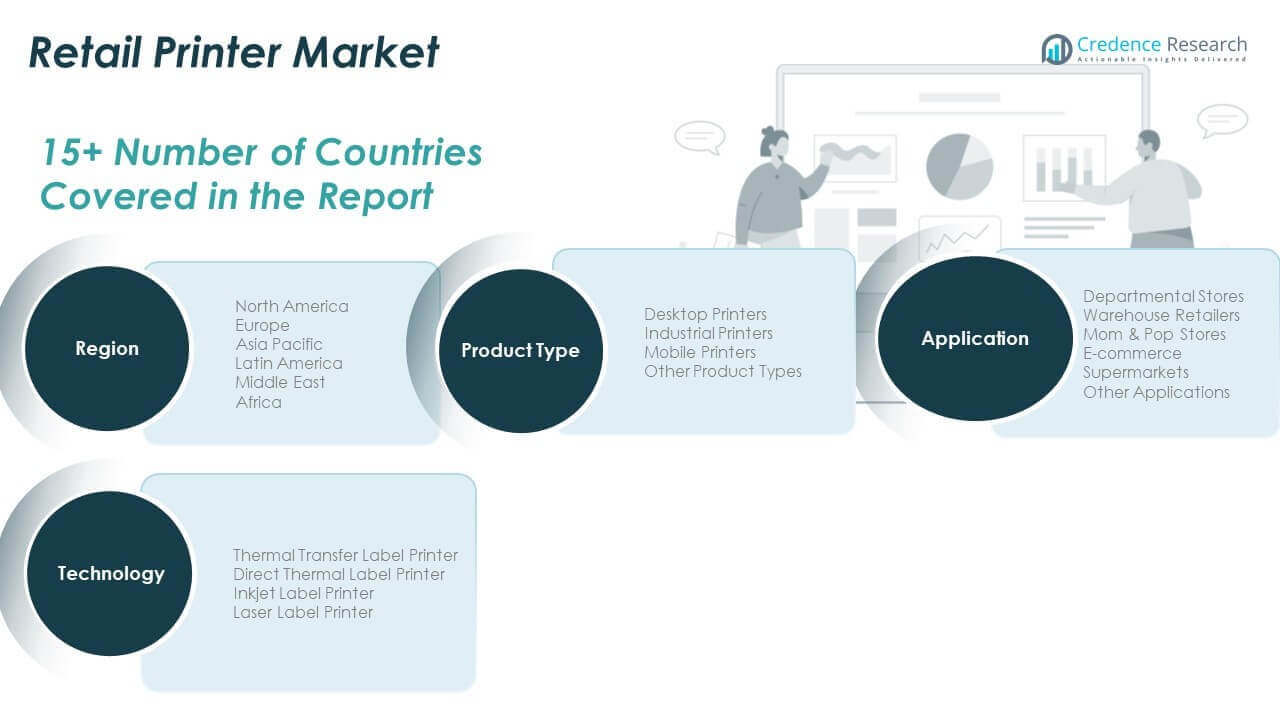
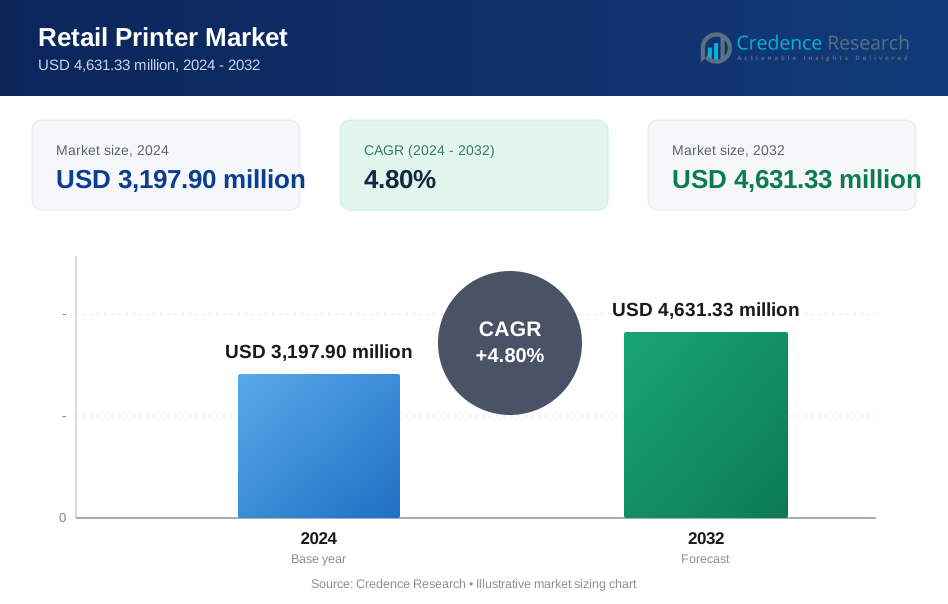
The Retail Printer Market size was valued at USD 2,800.00 million in 2018 to USD 3,197.90 million in 2024 and is anticipated to reach USD 4,631.33 million by 2032, at a CAGR of 4.80% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Retail Printer Market Size 2024 | USD 3,197.90 Million |
| Retail Printer Market, CAGR | 4.80% |
| Retail Printer Market Size 2032 | USD 4,631.33 Million |
The Retail Printer Market grows due to expansion of organized retail and digital billing systems. Retailers adopt printers to improve checkout speed and billing accuracy. POS deployment increases receipt and label printing needs. Inventory management relies on barcode and product labeling. E-commerce fulfillment drives demand for shipping and return labels. Regulatory invoice requirements sustain printer usage. Hardware standardization across stores supports replacement demand. Compact and thermal printers gain preference due to low maintenance needs.
North America leads due to advanced retail infrastructure and high POS penetration. The United States remains a key contributor with large retail chains and e-commerce hubs. Europe follows with strong compliance-driven printing demand across supermarkets. Asia Pacific emerges as the fastest-growing region driven by China and India. Rapid retail formalization and digital payments support adoption. Latin America shows steady progress through retail modernization. Middle East and Africa remain emerging due to gradual infrastructure development.
Market Insights:
- The Retail Printer Market reached USD 2,800.00 million in 2018, expanded to USD 3,197.90 million in 2024, and is projected to reach USD 4,631.33 million by 2032, growing at a CAGR of 4.80% driven by POS expansion and retail digitization.
- North America dominated with about 35.4% share in 2024, followed by Asia Pacific at 30.8% and Europe at 21.6%, supported by mature retail infrastructure, high transaction density, and strong compliance requirements.
- Asia Pacific emerged as the fastest-growing region and held nearly 30.8% share in 2024, driven by retail formalization in China and India, rapid supermarket expansion, and rising digital payment adoption.
- By product type and application, desktop and industrial printers together accounted for nearly 68% share, while supermarkets and departmental stores contributed around 46% share, reflecting high billing frequency and centralized store operations.
- By technology, thermal printing solutions held about 64% share, supported by low maintenance needs, faster output, and suitability for high-volume retail receipt and label printing.
Market Drivers:
Expansion Of Organized Retail And Point Of Sale Infrastructure Across Formats
The Retail Printer Market benefits from steady growth in organized retail formats worldwide. Supermarkets, hypermarkets, and specialty stores invest in structured billing systems. Retailers rely on printers to ensure fast and accurate checkout operations. POS expansion increases demand for receipt and label printing devices. Retail chains standardize hardware across locations for consistency. It supports better transaction control and customer service quality. Franchise models further increase printer deployment needs. Retail digitization sustains long-term equipment demand. Retail automation programs reinforce printer upgrades. Store expansion plans also raise installation volumes.
Rising Need For Accurate Billing, Inventory Tracking, And Product Identification
The Retail Printer Market gains traction from demand for precise transaction records. Retailers prioritize error-free billing to maintain customer trust. Barcode and label printers improve stock visibility across shelves. Inventory audits rely on clear product identification. It helps retailers reduce shrinkage and stock mismatch issues. Fast-moving goods require frequent label updates. Retail compliance norms encourage printed records. These factors reinforce continuous printer usage. Store managers depend on printed data for daily reconciliation. Audit readiness increases reliance on physical documentation.
Growth Of E-Commerce Fulfillment And Omni Channel Retail Operations
The Retail Printer Market sees support from omni channel retail growth. Stores handle online orders alongside walk-in sales. Packing slips, return labels, and invoices need reliable printing. Retailers integrate printers with order management systems. It improves fulfillment speed and order accuracy. Same-day delivery models raise printing frequency. Click-and-collect services also depend on printed tags. This driver expands usage beyond checkout counters. Reverse logistics also require consistent label output. Fulfillment hubs increase printer density per location.
- For instance, Amazon uses industrial label printers, including solutions from Honeywell, across its U.S. fulfillment network to support high-volume shipping label printing and fast order processing for same-day and next-day delivery operations.
Regulatory Compliance And Tax Invoice Documentation Requirements
The Retail Printer Market advances due to regulatory billing requirements. Governments mandate printed tax invoices in many regions. Retailers maintain transaction records for audits. It ensures compliance with consumer protection laws. Thermal printers suit high-volume invoice needs. Retail systems align hardware with fiscal rules. Small stores adopt compliant printers for legal safety. Regulatory pressure sustains stable demand. Policy enforcement raises inspection frequency. Documentation accuracy becomes operational priority.
- For instance, Reliance Retail has deployed thermal receipt printers across its extensive store network in India to support GST-compliant billing, fast invoice generation, and standardized POS operations during regulatory audits and peak retail periods.
Market Trends:
Shift Toward Compact And Space Efficient Retail Printing Devices
The Retail Printer Market reflects a clear shift toward compact hardware designs. Retailers prefer devices that fit limited counter space. Urban stores operate with smaller footprints. It improves counter organization and staff movement. Portable printers gain traction in pop-up stores. Mobile checkout concepts also support this trend. Retailers value ease of placement and setup. Compact formats influence product design strategies. Hardware aesthetics gain attention in modern stores. Lightweight units ease relocation needs.
Increasing Adoption Of Wireless And Cloud-Connected Printing Solutions
The Retail Printer Market trends toward wireless connectivity options. Retailers reduce cable clutter in store layouts. Cloud-based POS systems integrate directly with printers. It allows remote monitoring and device control. Central teams manage printer status across outlets. Software updates deploy without physical access. This trend supports scalable retail networks. Connectivity improves operational flexibility. Networked devices support faster troubleshooting. Centralized control lowers support costs.
- For instance, Lexmark’s Cloud Fleet Management integrates with Microsoft Universal Print to enable remote device management and cloud-based print job submission without requiring local PC applications.
Preference For Low Maintenance And Energy Efficient Printing Technologies
The Retail Printer Market shows rising preference for low maintenance solutions. Retailers aim to reduce downtime and service costs. Thermal printers attract attention due to fewer moving parts. It lowers consumable replacement frequency. Energy-efficient devices align with cost control goals. Retail chains track operating expenses closely. Sustainable store operations also influence procurement. Efficiency shapes purchasing decisions. Warranty coverage affects model selection. Lifecycle cost evaluation guides procurement teams.
Customization And Branding Through Printed Receipts And Labels
The Retail Printer Market highlights growing focus on print customization. Retailers use receipts for brand messaging. Promotional content appears on transaction slips. It supports marketing without extra media spend. Labels carry logos and compliance details. Loyalty programs integrate with printed coupons. Personalized print output enhances customer engagement. Branding adds strategic value to printers. Seasonal campaigns drive content updates. Printed touchpoints reinforce brand recall.
- For instance, Brother’s RJ-4230B mobile printer offers 203 dpi resolution on 3-inch labels, enabling clear printing of barcodes and QR codes for coupons and loyalty program use in retail environments.
Market Challenges Analysis:
High Initial Hardware Investment And Ongoing Replacement Cycles
The Retail Printer Market faces cost pressure from hardware investment needs. Small retailers struggle with upfront purchase expenses. Multi-store chains replace devices on fixed cycles. It strains capital budgets over time. Imported hardware increases cost exposure. Maintenance contracts add to total ownership costs. Price-sensitive markets delay upgrades. Cost control remains a core challenge. Budget limits slow technology refresh. Leasing options remain limited in many regions.
Technology Obsolescence And Compatibility Issues With POS Systems
The Retail Printer Market encounters challenges from rapid system upgrades. POS software updates require compatible hardware. Legacy printers fail to support new interfaces. It creates integration delays during system refresh cycles. Retailers face disruption during replacements. Vendor lock-in limits flexibility. Staff retraining adds operational burden. Technology alignment requires careful planning. Transition periods impact store productivity. Compatibility testing increases deployment time.
Market Opportunities:
Untapped Potential In Emerging Retail Markets And Tier Two Cities
The Retail Printer Market holds strong opportunity in emerging regions. Organized retail expands beyond major cities. Tier two and tier three locations adopt POS systems. It drives first-time printer installations. Local retailers modernize billing practices. Affordable printer models suit these markets. Distribution partnerships support wider reach. Expansion potential remains significant. Government digitization supports adoption. Retail formalization strengthens demand outlook.
Integration With Smart Retail And Automated Store Technologies
The Retail Printer Market can benefit from smart retail adoption. Automated checkout and digital shelves require printing support. It complements self-service and hybrid store models. Data-driven retail uses printed identifiers for tracking. AI-based inventory systems integrate with label printers. Smart stores demand reliable output devices. Vendors can offer bundled solutions. Innovation opens new revenue paths. Pilot stores validate advanced use cases. Technology partnerships enhance solution depth.
Market Segmentation Analysis:
The Retail Printer Market shows clear differentiation
By product type based on store scale and workload. Desktop printers serve small and mid-sized outlets that require compact and cost-efficient devices. Industrial printers support high-volume environments with continuous label and receipt output. Mobile printers gain demand in flexible retail formats and assisted selling models. Other product types address niche needs such as kiosk and specialty retail setups. Product selection depends on print speed, durability, and space constraints. Retailers align device choice with transaction intensity. Hardware reliability shapes long-term procurement decisions.
- For instance, TSC’s T600 series industrial printers are designed for high-volume, multi-site operations with consistent label output. The series supports fast print speeds, durable construction, and stable performance suited for continuous retail and logistics labeling environments.
By application, departmental stores and supermarkets represent major demand centers due to high daily transaction counts. Warehouse retailers rely on printers for bulk labeling and stock movement. Mom & pop stores adopt basic models to support billing compliance. E-commerce drives demand for shipping labels and return documentation. It supports integration with order management platforms. Other applications include convenience stores and specialty outlets. Application diversity sustains consistent demand across retail formats. Usage frequency varies by store size and sales model.
By technology, thermal transfer label printers gain traction for durable and long-life labeling needs. Direct thermal label printers suit fast, short-term printing tasks. Inkjet label printers support color and branding requirements. Laser label printers serve specialty and low-volume use cases. The Retail Printer Market benefits from technology choice based on print quality, cost, and maintenance needs. Retailers evaluate consumable availability and lifecycle costs. Technology adoption aligns with operational efficiency goals.
- For instance, SATO’s CL4NX Plus industrial printer supports a maximum print width of approximately 104 mm and offers 203 dpi resolution. The printer delivers high-speed thermal transfer and direct thermal printing, making it suitable for durable barcode and label output in retail and logistics environments.
Segmentation:
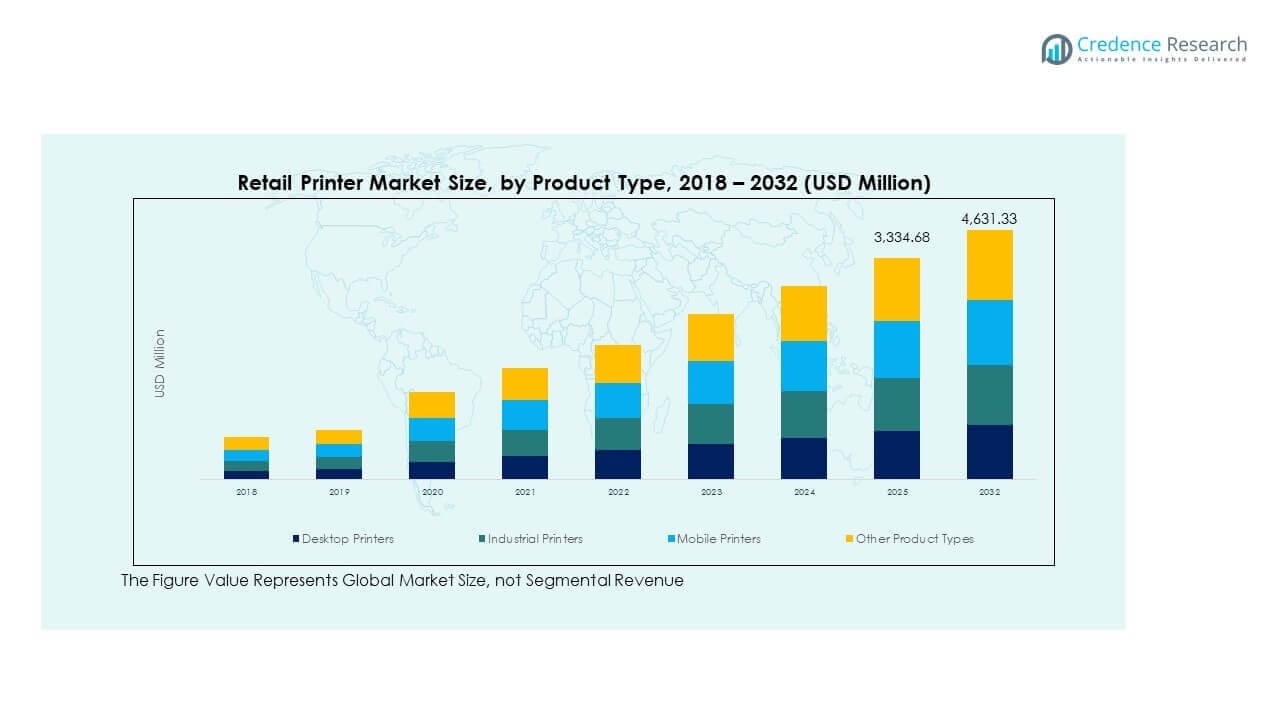
By Product Type
- Desktop Printers
- Industrial Printers
- Mobile Printers
- Other Product Types
By Application
- Departmental Stores
- Warehouse Retailers
- Mom & Pop Stores
- E-commerce
- Supermarkets
- Other Applications
By Technology
- Thermal Transfer Label Printers
- Direct Thermal Label Printers
- Inkjet Label Printers
- Laser Label Printers
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America Retail Printer Market size was valued at USD 1,002.40 million in 2018 to USD 1,130.76 million in 2024 and is anticipated to reach USD 1,635.33 million by 2032, at a CAGR of 4.8% during the forecast period. The region held nearly 35.36% market share in 2024. The Retail Printer Market in North America remains mature and technology driven. Large retail chains rely on standardized POS hardware across stores. It benefits from early adoption of wireless and cloud-enabled printers. The U.S. leads demand due to high transaction volumes. Canada supports growth through organized retail penetration. Retail compliance requirements sustain receipt printing demand. E-commerce fulfillment centers increase label printer use. Hardware refresh cycles remain consistent. Vendor presence supports stable replacement demand.
Europe
The Europe Retail Printer Market size was valued at USD 632.80 million in 2018 to USD 690.02 million in 2024 and is anticipated to reach USD 934.38 million by 2032, at a CAGR of 3.9% during the forecast period. The region accounted for 21.58% market share in 2024. The Retail Printer Market in Europe reflects strong regulatory influence. Retailers comply with strict invoicing and documentation rules. Germany, France, and the UK lead demand. It supports steady use of thermal printers. Supermarkets and specialty stores dominate installations. Retail digitization progresses at a controlled pace. Hardware reliability remains a priority. Southern Europe shows moderate adoption growth. Eastern Europe offers gradual expansion potential.
Asia Pacific
The Asia Pacific Retail Printer Market size was valued at USD 831.60 million in 2018 to USD 984.46 million in 2024 and is anticipated to reach USD 1,548.26 million by 2032, at a CAGR of 5.9% during the forecast period. The region represented 30.78% market share in 2024. The Retail Printer Market in Asia Pacific shows strong expansion momentum. China and India drive volume through retail formalization. It gains support from rapid POS adoption. Convenience stores and supermarkets expand quickly. Japan and South Korea focus on efficiency upgrades. Mobile printers gain traction in urban retail. E-commerce growth supports label demand. Local manufacturing improves supply access. Price-sensitive markets favor compact devices.
Latin America
The Latin America Retail Printer Market size was valued at USD 207.20 million in 2018 to USD 234.69 million in 2024 and is anticipated to reach USD 318.96 million by 2032, at a CAGR of 4.0% during the forecast period. The region captured 7.34% market share in 2024. The Retail Printer Market in Latin America grows with retail modernization. Brazil and Argentina lead regional demand. It benefits from POS upgrades in urban areas. Organized retail expands gradually. Small stores adopt entry-level printers. Compliance needs support receipt printing. Economic volatility limits rapid upgrades. Local distributors shape vendor access. Demand remains replacement focused.
Middle East
The Middle East Retail Printer Market size was valued at USD 79.80 million in 2018 to USD 83.44 million in 2024 and is anticipated to reach USD 104.69 million by 2032, at a CAGR of 3.0% during the forecast period. The region held 2.61% market share in 2024. The Retail Printer Market in the Middle East aligns with mall-based retail growth. GCC countries lead adoption. It supports modern POS systems in large stores. Tourism-driven retail sustains printer use. Israel shows technology-focused demand. Small retailers adopt printers at a slower pace. Import dependence influences pricing. Retail digitization remains selective. Expansion follows infrastructure investment.
Africa
The Africa Retail Printer Market size was valued at USD 46.20 million in 2018 to USD 74.52 million in 2024 and is anticipated to reach USD 89.71 million by 2032, at a CAGR of 1.9% during the forecast period. The region accounted for 2.33% market share in 2024. The Retail Printer Market in Africa remains at an early stage. South Africa leads structured retail adoption. It gains traction from POS penetration in cities. Informal retail limits widespread deployment. Hardware affordability influences demand patterns. Imports dominate supply channels. Power reliability affects device choice. Government digitization supports gradual growth. Long-term potential remains untapped.
Key Player Analysis:
- Zebra Technologies Corporation
- Epson Corporation
- Toshiba TEC Corporation
- Honeywell International Inc.
- Bixolon Co., Ltd.
- Avery Dennison Corporation
- Brother Industries, Ltd.
- Star Micronics Co., Ltd.
- SATO Holdings Corporation
- TSC Auto ID Technology Co., Ltd.
- Postek Electronics Co., Ltd.
Competitive Analysis:
The Retail Printer Market features competition among global manufacturers and regional suppliers. Leading players focus on product reliability, print speed, and system compatibility. It benefits from strong brand presence and established distribution networks. Companies invest in thermal and mobile printer portfolios to address varied retail needs. Strategic partnerships with POS providers strengthen market access. Vendors emphasize service support and warranty coverage to retain customers. Price competition remains intense in entry-level segments. Innovation centers on compact designs and wireless connectivity. Regional players compete through cost-effective offerings. Market positioning depends on technology depth and customer reach.
Recent Developments:
- In October 2025, Epson Corporation announced the integration of its POS thermal receipt printers into OnQ's Converge Take-a-Ticket retail display platform enhancing streamlined buying experiences for retailers by connecting with inventory and e-commerce systems.
- In January 2025, Lexmark announced new retail-ready printers at NRF 2025. The company showcased its 9-Series family of A3 printers and multifunction printers (MFPs) designed to boost operational efficiency and sales for retailers. These devices mark a significant update tailored for retail environments
Report Coverage:
The research report offers an in-depth analysis based on Product Type, Application and Technology. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Retail automation expansion will sustain printer demand across checkout, inventory, and fulfillment functions in both large and small retail formats.
- Wireless and cloud-ready printers will gain priority as retailers standardize centralized POS and store management platforms.
- Compact and mobile printer adoption will rise with space-limited stores and assisted selling models in urban retail environments.
- Thermal printing technologies will continue to dominate due to lower maintenance needs and consistent performance in high-transaction settings.
- E-commerce operations will increase printer deployment for shipping labels, returns processing, and order verification workflows.
- Emerging markets will support volume growth through retail formalization and first-time POS hardware installations.
- Compliance-driven printing will remain critical due to tax invoicing and audit documentation requirements across regions.
- Hardware refresh cycles will drive repeat purchases as retailers upgrade legacy devices to compatible modern systems.
- Sustainability focus will influence product design through energy efficiency and reduced consumable usage.
- Competitive differentiation will rely on reliability, service support, and integration with retail software ecosystems.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Expansion of Organized Retail and POS Infrastructure
The growth of supermarkets, hypermarkets, and specialty stores is driving the adoption of structured billing systems and POS terminals, which in turn increases the demand for retail printers to support fast and accurate checkout operations.
Rising Need for Accurate Billing, Inventory Tracking, and Product Identification
Retailers are prioritizing error-free billing and efficient inventory management, relying on barcode and label printers to improve stock visibility, reduce shrinkage, and ensure compliance with audit and documentation requirements.
Growth of E-Commerce Fulfillment and Omnichannel Retail
The surge in online orders and omnichannel retail operations is boosting demand for printers used in shipping labels, packing slips, and return documentation, as retailers integrate printing solutions with order management and fulfillment systems.
Regulatory Compliance and Tax Invoice Documentation
Government mandates for printed tax invoices and transaction records are sustaining steady demand for retail printers, especially thermal models, as retailers must comply with fiscal regulations and audit requirements across regions.
Preference for Compact, Low Maintenance, and Wireless Printing Solutions
Retailers are increasingly adopting compact, energy-efficient, and wireless printers to optimize limited counter space, reduce maintenance costs, and enable flexible store layouts, supporting the modernization of retail environments.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Retail Printer Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Retail Printer Market projected to grow between 2024 and 2032?
Which Retail Printer Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Retail Printer Market?
Who are the leading companies in the Retail Printer Market?
Which region commanded the largest share of the Retail Printer Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Technology
- 1.2.1 Thermal Transfer Label Printers
- 1.2.2 Direct Thermal Label Printers
- 1.2.3 Inkjet Label Printers
- 1.2.4 Laser Label Printers
- 1.3 By Application
- 1.3.1 Departmental Stores
- 1.3.2 Warehouse Retailers
- 1.3.3 Mom & Pop Stores
- 1.3.4 E-commerce
- 1.3.5 Supermarkets
- 1.3.6 Other Applications
- 1.4 By Product Type
- 1.4.1 Desktop Printers
- 1.4.2 Industrial Printers
- 1.4.3 Mobile Printers
- 1.4.4 Other Product Types
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 3,197.90 million → 2032: USD 4,631.33 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Retail Printer Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Retail Printer Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Retail Printer Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Retail Printer Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Retail Printer Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Retail Printer Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Retail Printer Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Retail Printer Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 3,197.90 million → 2032: USD 4,631.33 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Retail Printer Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Technology - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Thermal Transfer Label Printers
- 12.3.7.2 Direct Thermal Label Printers
- 12.3.7.3 Inkjet Label Printers
- 12.3.7.4 Laser Label Printers
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Departmental Stores
- 12.4.7.2 Warehouse Retailers
- 12.4.7.3 Mom & Pop Stores
- 12.4.7.4 E-commerce
- 12.4.7.5 Supermarkets
- 12.4.7.6 Other Applications
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Desktop Printers
- 12.5.7.2 Industrial Printers
- 12.5.7.3 Mobile Printers
- 12.5.7.4 Other Product Types
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Retail Printer End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Retail Printer Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Retail Printer Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Retail Printer Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Zebra Technologies Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Epson Corporation
- 18.4 Toshiba TEC Corporation
- 18.5 Honeywell International Inc.
- 18.6 Bixolon Co., Ltd.
- 18.7 Avery Dennison Corporation
- 18.8 Brother Industries, Ltd.
- 18.9 Star Micronics Co., Ltd.
- 18.10 SATO Holdings Corporation
- 18.11 TSC Auto ID Technology Co., Ltd.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

