
Market Overview:
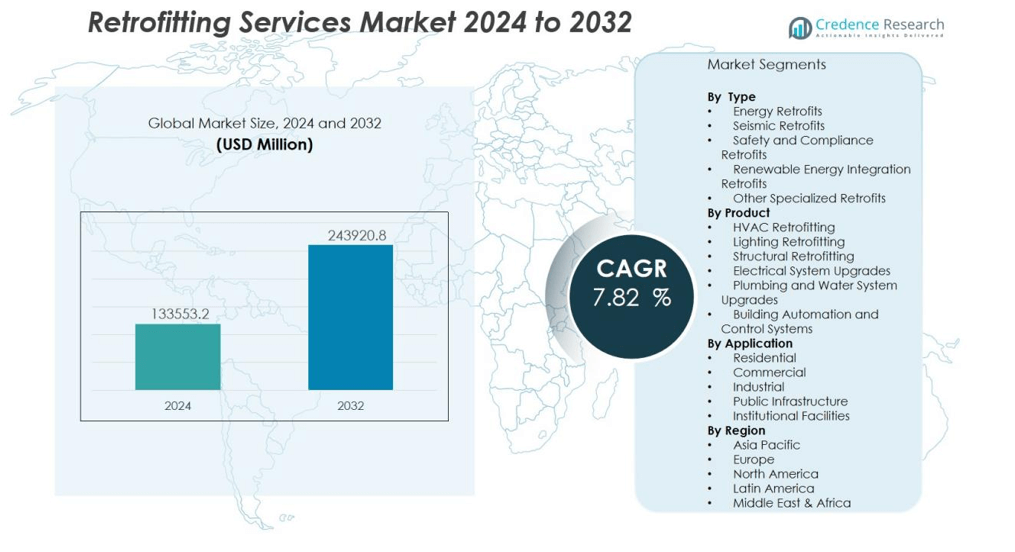
The retrofitting services market size was valued at USD 133553.2 million in 2024 and is anticipated to reach USD 243920.8 million by 2032, at a CAGR of 7.82 % during the forecast period (2024-2032).
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Retrofitting Services Market Size 2024 | USD 133553.2 million |
| Retrofitting Services Market, CAGR | 7.82% |
| Retrofitting Services Market Size 2032 | USD 243920.8 million |
Growth in the retrofitting services market is supported by increasing government incentives for energy-efficient building upgrades, stricter environmental regulations, and rising demand for cost-effective modernization over complete replacement. Technological advancements in building automation, renewable energy integration, and advanced materials are enabling service providers to offer innovative solutions. The push toward decarbonization and net-zero targets, coupled with aging global infrastructure, is accelerating the adoption of retrofitting in HVAC systems, lighting, structural components, and industrial machinery.
Regionally, North America and Europe lead the market due to strong regulatory frameworks, advanced construction sectors, and significant investments in green building initiatives. Asia-Pacific is expected to record the fastest growth, fueled by rapid urbanization, infrastructure development, and government-led sustainability programs. The Middle East, Latin America, and Africa present emerging opportunities, driven by modernization needs and energy efficiency goals.
Market Insights:
- The retrofitting services market was valued at USD 133,553.2 million in 2024 and is expected to reach USD 243,920.8 million by 2032, growing at a CAGR of 7.82% from 2024 to 2032.
- Strong growth is supported by government incentives, stricter environmental regulations, and rising demand for cost-effective modernization over complete replacement.
- Technological advancements in building automation, renewable energy integration, and advanced materials are enabling more efficient and sustainable retrofitting solutions.
- Aging infrastructure worldwide is creating opportunities for cost-effective upgrades in HVAC systems, lighting, structural components, and industrial machinery.
- North America holds 34% market share, driven by robust regulations, advanced construction practices, and significant investment in green building initiatives.
- Europe accounts for 30% market share, led by stringent energy efficiency laws, the European Green Deal, and modernization of urban building stocks.
- Asia-Pacific, with 25% market share, is expected to grow fastest due to rapid urbanization, smart city projects, and government-backed sustainability programs.
Market Drivers:
Rising Demand for Energy Efficiency and Sustainability:
The retrofitting services market is witnessing strong growth due to the global push for energy-efficient and sustainable infrastructure. Governments, businesses, and property owners are investing in upgrades to reduce energy consumption, lower greenhouse gas emissions, and meet stringent environmental standards. It plays a crucial role in modernizing HVAC systems, improving insulation, and integrating renewable energy sources into existing structures. Rising energy costs are further encouraging stakeholders to adopt retrofitting as a cost-saving measure over the long term.
- For instance, Johnson Controls helped the Empire State Building reduce its annual energy consumption by 38 percent through a comprehensive retrofit of its HVAC and building management systems, and save $4.4 million annually in the process.
Government Regulations and Incentives Driving Adoption:
Stringent building codes, emission regulations, and safety standards are compelling property owners to upgrade facilities. The introduction of tax benefits, grants, and low-interest financing programs is creating a favorable environment for retrofitting investments. It supports compliance with evolving industry regulations while enhancing property value. Many national and regional governments are prioritizing retrofitting as part of their climate action plans, further accelerating adoption across multiple sectors.
- For instance, New York City's Local Law 97 requires buildings over 25,000sq.ft to reduce greenhouse gas emissions, leading to significant retrofits such as high-efficiency HVAC installations and smart energy controls implemented by Tishman Speyer, who cut emissions by 30% across their properties in the city.
Technological Advancements Enabling Efficient Solutions:
The availability of advanced technologies is transforming the scope and efficiency of retrofitting services. Innovations in smart building systems, automation, energy monitoring tools, and advanced materials enable faster and more precise upgrades. It allows service providers to deliver customized, cost-effective solutions that extend the lifespan of existing assets. The integration of IoT and AI-driven analytics is also improving operational efficiency and decision-making for retrofit projects.
Aging Infrastructure and Cost-Effective Modernization Needs:
Many regions are dealing with infrastructure nearing the end of its operational life. Retrofitting offers a practical alternative to complete replacement, delivering significant upgrades without the high costs of new construction. It helps businesses and municipalities extend asset performance while reducing downtime. This cost-efficient approach is driving demand in sectors such as manufacturing, commercial real estate, and public infrastructure.
Market Trends:
Integration of Smart Technologies and Digital Solutions:
The retrofitting services market is evolving with the increasing adoption of smart technologies to optimize building performance and operational efficiency. IoT-enabled sensors, AI-based energy management systems, and predictive maintenance tools are becoming integral to retrofit projects. These technologies allow real-time monitoring, data-driven decision-making, and automated control of energy systems. It enables property owners to achieve significant cost savings while enhancing occupant comfort and safety. The demand for building automation retrofits is rising across commercial, industrial, and residential segments. Cloud-based platforms and digital twin technology are also gaining traction, allowing stakeholders to simulate and optimize retrofit designs before implementation.
- For instance, Johnson Controls led the Empire State Building retrofit project, upgrading windows, lighting, and HVAC controls to achieve a reduction of 38 million kWh in annual energy consumption.
Focus on Green Building Standards and Sustainable Materials:
Sustainability is shaping the direction of retrofitting projects, with a stronger emphasis on meeting green building certifications such as LEED, BREEAM, and WELL. Service providers are increasingly using eco-friendly materials, low-emission products, and recyclable components to align with environmental goals. It supports long-term operational efficiency while reducing the carbon footprint of existing infrastructure. The trend extends to renewable energy integration, including solar panels, energy storage systems, and geothermal solutions. Demand for net-zero and near-zero energy buildings is pushing retrofitting solutions into the mainstream, particularly in urban areas with older building stocks. Collaboration between architects, engineers, and technology providers is enabling the creation of high-performance, sustainable retrofit designs that meet both regulatory requirements and market demand.
- For instance, the Empire State Building retrofit achieved LEED Gold certification after a $550million renovation, integrating energy-efficient systems in one of the most prominent commercial buildings in New York.
Market Challenges Analysis:
High Initial Costs and Budget Constraints:
The retrofitting services market faces challenges due to the significant upfront investment required for large-scale projects. Many property owners and businesses delay retrofits because of budget limitations, even when long-term savings are evident. It often requires specialized materials, advanced technology, and skilled labor, which increase project costs. Limited access to financing options further slows adoption, particularly in small and medium-sized enterprises. Fluctuations in material prices and supply chain disruptions can also impact project feasibility and timelines. This cost barrier is more pronounced in developing regions where retrofitting awareness and funding are limited.
Technical Complexities and Disruption to Operations:
Retrofitting existing infrastructure often involves complex technical challenges, especially in older buildings with outdated systems. Structural limitations, compatibility issues with modern technologies, and the need for customized solutions increase project complexity. It can also cause operational disruptions, as retrofits may require partial shutdowns or restricted access to facilities. These interruptions can be costly for businesses and institutions, affecting productivity. A shortage of skilled professionals with expertise in advanced retrofitting techniques further compounds the challenge. Regulatory compliance across multiple jurisdictions adds another layer of complexity, requiring thorough planning and execution.
Market Opportunities:
Growing Demand for Sustainable Infrastructure Upgrades:
The retrofitting services market holds significant opportunities as global priorities shift toward sustainable development and energy efficiency. Governments, corporations, and property owners are increasingly investing in upgrades to meet carbon reduction targets and green building standards. It creates a strong demand for solutions that improve energy performance, reduce emissions, and extend asset life. The integration of renewable energy systems, such as solar panels and battery storage, into existing structures is becoming a major growth area. Urban centers with aging building stocks present a substantial market for energy-efficient lighting, HVAC upgrades, and advanced insulation. International climate agreements and environmental policies further encourage widespread adoption.
Expansion in Emerging Markets and Infrastructure Modernization:
Rapid urbanization and infrastructure development in emerging economies are creating new prospects for retrofitting services. Many governments in Asia-Pacific, the Middle East, and Latin America are prioritizing modernization projects to enhance safety, efficiency, and environmental performance. It offers service providers opportunities to enter markets with growing construction activity and regulatory support for energy-efficient upgrades. Industrial facilities, public infrastructure, and commercial properties in these regions require significant retrofitting to meet global standards. Digitalization trends, smart city initiatives, and public–private partnerships are also fostering investment. These factors position emerging markets as high-potential growth drivers for the industry.
Market Segmentation Analysis:
By Type:
The retrofitting services market by type includes energy retrofits, seismic retrofits, and other specialized upgrades. Energy retrofits dominate due to rising demand for improved energy efficiency, lower operational costs, and compliance with environmental standards. Seismic retrofits are gaining traction in earthquake-prone regions, supported by stricter safety regulations. Other upgrades, such as fire safety enhancements and accessibility improvements, cater to specific building compliance needs. It is witnessing strong adoption of multi-purpose retrofits that combine safety, efficiency, and sustainability goals.
By Product:
By product, the market is segmented into HVAC retrofits, lighting retrofits, structural retrofits, and others. HVAC retrofits hold a significant share due to their impact on energy savings and indoor comfort. Lighting retrofits, driven by the shift to LED and smart lighting systems, are becoming increasingly common in both commercial and residential spaces. Structural retrofits focus on extending the lifespan and safety of aging infrastructure. It is also seeing demand for integrated systems that combine multiple retrofit solutions into a single project.
- For instance, Skanska managed the replacement of all 592 steel suspender ropes over the course of seven years, ensuring structural integrity while keeping the bridge operational.
By Application:
By application, the market covers residential, commercial, and industrial sectors. The commercial segment leads due to large-scale modernization of office buildings, retail spaces, and public facilities. Industrial retrofits focus on process optimization, equipment upgrades, and emission reduction. Residential retrofits are growing as homeowners adopt energy-efficient and smart home solutions. It benefits from government-backed programs targeting multiple application areas to meet sustainability and safety standards.
- For instance, the Empire State Building’s deep retrofit, led by Johnson Controls and Jones Lang LaSalle, achieved a 38% reduction in energy use, saving over $4million annually in energy costs.
Segmentations:
By Type:
- Energy Retrofits
- Seismic Retrofits
- Safety and Compliance Retrofits
- Renewable Energy Integration Retrofits
- Other Specialized Retrofits
By Product:
- HVAC Retrofitting
- Lighting Retrofitting
- Structural Retrofitting
- Electrical System Upgrades
- Plumbing and Water System Upgrades
- Building Automation and Control Systems
By Application:
- Residential
- Commercial
- Industrial
- Public Infrastructure
- Institutional Facilities
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis:
North America:
North America accounted for 34% market share in the retrofitting services market in 2024, driven by strong regulatory frameworks and a mature construction sector. The region benefits from significant investments in energy efficiency programs, green building certifications, and advanced retrofitting technologies. It has a well-established infrastructure base that requires modernization to meet evolving safety and environmental standards. Federal and state-level incentives for energy-efficient upgrades are encouraging adoption across residential, commercial, and industrial sectors. The presence of major service providers and technology innovators further strengthens the market position. Increasing demand for building automation, renewable energy integration, and advanced HVAC retrofits is expected to sustain growth in the coming years.
Europe:
Europe held 30% market share in the retrofitting services market in 2024, supported by stringent energy efficiency regulations and climate-neutrality goals. The European Green Deal and national-level policies are driving large-scale retrofitting projects across member states. It has a high proportion of aging building stocks, particularly in urban areas, creating substantial demand for modernization. Public–private partnerships are fostering innovation in sustainable retrofitting materials and smart building systems. Countries such as Germany, the UK, and France are leading adoption due to their ambitious carbon reduction targets. The region’s commitment to renewable energy integration is further expanding retrofit applications in both public and private infrastructure.
Asia-Pacific:
Asia-Pacific represented 25% market share in the retrofitting services market in 2024, fueled by rapid urbanization and infrastructure growth. Governments in China, India, and Japan are implementing policies to upgrade existing structures for energy efficiency and safety compliance. It is witnessing strong demand for retrofitting in commercial complexes, industrial plants, and public infrastructure. The expansion of smart city projects and rising investments in sustainable construction are accelerating adoption. Local and international service providers are tapping into opportunities created by large-scale modernization initiatives. Growing environmental awareness and regulatory enforcement are expected to make Asia-Pacific the fastest-growing regional market during the forecast period.
Key Player Analysis:
- Daikin Industries Ltd.
- Eaton
- Ameresco
- Johnson Controls
- AECOM
- General Electric
- Schneider Electric
- Siemens
- Orion Energy Systems, Inc.
- Signify N.V.
- Orion Energy Systems, Inc.
- Trane Technologies Inc.
- Engie SA
Competitive Analysis:
The retrofitting services market is competitive, with global corporations and specialized service providers offering diverse solutions across energy, structural, and system upgrades. Key players include Daikin Industries Ltd., Eaton, Ameresco, Johnson Controls, AECOM, General Electric, Schneider Electric, Siemens, and Orion Energy Systems, Inc. It is characterized by technological innovation, strong regulatory compliance capabilities, and expertise in large-scale project execution. Leading companies leverage advanced HVAC systems, smart building solutions, and renewable energy integration to address client sustainability goals. Strategic partnerships, mergers, and investments in R&D are common approaches to strengthen market presence and expand service portfolios. Regional contractors compete by offering localized solutions, cost efficiency, and flexibility in project execution. Competitive differentiation is driven by the ability to deliver high-performance retrofits that meet evolving safety, environmental, and energy efficiency standards while ensuring minimal disruption to ongoing operations.
Recent Developments:
- In June 2025, Daikin launched the OTERRA 115V Single-Zone Heat Pump Solution in North America, targeting residential heating and cooling markets with a focus on installation and maintenance ease.
- In March 2025, Eaton signed an agreement to acquire Fibrebond Corporation, a modular power enclosure supplier for data centers, expecting to close the transaction in Q3 2025.
- In March 2025, Ameresco announced the acquisition of ASA Controls, enhancing their smart building and automation offerings.
Market Concentration & Characteristics:
The retrofitting services market is moderately consolidated, with a mix of global engineering firms, specialized service providers, and regional contractors competing for market share. It is characterized by high technical expertise requirements, strong regulatory influence, and growing integration of advanced technologies such as IoT, AI-driven energy management, and sustainable materials. Large players leverage extensive project portfolios, strong financing capabilities, and established client networks to secure large-scale contracts, while smaller firms focus on niche applications and localized solutions. The market is driven by long-term service contracts, government-backed modernization programs, and increasing demand for customized retrofit solutions tailored to specific industry and building needs. Competitive differentiation is often based on technological innovation, energy efficiency performance, and compliance with evolving environmental standards.
Report Coverage:
The research report offers an in-depth analysis based on Type, Product, Application and Region. It details leading Market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current Market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven Market expansion in recent years. The report also explores Market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on Market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the Market.
Future Outlook:
- The retrofitting services market will expand significantly due to increasing demand for sustainable infrastructure upgrades and energy efficiency improvements.
- Governments will strengthen regulatory frameworks and offer more incentives to encourage large-scale retrofitting adoption.
- Integration of smart building technologies, including IoT-enabled monitoring and AI-based energy optimization, will become a standard feature in retrofit projects.
- Demand for renewable energy integration, such as solar, wind, and energy storage systems, will rise within both commercial and residential retrofits.
- Public–private partnerships will play a critical role in funding and implementing urban infrastructure modernization initiatives.
- Advanced materials with improved durability, insulation, and environmental performance will gain traction in retrofit applications.
- Emerging economies will witness accelerated growth due to rapid urbanization, infrastructure aging, and increasing environmental awareness.
- The shortage of skilled labor for high-tech retrofitting solutions will drive investment in workforce training and certification programs.
- Retrofitting in industrial facilities will grow as companies seek to improve operational efficiency and reduce emissions.
- The market will experience heightened competition, with innovation in design, cost optimization, and sustainability credentials becoming key differentiators.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Government Incentives and Regulatory Mandates
Stringent building codes, emission regulations, and financial incentives are compelling property owners to invest in retrofitting, ensuring compliance with evolving standards and supporting market growth.
Push for Energy Efficiency and Sustainability
Global efforts to reduce energy consumption and carbon emissions are driving investments in retrofitting, as upgrades to HVAC, lighting, and insulation offer significant operational savings and environmental benefits.
Technological Advancements in Smart Building Solutions
Innovations in IoT, AI-driven analytics, and advanced materials are enabling more efficient, customized, and sustainable retrofitting projects, making upgrades more attractive and cost-effective for building owners.
Aging Infrastructure and Cost-Effective Modernization
With much of the global building stock reaching the end of its operational life, retrofitting provides a practical and less expensive alternative to complete replacement, extending asset life and improving performance.
Urbanization and Infrastructure Development in Emerging Markets
Rapid urban growth and government-led modernization programs in Asia-Pacific, Latin America, and the Middle East are creating new opportunities for retrofitting services, particularly in commercial, industrial, and public infrastructure sectors.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the retrofitting services market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the retrofitting services market projected to grow between 2024 and 2032?
What are the primary factors fueling the growth of the retrofitting services market?
Who are the leading companies in the retrofitting services market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Energy Retrofits
- 1.2.2 Seismic Retrofits
- 1.2.3 Safety and Compliance Retrofits
- 1.2.4 Renewable Energy Integration Retrofits
- 1.2.5 Other Specialized Retrofits
- 1.3 By Product
- 1.3.1 HVAC Retrofitting
- 1.3.2 Lighting Retrofitting
- 1.3.3 Structural Retrofitting
- 1.3.4 Electrical System Upgrades
- 1.3.5 Plumbing and Water System Upgrades
- 1.3.6 Building Automation and Control Systems
- 1.4 By Application
- 1.4.1 Residential
- 1.4.2 Commercial
- 1.4.3 Industrial
- 1.4.4 Public Infrastructure
- 1.4.5 Institutional Facilities
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 133,553.2 million → 2032: USD 243,920.8 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Retrofitting Services Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Retrofitting Services Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Retrofitting Services Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Retrofitting Services Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Retrofitting Services Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Retrofitting Services Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Retrofitting Services Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Retrofitting Services Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 133,553.2 million → 2032: USD 243,920.8 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Retrofitting Services Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Base-Year Market Share, 2024
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Energy Retrofits
- 12.3.6.2 Seismic Retrofits
- 12.3.6.3 Safety and Compliance Retrofits
- 12.3.6.4 Renewable Energy Integration Retrofits
- 12.3.6.5 Other Specialized Retrofits
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Product - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Base-Year Market Share, 2024
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 HVAC Retrofitting
- 12.4.6.2 Lighting Retrofitting
- 12.4.6.3 Structural Retrofitting
- 12.4.6.4 Electrical System Upgrades
- 12.4.6.5 Plumbing and Water System Upgrades
- 12.4.6.6 Building Automation and Control Systems
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Base-Year Market Share, 2024
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Residential
- 12.5.6.2 Commercial
- 12.5.6.3 Industrial
- 12.5.6.4 Public Infrastructure
- 12.5.6.5 Institutional Facilities
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Retrofitting Services End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Retrofitting Services Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Retrofitting Services Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Energy Efficiency and Resource Management
- 15.7 Sustainability, Recycling and Circularity
- 15.8 Technology Roadmap, 2024-2032
- 15.9 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Retrofitting Services Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Daikin Industries Ltd.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 Eaton
- 18.4 Ameresco
- 18.5 Johnson Controls
- 18.6 AECOM
- 18.7 General Electric
- 18.8 Schneider Electric
- 18.9 Siemens
- 18.10 Orion Energy Systems, Inc.
- 18.11 Trane Technologies Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

