
Market Overview
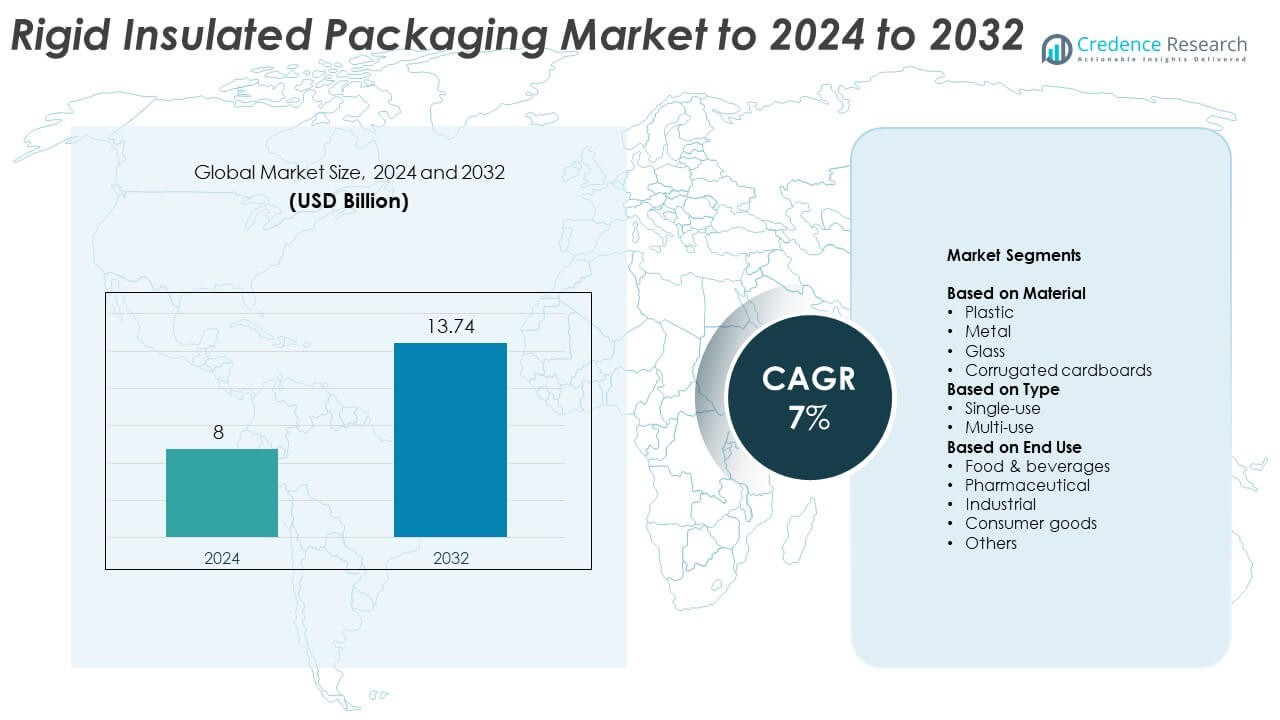
The global Rigid Insulated Packaging Market size was valued at USD 8 billion in 2024 and is anticipated to reach USD 13.74 billion by 2032, at a CAGR of 7% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Rigid Insulated Packaging Market Size 2024 | USD 8 Billion |
| Rigid Insulated Packaging Market, CAGR | 7% |
| Rigid Insulated Packaging Market Size 2032 | USD 13.74 Billion |
The rigid insulated packaging market is dominated by major players such as Cold Chain Technologies, Huhtamaki, Sonoco ThermoSafe, Insulated Products Corporation, Ranpak, MARKO FOAM PRODUCTS, Exeltainer, Cold Ice Inc., TEMPACK, IPG, Smurfit Westrock, Thermal Packaging Solutions Ltd., Lifoam, and Cryopak. These companies lead through innovations in thermal insulation, sustainable materials, and cold chain packaging solutions. Strategic collaborations with logistics and pharmaceutical industries enhance their market reach and reliability. North America emerged as the leading region in 2024, accounting for 34.2% of the global share, driven by strong demand from food, beverage, and healthcare sectors, supported by advanced cold chain infrastructure and regulatory emphasis on product safety.
Market Insights
- The global rigid insulated packaging market was valued at USD 8 billion in 2024 and is projected to reach USD 13.74 billion by 2032, growing at a CAGR of 7%.
- Rising demand for temperature-sensitive packaging in food, beverage, and pharmaceutical industries is a key market driver.
- Technological advancements in recyclable materials and multi-use insulation designs are shaping future market trends and opportunities.
- The market is highly competitive, with companies focusing on sustainable packaging innovations, R&D investments, and regional expansion to gain advantage.
- North America led the market with 34.2% share in 2024, followed by Europe with 28.6% and Asia Pacific with 24.8%, while the plastic segment dominated with a 54.3% share.
Market Segmentation Analysis:
By Material
The plastic segment dominated the rigid insulated packaging market in 2024, accounting for around 54.3% of the total share. Its dominance is driven by high durability, lightweight characteristics, and superior insulation efficiency. Plastic materials, such as polyethylene and polypropylene, are preferred for temperature-sensitive goods due to their moisture resistance and cost-effectiveness. The growing demand for recyclable and bio-based plastic variants further strengthens the segment’s position. Industries are increasingly adopting advanced plastic-based insulated packaging to ensure extended shelf life and maintain product integrity during transportation.
- For instance, Knauf Industries reports EPP thermal conductivity at 0.039 W/mK. This supports high insulation with low weight. The spec underpins PP/EPP dominance in cold-chain boxes.
By Type
The single-use segment held the largest share of approximately 63.5% in 2024, driven by the widespread use in food delivery, pharmaceuticals, and e-commerce logistics. Single-use insulated packaging offers better convenience, lower contamination risk, and high temperature retention for perishable goods. The surge in online food delivery services and vaccine distribution programs has accelerated its adoption. Additionally, the demand for cost-efficient, disposable packaging solutions in urban areas continues to support market growth, while regulatory efforts to promote recyclable single-use options are shaping product innovation.
- For instance, Sonoco ThermoSafe’s ChillTech systems hold 2–8 °C for 48–144 hours. Payloads range from 5 L to 40 L, ISTA 7D/7E qualified. Single-use shippers meet tight lane durations.
By End Use
The food and beverages segment led the market with a 46.8% share in 2024, owing to the increasing demand for temperature-controlled storage and transportation of perishable items. Rigid insulated packaging ensures product freshness, reduces spoilage, and supports safe delivery of dairy, meat, and ready-to-eat foods. The growing expansion of online grocery and meal kit services has intensified adoption in this category. Beverage manufacturers are also integrating high-performance insulated containers to maintain product quality in extended distribution cycles, strengthening the segment’s leadership in the global market.
Key Growth Drivers
Rising Demand for Temperature-Sensitive Goods
The growing need for temperature-controlled transportation of food, beverages, and pharmaceuticals is a major growth driver. Consumers increasingly rely on insulated packaging to preserve product freshness and safety across longer distances. Expanding cold chain logistics networks and e-commerce deliveries of perishable goods further fuel this demand. The adoption of rigid insulated containers that maintain internal temperature stability ensures product integrity, making them essential for industries requiring consistent thermal performance.
- For instance, Va-Q-tec offers the va-Q-one product line of single-use thermal transport boxes in several configurations, with different boxes designed to maintain different temperature ranges. These include options for deep-frozen shipments as low as -70 °C (using dry ice) and others for controlled room temperature, such as +15 °C to +25 °C (using phase change materials).
Expansion of Online Food Delivery and E-commerce
The surge in online food delivery and retail distribution has significantly increased demand for efficient insulated packaging. Rigid insulated containers offer protection against heat, moisture, and external impacts during transit. The rapid growth of e-commerce platforms and doorstep delivery models has led to higher consumption of reusable and single-use insulated boxes. Companies in the food and beverage sector are prioritizing thermal packaging to enhance customer satisfaction and reduce spoilage rates in the last-mile delivery segment.
- For instance, DeltaTrak’s mini PDF logger stores 12,288 data points. Single-use models support trips up to 85 days. Reliable logging secures cold-chain deliveries.
Growing Focus on Sustainable Packaging Materials
The shift toward recyclable and eco-friendly packaging materials is driving innovation in the market. Manufacturers are developing rigid insulated solutions using recyclable plastics, molded pulp, and biodegradable composites to reduce environmental impact. Governments are also supporting sustainable production through regulations and incentives promoting waste reduction. This growing emphasis on circular economy practices is encouraging companies to redesign packaging systems with reduced carbon footprints while maintaining thermal efficiency and product protection.
Key Trends & Opportunities
Technological Advancements in Insulation Materials
Continuous innovation in insulation technologies is shaping the market landscape. The use of vacuum insulation panels, expanded polystyrene, and polyurethane foams enhances temperature retention and durability. Smart insulated packaging with temperature monitoring sensors is also gaining traction across food and pharmaceutical industries. These technological upgrades provide better control, longer shelf life, and improved supply chain transparency, opening new opportunities for packaging manufacturers to serve high-value sectors.
- For instance, Peli BioThermal’s Crēdo GO is qualified to ISTA 7D. Systems provide 24–120 hours across multiple temperature ranges. Advanced VIP and PCM extend protection.
Rising Adoption of Multi-Use Packaging Solutions
The growing shift toward reusable and multi-use insulated packaging offers significant market potential. Businesses are increasingly adopting returnable packaging systems to minimize waste and lower long-term operational costs. Multi-use containers deliver consistent insulation performance and support sustainability targets by reducing reliance on disposable materials. The logistics and cold storage sectors are major beneficiaries of this trend, as they seek durable packaging alternatives for multiple delivery cycles.
- For instance, CSafe's Silverpod MAX RE, a reusable pallet shipper, provides over 120 hours of qualified thermal protection in the +2 °C to +8 °C temperature range.
Key Challenges
High Production and Material Costs
Rigid insulated packaging often involves advanced materials such as polyurethane foam or vacuum panels, which raise production expenses. The cost-intensive manufacturing process, combined with the need for precise temperature control, limits adoption among small-scale users. Volatility in raw material prices, particularly plastics and metals, further affects profitability. These factors challenge market expansion, especially in price-sensitive regions where cheaper, non-insulated packaging remains preferred.
Environmental and Recycling Limitations
Although sustainability is a major focus, recycling rigid insulated packaging remains complex due to multi-layered materials. Separation and recovery of insulation components are difficult, leading to increased waste disposal challenges. Limited infrastructure for handling insulated waste hampers large-scale recycling initiatives. This constraint pushes manufacturers to explore new material compositions and eco-friendly alternatives that can balance insulation efficiency with recyclability.
Regional Analysis
North America
North America held the largest share of 34.2% in the rigid insulated packaging market in 2024, driven by strong demand from the food, beverage, and pharmaceutical industries. The region benefits from advanced cold chain infrastructure and widespread adoption of temperature-sensitive packaging solutions. Growing e-commerce activities and increasing consumption of ready-to-eat meals further support market growth. The United States dominates the regional market, while Canada is witnessing growing adoption in healthcare logistics and perishable goods transportation, supported by sustainability-focused packaging innovations.
Europe
Europe accounted for 28.6% of the global market share in 2024, driven by strict environmental regulations and a strong focus on sustainable packaging materials. Countries such as Germany, France, and the U.K. are leading in the adoption of recyclable and multi-use insulated packaging solutions. The food delivery and pharmaceutical industries remain key demand generators. The European Union’s emphasis on circular economy principles encourages the use of eco-friendly materials, while innovation in lightweight, reusable packaging further supports long-term market expansion across the region.
Asia Pacific
Asia Pacific captured 24.8% of the rigid insulated packaging market in 2024, supported by rapid industrialization and expanding food delivery networks. The region’s growth is fueled by strong demand from China, Japan, and India, where rising disposable incomes and urbanization boost packaged food consumption. Increasing pharmaceutical exports and temperature-sensitive logistics also contribute to market expansion. Growing awareness of sustainable materials and government initiatives promoting green packaging technologies are encouraging regional manufacturers to invest in recyclable rigid insulated packaging solutions.
Latin America
Latin America represented 7.3% of the global market share in 2024, driven by expanding food processing industries and the growth of cold chain logistics. Brazil and Mexico dominate the regional demand due to increasing exports of perishable food products. The rise of quick-service restaurants and online grocery platforms supports insulated packaging adoption. However, limited recycling infrastructure and fluctuating raw material costs pose challenges. Manufacturers are focusing on affordable, durable packaging alternatives to cater to evolving regional consumer and industrial needs.
Middle East & Africa
The Middle East & Africa accounted for 5.1% of the rigid insulated packaging market share in 2024, supported by growing demand from the pharmaceutical and food delivery sectors. The region’s hot climate drives the need for temperature-controlled packaging to ensure product safety during distribution. Countries such as the United Arab Emirates, Saudi Arabia, and South Africa are investing in advanced cold chain systems. Increasing healthcare infrastructure and packaged food imports are further supporting market growth, while local manufacturers are gradually adopting recyclable insulated packaging materials.
Market Segmentations:
By Material
- Plastic
- Metal
- Glass
- Corrugated cardboards
By Type
- Single-use
- Multi-use
By End Use
- Food & beverages
- Pharmaceutical
- Industrial
- Consumer goods
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The rigid insulated packaging market features strong competition among leading players such as Cold Chain Technologies, Huhtamaki, Sonoco ThermoSafe, Insulated Products Corporation, Ranpak, MARKO FOAM PRODUCTS, Exeltainer, Cold Ice Inc., TEMPACK, IPG, Smurfit Westrock, Thermal Packaging Solutions Ltd., Lifoam, and Cryopak. The competitive environment is driven by innovation in insulation materials, improved temperature control performance, and sustainability-focused product design. Companies are emphasizing lightweight, recyclable, and multi-use packaging solutions to align with global environmental standards. Strategic collaborations with logistics and pharmaceutical firms are enhancing product distribution efficiency and cold chain reliability. Continuous investment in research and development supports advanced thermal management technologies and energy-efficient production processes. Market participants are expanding manufacturing capabilities and strengthening regional presence to meet growing demand across the food, beverage, healthcare, and industrial sectors. Competitive differentiation increasingly depends on material innovation, operational scalability, and compliance with evolving regulatory frameworks.
Key Player Analysis
- Cold Chain Technologies
- Huhtamaki
- Sonoco ThermoSafe
- Insulated Products Corporation
- Ranpak
- MARKO FOAM PRODUCTS
- Exeltainer
- Cold Ice Inc.
- TEMPACK
- IPG
- Smurfit Westrock
- Thermal Packaging Solutions Ltd.
- Lifoam
- Cryopak
Recent Developments
- In 2025, Sonoco announced the divestiture of its ThermoSafe temperature-controlled packaging business to Arsenal Capital Partners
- In 2023, Cryopak introduced Eco Gel, a biodegradable gel pack made from a proprietary blend of natural components.
- In 2023, Huhtamaki launched several sustainable innovations. It introduced fiber-based egg cartons made from 100% recycled North American materials as an alternative to foam packaging.
Report Coverage
The research report offers an in-depth analysis based on Material, Type, End-Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will see rising adoption of eco-friendly and recyclable insulated materials.
- Demand from the food delivery and e-commerce sectors will continue to strengthen.
- Pharmaceutical and healthcare logistics will increasingly rely on advanced thermal packaging.
- Manufacturers will invest in vacuum insulation and smart temperature monitoring technologies.
- Multi-use insulated packaging systems will gain traction to support sustainability goals.
- Asia Pacific will emerge as the fastest-growing regional market driven by industrial expansion.
- Government regulations will encourage the use of biodegradable and reusable materials.
- Partnerships between packaging producers and logistics firms will enhance cold chain efficiency.
- Technological innovation will improve insulation performance and reduce material costs.
- The focus on reducing carbon footprints will drive new product development across industries.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Rigid Insulated Packaging Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Rigid Insulated Packaging Market projected to grow between 2025 and 2032?
Which Rigid Insulated Packaging Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Rigid Insulated Packaging Market?
Who are the leading companies in the Rigid Insulated Packaging Market?
Which region commanded the largest share of the Rigid Insulated Packaging Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 8 billion → 2032: USD 13.74 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Rigid Insulated Packaging Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Rigid Insulated Packaging Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Rigid Insulated Packaging Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Rigid Insulated Packaging Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Rigid Insulated Packaging Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Rigid Insulated Packaging Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Rigid Insulated Packaging Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Rigid Insulated Packaging Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 8 billion → 2032: USD 13.74 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Rigid Insulated Packaging Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Rigid Insulated Packaging Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Rigid Insulated Packaging Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Rigid Insulated Packaging Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
