
Market overview
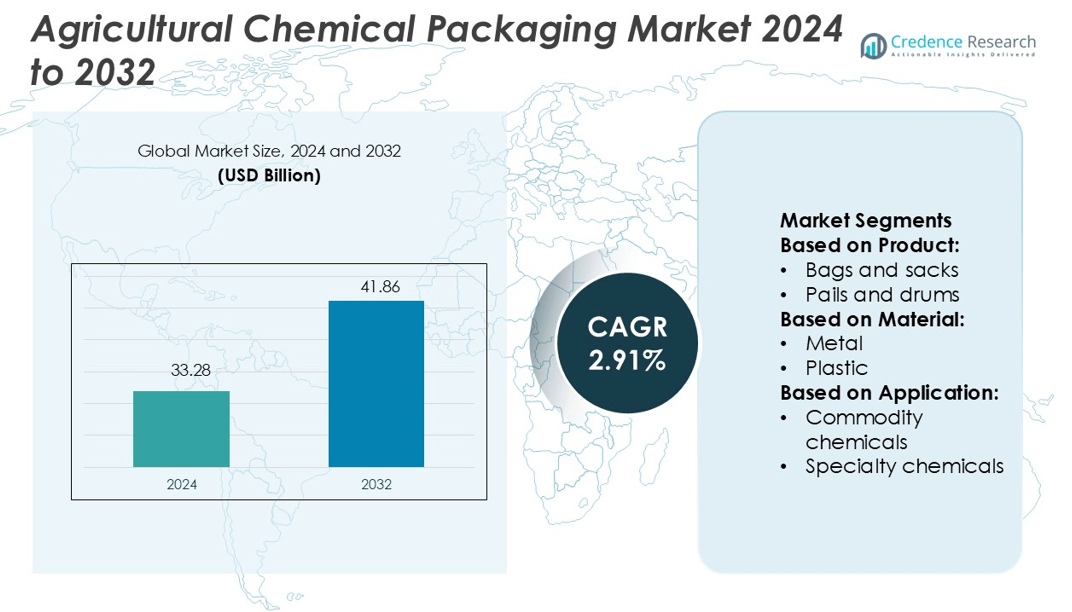
Agricultural Chemical Packaging Market size was valued USD 33.28 billion in 2024 and is anticipated to reach USD 41.86 billion by 2032, at a CAGR of 2.91% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Agricultural Chemical Packaging Market Size 2024 | USD 33.28 billion |
| Agricultural Chemical Packaging Market, CAGR | 2.91% |
| Agricultural Chemical Packaging Market Size 2032 | USD 41.86 billion |
The agricultural chemical packaging market is shaped by prominent players such as Kaufman Container, DS Smith, Hoover CS, Codefine, Advanced Industries Packaging, Champion Plastics, ILC Dover, CDF, LC Packaging, and Fres-co. These companies focus on innovative packaging solutions that ensure product safety, regulatory compliance, and sustainability. They are investing in smart labeling, recyclable materials, and bulk packaging formats to meet rising agrochemical demand. North America emerges as the leading region in this market, holding a 32% share, driven by advanced farming practices, strict safety regulations, and high adoption of sustainable packaging technologies. This leadership reinforces strong competitive positioning and market expansion.
Market Insights
- The agricultural chemical packaging market was valued at USD 33.28 billion in 2024 and is projected to reach USD 41.86 billion by 2032, growing at a CAGR of 2.91% during the forecast period.
- Rising agrochemical use, strict regulatory compliance, and the shift toward sustainable packaging are key drivers supporting steady market growth across major farming economies.
- Smart labeling, bulk packaging, and recyclable materials are shaping new trends, enhancing product traceability and supply chain efficiency.
- The market is dominated by leading players such as Kaufman Container, DS Smith, Hoover CS, Codefine, Advanced Industries Packaging, Champion Plastics, ILC Dover, CDF, LC Packaging, and Fres-co, creating strong competitive pressure.
- North America leads with a 32% regional share, supported by advanced farming practices, while plastic-based packaging dominates segment share due to its durability and cost efficiency.
Market Segmentation Analysis:
By Product
Bags and sacks hold the dominant share in the agricultural chemical packaging market with 38%. Their widespread use in storing and transporting fertilizers, pesticides, and herbicides drives this leadership. The segment benefits from cost-effective production, easy handling, and compatibility with bulk quantities. Manufacturers favor bags and sacks due to their lightweight structure and durability in varying weather conditions. The demand is further supported by increased mechanized farming and efficient supply chains. Their reusability and ease of labeling make them preferred for both commodity and specialty chemicals.
- For instance, DS Smith’s chemical-industry packaging design supports dynamic stacking of 1,300 kg per container during transport of hazardous and bulk materials, and includes RFID‐enabled corrugated solutions that permit tracking of each unit throughout the supply chain.
By Material
Plastic dominates the material segment with a 42% market share. Its high chemical resistance, lightweight structure, and lower production cost make it a preferred choice for agricultural packaging. Plastic containers ensure long shelf life and protection against moisture and contamination. Their adaptability for various product types, including bottles, drums, and IBCs, enhances their use. Growing adoption of advanced polymers and recyclable plastics strengthens this segment’s position. Farmers and distributors rely on plastic for efficient storage, safe transport, and cost control in large-scale farming operations.
- For instance, Hoover CS’s 10-gauge 304 stainless-steel IBC models support maximum gross weights of up to 13,456 lbs (approximately 6,104 kg) in its 793-gallon (3,000 L) unit, as described in its handling manual.
By Application
Commodity chemicals lead the application segment with a 47% market share. Fertilizers and bulk pesticides require durable and cost-effective packaging solutions, making this segment dominant. Bags, sacks, and plastic containers are extensively used to handle high-volume chemical products. Rising demand for crop protection products in commercial agriculture boosts this segment’s growth. Large-scale distribution networks and storage facilities also favor packaging that ensures product stability and easy handling. The increasing use of nitrogen-based fertilizers further fuels packaging demand in this segment.
Key Growth Drivers
Rising Demand for Agrochemicals
The rapid expansion of modern agriculture is driving agrochemical consumption. Farmers are increasingly using pesticides, herbicides, and fertilizers to boost crop yield and quality. This rise in chemical use directly increases demand for durable and safe packaging solutions. Agricultural chemical packaging protects products from contamination and ensures easier transport and storage. It also supports compliance with safety regulations in different countries. Growing global food demand further fuels this packaging market, especially in regions with intensive farming practices and large-scale crop production.
- For instance, Codefine supplies FIBC (Flexible Intermediate Bulk Container) bulk bags tailored for agrochemical and fertilizer transport. The company offers bags with Safe Working Loads (SWL) up to 2,000 kg, and standard single-trip bags are manufactured with a 5:1 Safety Factor, meaning they are tested to withstand five times their rated load before bursting.
Increased Focus on Product Safety and Compliance
Stricter regulations on chemical handling are pushing manufacturers to adopt high-quality packaging. Advanced packaging solutions reduce leakage risks and ensure chemical stability during transportation and storage. Companies are using UN-certified containers, tamper-proof seals, and chemical-resistant materials to meet compliance standards. This trend is especially strong in North America and Europe. Clear labeling and secure closures also enhance traceability, improving overall supply chain safety. As governments tighten safety rules, demand for specialized packaging continues to rise across major agricultural markets.
- For instance, Champion Plastics offers polyethylene film and bags with width ranges from 2 inches up to 200 inches, and gauges from 0.0005″ to 0.010″, enabling high-precision containment for industrial and chemical applications.
Expansion of Sustainable Packaging Solutions
Growing environmental awareness is driving the adoption of sustainable packaging materials. Producers are shifting toward recyclable plastics, biodegradable films, and paper-based containers to meet green packaging targets. Major agrochemical companies are partnering with packaging suppliers to reduce carbon footprints. These solutions appeal to both regulators and environmentally conscious consumers. Advanced sustainable designs also offer durability, chemical resistance, and cost efficiency. This shift supports brand reputation and aligns with global sustainability goals, boosting growth opportunities for eco-friendly packaging providers.
Key Trends & Opportunities
Integration of Smart and Trackable Packaging
The packaging industry is adopting smart technologies to improve product safety and traceability. RFID tags, QR codes, and NFC sensors are increasingly used to monitor agrochemical distribution and prevent counterfeiting. This trend allows real-time tracking of product movement through the supply chain. It enhances regulatory compliance and builds farmer trust. Digital labeling also improves inventory management for distributors. As the agricultural sector embraces digitalization, smart packaging solutions present a strong opportunity for market expansion.
- For instance, DoverPac® High Containment FIBC System meets containment levels of < 0.5 µg/m³, and is built using ArmorFlex® film for robust static-dissipative and solvent-resistant performance.
Growth in Bulk and Refillable Packaging Formats
Large-scale farming operations are driving demand for bulk and reusable packaging solutions. Intermediate bulk containers (IBCs) and pails are becoming popular for efficient chemical handling. These solutions reduce packaging waste and lower logistics costs. Refillable systems also support sustainability targets for agrochemical producers. Many companies are offering returnable container programs to reduce single-use plastics. This trend aligns with operational cost savings and environmental goals, creating new revenue opportunities for packaging manufacturers.
- For instance, CDF launched a new Form-Fit IBC liner manufacturing line in Lienen, Germany, that supports bulk packaging volumes ranging from 220 litres to 1,500 litres.
Rising Adoption of Barrier-Coated and High-Performance Materials
Manufacturers are developing advanced packaging materials with strong chemical resistance and extended shelf life. Barrier-coated plastics and multi-layer laminates protect agrochemicals from moisture, sunlight, and degradation. These innovations improve product stability and minimize spillage. High-performance packaging also helps companies comply with international shipping standards. As agricultural trade expands globally, such material advancements offer competitive advantages. This trend strengthens market growth prospects in regions with diverse climatic conditions.
Key Challenges
Volatile Raw Material Costs
Fluctuating raw material prices pose a major challenge for packaging manufacturers. Most packaging solutions rely on plastic resins and metals, which are sensitive to global oil price changes. These fluctuations impact production costs and profit margins. Smaller manufacturers often face difficulties in absorbing these price shifts. Sudden cost spikes can also delay delivery schedules and strain supplier contracts. This volatility forces companies to explore cost-efficient and alternative materials while maintaining quality standards.
Environmental Regulations and Waste Management
Stringent environmental rules on plastic waste and chemical disposal are challenging for the industry. Many regions are introducing restrictions on single-use plastics and non-recyclable materials. Compliance with these evolving regulations requires high investments in sustainable product development. Waste collection and recycling infrastructure also remain limited in several countries. This creates additional burdens for packaging producers and agrochemical companies. Meeting these regulations without increasing costs is a key challenge that affects overall market expansion.
Regional Analysis
North America
North America leads the agricultural chemical packaging market with a 32% share. The region benefits from advanced farming practices, strong regulatory frameworks, and a high adoption rate of smart packaging solutions. Manufacturers prioritize UN-certified containers, bulk packaging formats, and sustainable materials to meet compliance and environmental goals. Large agrochemical producers rely on durable and tamper-proof packaging for safe transport and handling. Growing demand for precision agriculture and improved chemical traceability supports market growth. The United States dominates regional revenue, with Canada contributing steadily through large-scale crop protection initiatives.
Europe
Europe holds a 27% market share, driven by strict environmental regulations and strong sustainability initiatives. The region has high demand for eco-friendly packaging solutions made from recyclable and biodegradable materials. Agrochemical producers focus on compliance with EU safety standards, leading to increased use of advanced barrier-coated and smart packaging. Bulk and refillable formats are growing rapidly, particularly in Germany, France, and the Netherlands. Rising emphasis on reducing plastic waste and improving supply chain traceability further strengthens market demand across the region, supported by widespread technological adoption in agriculture.
Asia-Pacific
Asia-Pacific accounts for a 24% market share, supported by rapid agricultural expansion and increasing chemical usage. High population growth and rising food demand are driving agrochemical consumption in countries like China, India, and Japan. Manufacturers focus on cost-effective, lightweight packaging suitable for small and bulk quantities. Government initiatives promoting modern farming and pest control boost the adoption of advanced packaging formats. Local players are also investing in sustainable packaging solutions to meet export standards. The region’s strong manufacturing base and expanding farming infrastructure make it a major growth hub.
Latin America
Latin America represents a 10% market share, led by Brazil and Argentina’s large-scale farming operations. The region’s agricultural sector is highly export-oriented, increasing demand for secure and durable agrochemical packaging. Producers prefer intermediate bulk containers (IBCs) and pails to reduce handling costs. Growing adoption of smart labeling and traceability solutions supports compliance with international trade standards. However, limited recycling infrastructure creates barriers for sustainable packaging. Despite this, ongoing investments in modern agriculture and improved logistics networks are driving steady market expansion in the region.
Middle East & Africa
The Middle East & Africa region holds a 7% market share, supported by growing investments in agriculture and irrigation. Countries like Saudi Arabia, South Africa, and the UAE are adopting chemical-based crop protection to increase food security. Packaging demand is rising for both imported and locally produced agrochemicals. Cost-efficient plastic containers and bulk packaging dominate due to affordability and ease of transport. Sustainability adoption is slower compared to other regions, but regulatory changes are encouraging eco-friendly solutions. Expanding agricultural modernization initiatives are expected to boost future market potential.
Market Segmentations:
By Product:
- Bags and sacks
- Pails and drums
By Material:
- Metal
- Plastic
By Application:
- Commodity chemicals
- Specialty chemicals
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the agricultural chemical packaging market features leading players such as Kaufman Container, DS Smith, Hoover CS, Codefine, Advanced Industries Packaging, Champion Plastics, ILC Dover, CDF, LC Packaging, and Fres-co. The agricultural chemical packaging market is defined by continuous innovation and strong regulatory compliance. Companies are focusing on developing advanced packaging formats that enhance product safety, traceability, and sustainability. Eco-friendly materials, including recyclable plastics and biodegradable films, are becoming standard in product lines to meet environmental targets. Bulk and refillable containers are gaining popularity, reducing transportation costs and packaging waste. Many market participants are integrating smart technologies such as RFID tags and QR codes to improve supply chain visibility and reduce counterfeiting. Strategic partnerships with agrochemical manufacturers enable customized packaging solutions. This competitive approach strengthens market growth and encourages consistent technological advancement.
Key Player Analysis
- Kaufman Container
- DS Smith
- Hoover CS
- Codefine
- Advanced Industries Packaging
- Champion Plastics
- ILC Dover
- CDF
- LC Packaging
- Fres-co
Recent Developments
- In January 2025, Borouge secured supply agreements with Bericap, Taghleef Industries, INDEVCO Group, and ALPLA, allocating 80% of contracted polyethylene and polypropylene volumes to fast-growing sectors including agriculture.
- In September 2024, Greif, Inc. opened a new manufacturing facility for Intermediate Bulk Containers (IBCs) used in various industries such as food, chemicals, lubricants, flavors, and fragrances in Pasir Gudang, Johor, Malaysia. The new facility uses advanced manufacturing technologies, including blow molding and cage line technologies, to ensure production meets Greif’s quality and sustainability standards.
- In August 2024, Mauser Packaging Solutions expanded its presence in South Africa by acquiring a plastic drum manufacturing business in Pinetown, Kwa-Zulu Natal. This acquisition extends Mauser's production capacities and footprint in South Africa, enabling the company to offer comprehensive solutions and packaging excellence from five manufacturing and reconditioning facilities.
- In January 2024, StePac, a fresh produce packaging manufacturer, launched a sustainable packaging solution that prolongs the shelf life of exotic mushrooms. This latest advancement in its packaging formats is specifically designed to maintain the freshness of whole and sliced white mushrooms, as well as other exotic varieties, such as oyster, shiitake, lion's mane, and portabell
Report Coverage
The research report offers an in-depth analysis based on Product, Material, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Sustainable packaging adoption will increase as regulatory pressure and consumer awareness grow.
- Smart packaging with tracking features will enhance supply chain transparency.
- Bulk and refillable packaging solutions will gain stronger demand among large farms.
- Advanced barrier coatings will improve chemical stability and product shelf life.
- Investment in recyclable and biodegradable materials will accelerate.
- Digital labeling and QR codes will become standard across major agrochemical brands.
- Automation in filling and sealing processes will improve operational efficiency.
- Strategic partnerships will drive product innovation and regional expansion.
- Emerging economies will become key growth hubs for packaging demand.
- Circular economy practices will reshape packaging design and disposal methods.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Agricultural Chemical Packaging Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Agricultural Chemical Packaging Market projected to grow between 2025 and 2032?
Which Agricultural Chemical Packaging Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Agricultural Chemical Packaging Market?
Who are the leading companies in the Agricultural Chemical Packaging Market?
Which region commanded the largest share of the Agricultural Chemical Packaging Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 33.28 billion → 2032: USD 41.86 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Agricultural Chemical Packaging Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Agricultural Chemical Packaging Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Agricultural Chemical Packaging Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Agricultural Chemical Packaging Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Agricultural Chemical Packaging Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Agricultural Chemical Packaging Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Agricultural Chemical Packaging Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Agricultural Chemical Packaging Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 33.28 billion → 2032: USD 41.86 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Agricultural Chemical Packaging Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Agricultural Chemical Packaging Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Agricultural Chemical Packaging Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Agricultural Chemical Packaging Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

