
Market Overview:
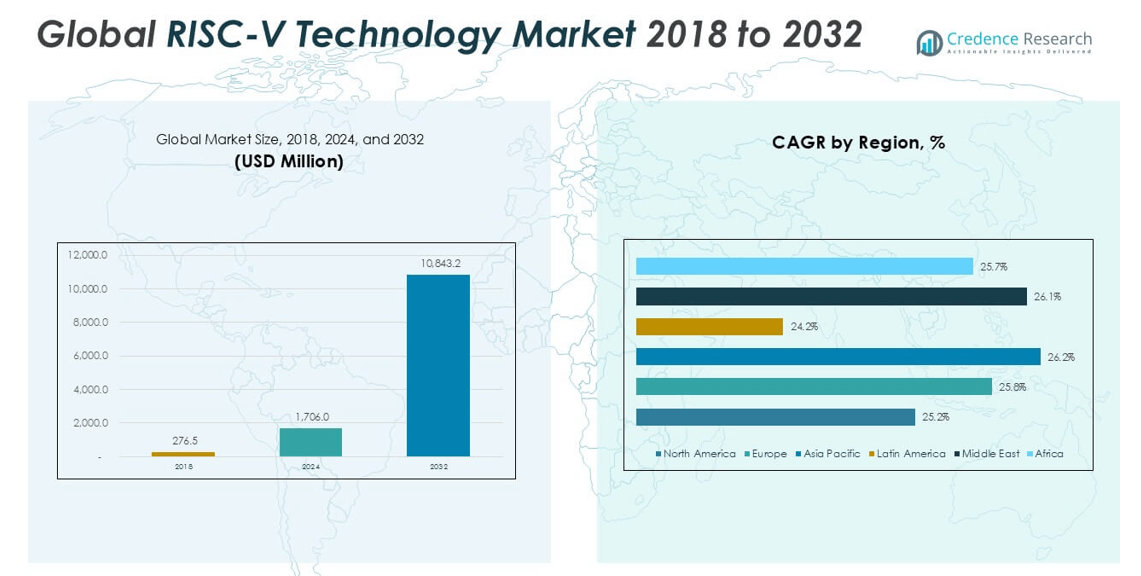
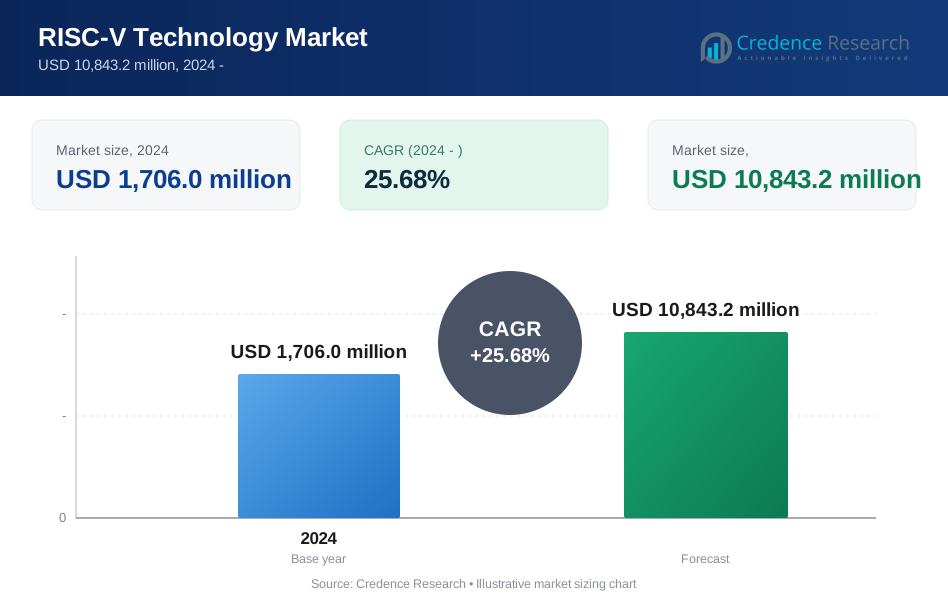
RISC-V Technology market size was valued at USD 276.5 million in 2018 to USD 1,706.0 million in 2024 and is anticipated to reach USD 10,843.2 million by 2032, at a CAGR of 25.68% during the forecast period.| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| RISC-V Technology Market Size 2024 | USD 1,706.0 million |
| RISC-V Technology Market, CAGR | 25.68% |
| RISC-V Technology Market Size 2032 | USD 10,843.2 million |
Market Insights
- The RISC-V technology market was valued at USD 1,706.0 million in 2024 and is projected to reach USD 10,843.2 million by 2032, growing at a CAGR of 25.68% during the forecast period.
- Market growth is primarily driven by the open-source nature of RISC-V, enabling cost-effective and customizable processor development across AI, IoT, and automotive sectors.
- A key trend is the rapid expansion of RISC-V adoption in consumer electronics and industrial automation, supported by an improving software ecosystem and increased collaboration within the developer community.
- The market features strong competition from companies like SiFive, Andes Technology, Intel, and Alibaba’s T-Head, with innovation focused on energy efficiency, performance, and ecosystem integration.
- Asia Pacific leads with a 36.7% market share in 2024, followed by Europe (23.8%) and North America (21.2%), while the hardware segment remains dominant, driven by demand for embedded systems and edge computing solutions.
Market Segmentation Analysis:
By Type The RISC-V Technology market, when segmented by type, is dominated by the hardware segment, which held the largest market share in 2024. Hardware accounts for the bulk of RISC-V integration due to its role in processors, microcontrollers, and embedded systems. Its growth is driven by increased adoption in IoT devices, consumer electronics, and automotive applications. The open-source nature of RISC-V architecture allows hardware developers to customize chips without licensing fees, thereby accelerating innovation. Meanwhile, the software and services segments are gaining momentum as companies seek development tools and support infrastructure to complement hardware deployments.- For instance, SiFive’s U8-Series RISC-V Core IP, introduced in 2020, delivers up to 5.6 SpecINT2006/GHz performance, making it suitable for high-performance computing applications and illustrating the substantial capabilities of RISC-V hardware in commercial deployment.
- For instance, Alibaba’s T-Head division launched the Xuantie C910, a RISC-V processor used in smart home and multimedia devices, capable of achieving up to 2.5 GHz clock speed, demonstrating its suitability for high-demand consumer electronic applications
Market Overview
Open-Source Architecture and Licensing Flexibility
One of the most significant growth drivers for the RISC-V technology market is its open-source architecture, which allows companies to design custom processors without incurring licensing costs. This flexibility encourages innovation and reduces barriers to entry for startups and smaller semiconductor firms. The absence of vendor lock-in enhances transparency, security, and design control, making RISC-V a preferred choice across industries. These advantages are increasingly appealing to companies seeking alternatives to proprietary instruction set architectures (ISAs) like ARM and x86, particularly in cost-sensitive and innovation-driven markets.- For instance, Western Digital has committed to using over 2 billion RISC-V cores per year in its internal products, illustrating how the company capitalizes on RISC-V’s licensing flexibility to customize controllers for its storage devices.
Growing Demand in AI, IoT, and Edge Computing
RISC-V adoption is accelerating in advanced computing fields such as artificial intelligence (AI), Internet of Things (IoT), and edge computing. These applications demand scalable, energy-efficient processors capable of real-time performance. RISC-V's modularity and adaptability make it ideal for customized solutions, enabling developers to optimize performance and power efficiency. As smart devices proliferate and edge computing becomes central to real-time data processing, RISC-V’s architectural advantages position it as a strong alternative to traditional processors in these rapidly expanding markets.- For instance, GreenWaves Technologies’ GAP9, a RISC-V based AI processor, delivers 50 GOPS (Giga Operations Per Second) at 50 mW, exemplifying RISC-V’s capability to enable ultra-low power edge AI processing.
Government and Industry Push for Semiconductor Independence
Geopolitical tensions and supply chain disruptions have spurred global interest in reducing reliance on foreign-controlled chip technologies. Governments and industries are increasingly supporting RISC-V as a path to semiconductor sovereignty, particularly in regions like China, India, and the EU. This trend is further reinforced by public and private funding in RISC-V-based R&D projects and infrastructure. National initiatives promoting open-source hardware are accelerating the deployment of RISC-V cores in defense, aerospace, and critical infrastructure sectors, thus fueling long-term market growth.Key Trends & Opportunities
Expansion into Automotive and Industrial Automation
The RISC-V market is witnessing strong traction in automotive and industrial automation segments. As electric vehicles (EVs), advanced driver-assistance systems (ADAS), and Industry 4.0 technologies demand highly customizable and reliable processors, RISC-V’s adaptability and cost-efficiency present a strategic advantage. Automotive OEMs and industrial manufacturers are exploring RISC-V cores to reduce dependency on legacy ISAs and to foster long-term design flexibility. This trend opens vast opportunities for chip vendors and software ecosystem providers to offer specialized RISC-V solutions tailored to these mission-critical environments.- For instance, Nuclei System Technology’s RISC-V processors have been integrated into over 100 million automotive-grade microcontrollers, supporting real-time control systems for EVs and industrial automation across multiple product platforms.
Ecosystem Maturity and Toolchain Development
The continued maturation of the RISC-V ecosystem—including development tools, software libraries, simulation platforms, and debugging tools—is creating favorable conditions for widespread adoption. Growing support from leading technology companies, such as SiFive, Andes Technology, and Intel, is contributing to a more robust and commercially viable RISC-V platform. As the software and toolchain gap with legacy architectures narrows, more developers and OEMs are likely to transition to RISC-V, opening new revenue streams and accelerating its market penetration across both established and emerging technology sectors.- For instance, Andes Technology reported shipment of over 12 billion AndesCore RISC-V cores as of Q4 2024, demonstrating the impact of ecosystem maturity and robust toolchain support on commercial deployment at scale.
Key Challenges
Limited Software Ecosystem Compared to Legacy Architectures
Despite rapid growth, the RISC-V software ecosystem still lags behind more established architectures such as ARM and x86. Developers face challenges in areas like compiler optimization, operating system support, and compatibility with legacy applications. While efforts are underway to expand RISC-V's software infrastructure, the relative immaturity presents a barrier for companies seeking immediate deployment without significant in-house development. Bridging this ecosystem gap is critical to ensuring smooth adoption and long-term scalability of RISC-V-based solutions across various industries.Integration Complexity and Custom Design Overheads
While the open and modular nature of RISC-V is a strength, it also introduces complexity in integration and customization. Designing RISC-V cores to meet specific performance and power requirements often demands significant engineering expertise and resources. For companies without established chip design capabilities, this can slow down time-to-market and increase development costs. Additionally, ensuring interoperability with existing hardware and software stacks requires thorough validation, making adoption more resource-intensive for certain applications and use cases.Market Fragmentation and Standardization Issues
The flexibility of RISC-V allows for extensive customization, but it also risks leading to market fragmentation. Without strict standardization, variations in implementations may cause compatibility issues across products and vendors. This lack of uniformity can hinder ecosystem scalability, toolchain support, and long-term maintenance. While organizations like RISC-V International are working to define clearer standards, ensuring consistency across implementations remains a challenge that must be addressed to maintain industry confidence and accelerate broader adoption.Regional Analysis
North America: North America accounted for a market size of USD 59.91 million in 2018 and grew to USD 361.57 million in 2024. It is projected to reach USD 2,229.37 million by 2032, expanding at a CAGR of 25.2% during the forecast period. In 2024, the region held a market share of approximately 21.2%, driven by strong technological infrastructure, early adoption of RISC-V in enterprise computing, and rising demand for customizable processors in AI and cloud applications. Significant investments by major chipmakers and active academic participation continue to solidify North America's position in the global RISC-V market. Europe: Europe recorded a market size of USD 65.44 million in 2018 and rose to USD 406.21 million in 2024, with projections reaching USD 2,602.37 million by 2032. Growing at a CAGR of 25.8%, Europe captured nearly 23.8% of the global market share in 2024. The region benefits from robust industrial and automotive sectors increasingly turning to RISC-V for cost-effective and scalable solutions. Government-backed initiatives to boost semiconductor independence and collaborative R&D across nations like Germany and France are further propelling adoption, especially in edge computing, smart manufacturing, and open-source design initiatives. Asia Pacific: Asia Pacific leads the global RISC-V technology market, with a market size of USD 98.92 million in 2018 and USD 625.82 million in 2024. It is expected to surge to USD 4,108.50 million by 2032, at a CAGR of 26.2%. The region held the largest market share of approximately 36.7% in 2024. Growth is fueled by massive semiconductor investments, especially in China, India, South Korea, and Japan. Regional governments and tech firms are prioritizing RISC-V to reduce dependency on Western chip technologies and advance domestic innovation in smartphones, smart devices, and AI-enabled systems. Latin America: Latin America registered a market value of USD 28.23 million in 2018 and USD 162.92 million in 2024, with expectations to reach USD 940.11 million by 2032. The region is growing at a CAGR of 24.2% and held a market share of about 9.6% in 2024. Brazil and Mexico lead adoption, supported by emerging demand for low-power and cost-efficient embedded systems across consumer electronics and industrial applications. While still in the early stages, growing interest in open hardware and academic research is gradually encouraging RISC-V technology uptake throughout Latin America. Middle East: The Middle East RISC-V market grew from USD 13.22 million in 2018 to USD 83.15 million in 2024 and is expected to reach USD 542.16 million by 2032. With a strong CAGR of 26.1%, the region accounted for a 4.9% market share in 2024. Government-led digital transformation programs and investments in local semiconductor capabilities are primary growth drivers. Countries like the UAE and Saudi Arabia are increasingly investing in open-source technologies to drive innovation in telecommunications, IoT infrastructure, and national security systems, thus enhancing the region’s RISC-V market outlook. Africa: Africa's RISC-V market grew from USD 10.75 million in 2018 to USD 66.29 million in 2024 and is projected to reach USD 420.72 million by 2032, registering a CAGR of 25.7%. The region held around 3.9% of the global market share in 2024. While still nascent, Africa is witnessing gradual adoption of RISC-V in academic institutions, startup ecosystems, and select government-backed tech initiatives. Emphasis on low-cost, flexible processor architectures to support education, digital transformation, and indigenous tech development is expected to steadily fuel market growth across the continent.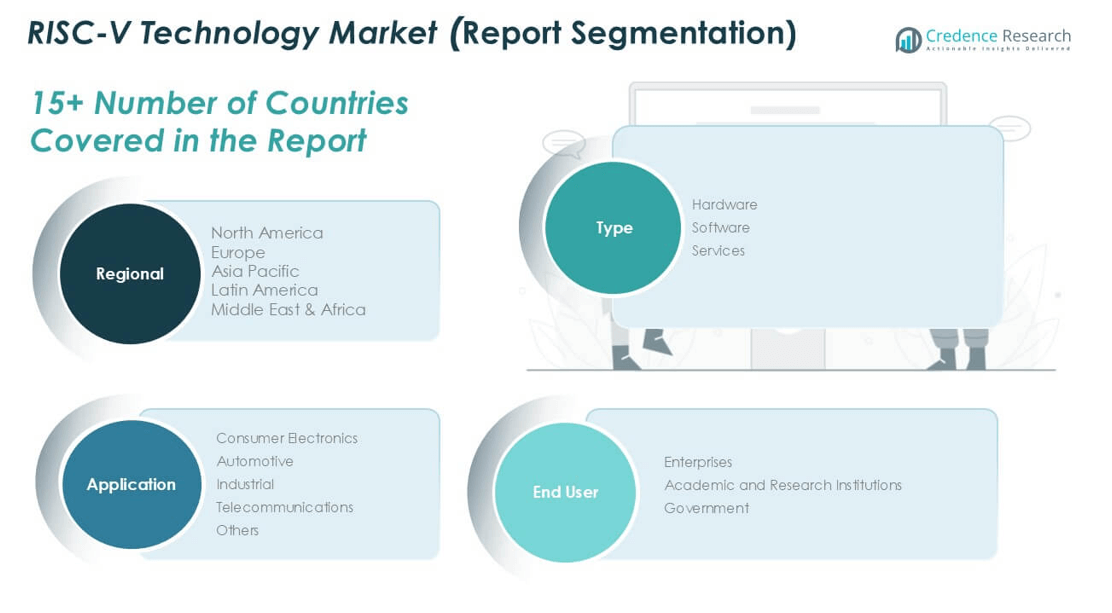 Market Segmentations:
By Type:
- Hardware
- Software
- Services
- Consumer Electronics
- Automotive
- Industrial
- Telecommunications
- Others
- Enterprises
- Academic and Research Institutions
- Government
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the RISC-V technology market is characterized by a mix of specialized startups, established semiconductor companies, and global tech giants, all actively contributing to ecosystem development. Companies like SiFive, Codasip, and Andes Technology are leading in RISC-V core design and licensing, offering customizable IP solutions to support diverse applications. Established players such as Intel, Qualcomm, and NVIDIA are investing in RISC-V to enhance design flexibility and reduce dependency on proprietary architectures. Meanwhile, organizations like Alibaba (T-Head) and Huawei are promoting RISC-V as a strategic alternative to ARM, particularly in China’s drive for semiconductor autonomy. The market also benefits from the collaborative, open-source nature of RISC-V International, which facilitates cross-industry partnerships and standardization efforts. Intense competition is driving innovation in low-power design, scalability, and security features. As the ecosystem matures with better toolchains and software support, competitive dynamics are expected to shift toward performance differentiation and vertical-specific RISC-V solutions.Key Player Analysis
- SiFive
- Andes Technology
- Codasip
- GreenWaves Technologies
- Microchip Technology
- NVIDIA
- Alibaba Group (T-Head)
- Huawei Technologies
- Samsung Electronics
- Intel Corporation
- Qualcomm
- Imagination Technologies
- RISC-V International
Recent Developments
- In January 2025, SiFive's focus was on expanding their software ecosystem, particularly by aligning it with the RISC-V RVA23 Profile and optimizing their RISC-V processors for AI workloads, including large language models. This involved tailoring their silicon to effectively handle the demanding computational needs of AI, with a particular emphasis on edge AI applications.
- In August 2024, Andes Technologyand Resiltech partnered to develop Software Test Libraries (STL) for Andes' automotive-grade RISC-V IP, focusing on enhancing safety and security features. This collaboration aims to provide automotive OEMs and Tier-1 suppliers with robust solutions for fault detection and mitigation in their systems. Resiltech's STLs are designed to streamline the safety certification process, offering a pre-certified product tailored for the target silicon.
- In August 2024, SiFive unveiled the Performance P870-D, a high-performance RISC-V processor designed for AI workloads in data centers. This processor scales up to 256 cores and supports advanced features like RAS (Reliability, Availability, and Serviceability), 57-bit virtual addressing (Sv57), and an IOMMU for virtualization. The P870-D aims to provide high compute density and efficiency for demanding AI tasks, while also being suitable for other workloads like video streaming and storage.
Market Concentration & Characteristics
The RISC-V Technology Market demonstrates moderate to high concentration, led by a small group of key players including SiFive, Andes Technology, and Codasip. These companies shape the market through IP development, strategic licensing, and ecosystem partnerships. It remains innovation-driven, with open-source architecture enabling diverse applications and cost advantages. Competitive dynamics favor firms that can balance customization with scalability and toolchain support. The market shows strong collaboration among hardware vendors, software developers, and academic institutions, reflecting its open and community-centric nature. It is characterized by rapid technological advancement, with new use cases emerging in AI, IoT, and automotive systems. Regional participation varies, with Asia Pacific commanding the highest share, supported by government initiatives and domestic chip development. Europe and North America also maintain strong positions due to established semiconductor infrastructure and enterprise adoption. Entry barriers are moderate, primarily due to the need for design expertise and ecosystem maturity. The market continues to evolve through standardization and strategic alliances.Report Coverage
The research report offers an in-depth analysis based on Type, Application, End User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.Future Outlook
- The RISC-V technology market will continue to grow rapidly due to rising demand for open-source processor architectures.
- Hardware will remain the dominant segment, driven by embedded systems and edge computing applications.
- Consumer electronics will lead application growth, followed closely by automotive and industrial automation sectors.
- Enterprises will maintain the largest end-user share, supported by increased R&D and custom chip development.
- Asia Pacific will retain its lead in regional share, driven by domestic chip initiatives and large-scale adoption.
- Toolchain development and software ecosystem improvements will accelerate market maturity.
- Government investments in semiconductor independence will increase RISC-V adoption across critical sectors.
- Standardization efforts will reduce fragmentation and improve cross-vendor compatibility.
- Strategic partnerships and acquisitions will shape competitive dynamics and expand commercial deployment.
- Adoption in AI, 5G, and IoT will unlock new growth opportunities across high-performance and low-power applications.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the RISC-V Technology Market?
What factors are driving the growth of the RISC-V Technology Market?
What are some challenges faced by the RISC-V Technology Market?
Who are the major players in the RISC-V Technology Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 RISC-V Technology Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global RISC-V Technology Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (the forecast period) (2024: USD 1,706.0 million → forecast year: USD 10,843.2 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 RISC-V Technology Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. RISC-V Technology Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 RISC-V Technology Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 RISC-V Technology Market Drivers
- 3.3 RISC-V Technology Market Restraints & Challenges
- 3.4 RISC-V Technology Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 RISC-V Technology Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 RISC-V Technology Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, RISC-V Technology category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 RISC-V Technology Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. RISC-V Technology Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the RISC-V Technology market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 RISC-V Technology Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 RISC-V Technology Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 RISC-V Technology Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in RISC-V Technology (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New RISC-V Technology Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global RISC-V Technology Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America RISC-V Technology Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe RISC-V Technology Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific RISC-V Technology Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America RISC-V Technology Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East RISC-V Technology Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa RISC-V Technology Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. RISC-V Technology Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
