
Market Overview:
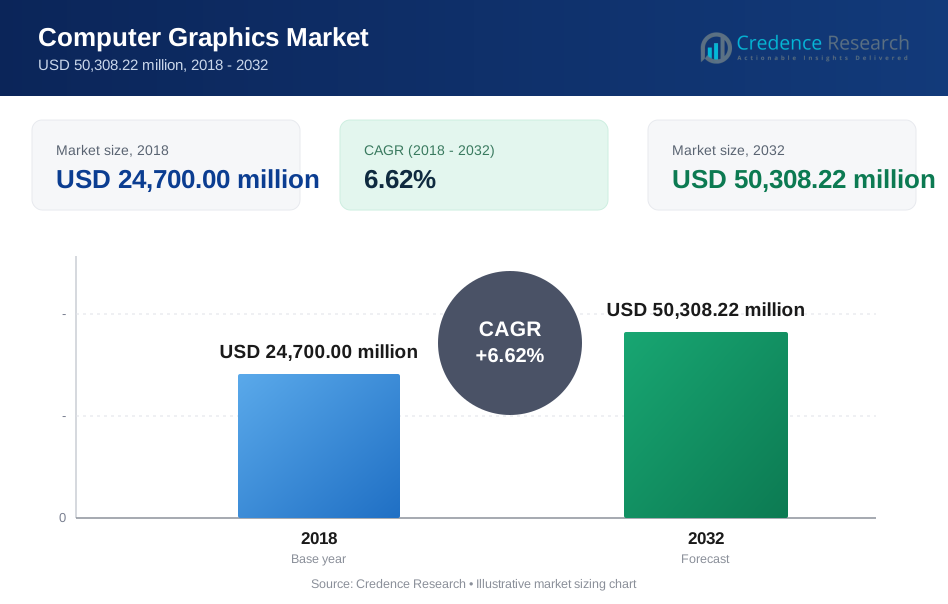
The Computer Graphics Market size was valued at USD 24,700.00 million in 2018 to USD 30,254.70 million in 2024 and is anticipated to reach USD 50,308.22 million by 2032, at a CAGR of 6.62% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Computer Graphics Market Size 2024 | USD 30,254.70 million |
| Computer Graphics Market, CAGR | 6.62% |
| Computer Graphics Market Size 2032 | USD 50,308.22 million |
The Computer Graphics Market is driven by the rising need for high-quality visuals across entertainment, gaming, architecture, and medical imaging. Companies invest heavily in 3D modeling, animation, and simulation tools to enhance design precision and user engagement. The demand for immersive content is pushing innovation in AR, VR, and real-time rendering engines. Educational institutions and enterprises are adopting graphics technologies to improve learning and communication. Cloud-based software deployment, coupled with GPU advancements, continues to expand market access and reduce infrastructure costs, making advanced graphics tools more widely usable.
North America leads the Computer Graphics Market due to its concentration of technology companies, advanced digital infrastructure, and high content consumption. Europe follows with steady growth across automotive design, media production, and simulation-based research. Asia Pacific emerges as the fastest-growing region, driven by rising investments in digital media, gaming, and animation industries in countries like China, Japan, and India. Latin America and the Middle East are expanding through increased media digitization and mobile-first strategies. Africa is developing gradually with growing adoption of visual tools in education, healthcare, and remote communication.
Market Insights:
- The Computer Graphics Market was valued at USD 30,254.70 million in 2024 and is projected to reach USD 50,308.22 million by 2032. This growth is fueled by increasing adoption of real-time rendering and its integration across multiple industries.
- North America and Asia Pacific dominate due to early adoption of advanced graphic technologies. High user engagement and strong tech ecosystems support sustained market leadership in these regions.
- Cloud-based GPU rendering is gaining popularity for reducing dependence on physical infrastructure. This shift enhances accessibility and scalability for small to medium enterprises.
- Mobile-first platforms are accelerating adoption in emerging markets with growing internet penetration. Lightweight applications and responsive design tools are driving usage in mobile-centric regions.
- Data privacy regulations and high implementation costs pose significant challenges to market growth. Enterprises must balance innovation with compliance and financial sustainability.
- AR and VR tools are expanding use cases in healthcare simulations and immersive education. These technologies create engaging learning and diagnostic environments for institutions and professionals.
- AI-driven automation is transforming the way content is created, rendered, and customized. Tools powered by machine learning are streamlining workflows and reducing time to production.

Market Drivers:
Digital Content Creation Across Industries
The Computer Graphics Market benefits from a widespread shift toward digital content creation across industries. Media and entertainment companies increasingly rely on high-resolution graphics for film, animation, and gaming content. The adoption of 3D modeling in architecture and automotive design expands its industrial usage. Real-time rendering capabilities enhance design accuracy and visualization. Educational platforms integrate computer graphics for interactive learning environments. Businesses use graphic interfaces to improve data visualization and decision-making. The healthcare sector’s reliance on imaging software boosts market uptake. These trends make computer graphics integral to digital transformation strategies.
- For example, the viral Dollar Shave Club launch video exemplifies digital content as a direct marketing tool: the advertisement reached 4.7 million views within the first three months, resulting in 12,000 new subscribers within 48 hours. This illustrates the use of targeted, high-impact video production to drive engagement and organizational growth.
Immersive Technologies Driving Demand
Enterprises are integrating immersive technologies such as AR and VR into their operations, fueling demand in the Computer Graphics Market. These applications improve virtual simulations, employee training, and remote collaboration. Gaming companies continue to advance graphic innovations to meet growing consumer expectations for realism. Advanced rendering engines and GPUs deliver high-performance outputs. Software-as-a-service models ease access to sophisticated graphics tools. Cloud computing lowers infrastructure requirements and enables scalability. These advances support broad commercial applications across multiple sectors.
- For instance, Walmart uses VR headsets at over 4,600 U.S. stores for employee training. Their STRIVR platform hosted millions of VR training sessions in 2023, with modules simulating customer service and Black Friday scenarios.
Simulation, Prototyping, and Smart Infrastructure
Increased automation and product design requirements are creating demand for accurate simulation and visualization tools. The Computer Graphics Market meets this need with robust CAD/CAM platforms and advanced simulation software. Industries such as engineering, aerospace, and electronics use graphical models extensively for prototyping and functional testing. Government funding in smart city projects and defense applications generates new opportunities. Businesses leverage 3D visualization for design validation and decision-making efficiency. A growing focus on enhancing customer experiences further accelerates the adoption of advanced graphical user interfaces.
Mobile Optimization and Interactive Experiences
The rapid rise in content consumption through mobile devices necessitates lightweight, optimized graphics. The Computer Graphics Market aligns with mobile-first development strategies in applications and games. Developers utilize adaptive rendering techniques to ensure fluid performance across diverse platforms. Marketing and e-commerce sectors increasingly use 3D product visualizations and immersive storytelling. Social media platforms leverage AR filters and visual content to enhance user engagement. As digital ecosystems continue to expand, reliance on advanced computer graphics becomes essential for driving interactivity and consumer connection.
Market Trends:
AI-Powered Rendering and Workflow Automation
The Computer Graphics Market sees increasing integration of artificial intelligence to enhance rendering techniques and streamline image processing tasks. Deep learning algorithms now improve realism and significantly reduce rendering times in 3D content development. Real-time ray tracing is gaining traction, offering lifelike digital environments for games and simulations. Edge computing minimizes latency, enabling smoother experiences in interactive applications. Browser-based graphics tools are evolving to support better accessibility and team collaboration. Market leaders continue to invest in AI-driven tools to improve workflow efficiency and give creators greater control over design processes.
- For instance, D5 Render implemented AI Atmosphere Matchand D5 Hi to automate repetitive environmental adjustments and accelerate concept generation. This enabled instant, photorealistic 3D scene creation, as seen in their 2025 Architizer A+Product Award-winning projects, and integrated seamless upscaling via D5 AI Enhancer.
Cross-Platform Development and Cloud Rendering
Cross-platform compatibility has become a central theme in the Computer Graphics Market, promoting consistent user experiences across devices. Developers are increasingly adopting web-based graphics APIs to ensure seamless delivery without hardware limitations. Cloud rendering solutions help streamline complex processing tasks, allowing creators to access power-intensive tools remotely. Real-time collaboration through cloud platforms shortens production cycles and supports distributed teams. Companies are improving GPU performance not just for speed but also for energy efficiency. Adaptive resolution and scaling tools enhance performance while maintaining visual standards. These collaborative advancements are reshaping productivity benchmarks across industries.
Augmented Reality and Experiential Graphics
Augmented reality continues to reshape the Computer Graphics Market by creating immersive, interactive experiences across sectors. AR is widely used in virtual try-ons, interactive retail displays, and mobile applications. Smart glasses and wearable tech now extend graphics applications beyond conventional screens. Gesture and voice controls are being adopted to improve creative workflows. Open-source AR platforms foster experimentation and industry innovation. Enterprises use AR for virtual product demonstrations, training simulations, and spatial data visualization. Personalized user experiences further accelerate demand for advanced visual computing, pushing the boundaries of what’s possible with current tools.
- For example, XREAL’s X1-powered AR glasses achieve motion-to-photon latency as low as 3 milliseconds, significantly enhancing real-time responsiveness and visual stability. This ultra-low latency enables smoother overlays and improves the overall user experience, marking a substantial advancement in consumer-grade spatial computing.
Photorealism and Visual Computing Transformation
Demand for photorealistic rendering is rising across industries such as e-commerce, real estate, and marketing within the Computer Graphics Market. High visual fidelity has emerged as a key factor in enhancing customer engagement and brand perception. Companies are deploying GPU clusters and proprietary graphics engines to optimize processing pipelines. The use of digital twins virtual replicas of real-world products is transforming how firms handle design and prototyping. Hybrid workflows that blend procedural and traditional asset creation are becoming the new norm. Evolving licensing models offer flexibility to meet diverse business needs, highlighting the increasing reliance on powerful graphic infrastructures.
Market Challenges Analysis:
Increasing Hardware Complexity and High Costs Limit Accessibility for Smaller Enterprises
The Computer Graphics Market faces mounting challenges due to the growing complexity and cost of advanced hardware. High-performance GPUs, rendering engines, and visualization systems require significant investment, creating a financial barrier for startups and smaller design studios. These enterprises often struggle to compete with larger firms that can afford top-tier infrastructure, thereby slowing broader market democratization. The rapid pace of innovation also forces frequent upgrades, which imposes further cost pressure on existing users. Maintaining compatibility with evolving graphics hardware demands continuous investment in R&D and system integration. This issue restricts adoption in budget-sensitive industries and slows the penetration of new technologies across emerging markets. The Computer Graphics Market must address these limitations to ensure more inclusive growth.
Talent Shortage and Skill Gaps Hamper Efficient Utilization of Advanced Tools
A significant challenge in the Computer Graphics Market is the shortage of skilled professionals capable of leveraging complex tools and software. Despite the proliferation of high-end graphics applications, the talent pool remains shallow, particularly in areas like 3D modeling, VFX, and real-time rendering. Organizations find it difficult to hire or train personnel with deep expertise in both creative and technical domains. This gap reduces operational efficiency and delays production cycles, especially in industries like gaming, animation, and simulation. The need for specialized training programs and industry-academic collaboration has become urgent. It affects the market’s ability to scale and hinders optimal use of sophisticated computer graphics platforms. Addressing the talent deficit is critical for sustaining innovation and maximizing ROI on technology investments.
Market Opportunities:
Integration with Artificial Intelligence and Real-Time Rendering Opens New Avenues
The growing adoption of artificial intelligence in design, simulation, and animation presents a major opportunity for the Computer Graphics Market. AI-powered tools accelerate content creation, automate repetitive processes, and enhance realism in rendered scenes. Real-time rendering technologies are also gaining momentum across industries such as gaming, architecture, and automotive design. It allows faster visualization, iterative development, and immersive user experiences. These capabilities are expanding demand for advanced graphics solutions that combine speed with photorealism. The Computer Graphics Market can leverage these developments to expand into new commercial applications and improve workflow efficiency.
Expansion into AR/VR and Metaverse Applications Enhances Market Reach
Augmented reality, virtual reality, and metaverse platforms are creating new use cases for high-performance graphics engines and visualization tools. The Computer Graphics Market stands to benefit from the rising demand for interactive, 3D-rich environments in both consumer and enterprise settings. Sectors like healthcare, education, retail, and real estate are exploring AR/VR for training, simulation, and customer engagement. It enables highly detailed and dynamic visual communication, which supports more intuitive user interactions. These trends are opening opportunities for software developers and hardware vendors to innovate and differentiate. The expansion into spatial computing is likely to accelerate growth and diversify revenue streams.
Market Segmentation Analysis:
By software segment, includes CAD/CAM, Digital Video, Simulation, Imaging, and Animation. Each of these tools plays a distinct role in different industries such as automotive, architecture, media, and medical visualization. CAD/CAM dominates engineering applications, while animation and digital video drive demand in entertainment. Simulation tools assist in real-time testing and modeling, making them vital in R&D.
- For example, Dassault Systèmes' CATIA is used by automotive giants like BMW for full vehicle design, enabling real-time 3D product modeling and collaborative engineering. BMW leveraged CATIA for rapid vehicle prototyping, reducing design error rates by with built-in simulation modules.
By services segment in the Computer Graphics Market encompasses Consulting, Training and Support, and Integration. Consulting services assist businesses in adopting graphics technology effectively. Training ensures personnel can maximize software performance, while integration connects tools across the enterprise stack. This segment is essential in delivering operational efficiency and seamless user experience.
By vertical segmentation within the Computer Graphics Market includes Packaging, Healthcare, Electronics and Electrical, Automotive, and Others. Healthcare leverages imaging and simulation, while electronics industries use CAD for product design. Automotive design requires advanced modeling tools, and packaging uses visualization for branding. Other sectors include real estate, defense, and education.
By enterprise size, the Computer Graphics Market is segmented into Small and Medium Businesses and Large Enterprises. SMBs adopt cost-effective cloud-based graphic tools, whereas large enterprises implement integrated solutions across multiple departments. This segmentation reflects budget capacity, scalability needs, and strategic use of graphics technology.
- For example, Canva Pro enables SMBs such as boutique marketing agencies to design graphics, presentations, and short animations using an affordable, cloud-based platform. Automatic team workflows and real-time collaboration support remote, distributed teams.

Segmentation:
By Software Segment:
- CAD/CAM
- Digital Video
- Simulation
- Imaging
- Animation
By Services Segment:
- Consulting
- Training and Support
- Integration
By Vertical Segment:
- Packaging
- Healthcare
- Electronics and Electrical
- Automotive
- Others
By Enterprise Size Segment:
- Small and Medium Businesses
- Large Enterprises
By Regions:
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East
- Africa
Regional Analysis:
The North America Computer Graphics Market size was valued at USD 7,377.89 million in 2018 to USD 8,903.78 million in 2024 and is anticipated to reach USD 14,780.65 million by 2032, at a CAGR of 6.6% during the forecast period. North America holds a market share of 25.9% in the Computer Graphics Market, driven by strong demand in the media, gaming, and design industries. It benefits from the presence of leading technology companies and a well-established digital infrastructure. High investment in visual computing, virtual production, and advanced simulation tools supports consistent growth across the region. Enterprises are rapidly integrating GPU-accelerated platforms and real-time rendering into creative and engineering workflows. It also experiences robust demand for cloud-based graphics software and enterprise visualization solutions. Continued innovation in AI-enhanced graphics and extended reality (XR) contributes to the region’s technological edge.
The Europe Computer Graphics Market size was valued at USD 5,293.21 million in 2018 to USD 6,174.16 million in 2024 and is anticipated to reach USD 9,561.21 million by 2032, at a CAGR of 5.7% during the forecast period. Europe accounts for 16.8% of the global Computer Graphics Market, supported by growing applications in automotive design, industrial simulation, and architectural visualization. Countries like Germany, France, and the UK are investing in design-led innovation and 3D content development. The region benefits from strong educational institutions and collaborative research in graphics technologies. It is expanding adoption in real-time digital twins, BIM software, and interactive training tools. Cloud rendering and virtual prototyping continue to gain traction in manufacturing and healthcare. The market is advancing steadily with support from smart city initiatives and creative sector investments.
The Asia Pacific Computer Graphics Market size was valued at USD 9,064.90 million in 2018 to USD 11,431.61 million in 2024 and is anticipated to reach USD 20,339.65 million by 2032, at a CAGR of 7.5% during the forecast period. Asia Pacific dominates the Computer Graphics Market with a 35.7% share, driven by rising demand in gaming, entertainment, and digital manufacturing. Countries such as China, Japan, South Korea, and India are leading in content creation, animation production, and software development. The expansion of consumer electronics, smartphones, and AR/VR platforms boosts market penetration. It also sees increasing use of graphics technologies in education, virtual labs, and mobile applications. Local companies are scaling investment in AI-integrated design tools and GPU-intensive cloud services. Strong growth in e-commerce and online media further accelerates demand for dynamic, high-resolution graphics.
The Latin America Computer Graphics Market size was valued at USD 1,432.60 million in 2018 to USD 1,736.32 million in 2024 and is anticipated to reach USD 2,659.80 million by 2032, at a CAGR of 5.6% during the forecast period. Latin America holds a 4.7% share in the Computer Graphics Market, showing gradual expansion across gaming, education, and digital advertising. Brazil and Mexico serve as key contributors, with increasing interest in animation and 3D rendering tools. The region is witnessing adoption of mobile-based graphics solutions and cost-effective cloud rendering services. It faces challenges in infrastructure and skill development but benefits from a growing pool of digital content creators. It also shows potential for immersive media adoption in healthcare and tourism sectors. Government initiatives in digital education are helping stimulate graphics software usage in academic settings.
The Middle East Computer Graphics Market size was valued at USD 1,012.70 million in 2018 to USD 1,167.63 million in 2024 and is anticipated to reach USD 1,766.10 million by 2032, at a CAGR of 5.4% during the forecast period. The Middle East contributes a 3.3% market share to the Computer Graphics Market, with rising demand in urban development, oil & gas simulations, and virtual learning. Countries like the UAE and Saudi Arabia are investing in digital transformation and smart infrastructure. It is witnessing increasing use of AR/VR and real-time visualization tools in architecture and defense applications. Media and entertainment companies are exploring animation and visual effects to diversify content offerings. Startups and design studios are leveraging cloud platforms to access high-performance graphics processing. The regional market is growing with government support for creative industries and digital education.
The Africa Computer Graphics Market size was valued at USD 518.70 million in 2018 to USD 841.20 million in 2024 and is anticipated to reach USD 1,200.82 million by 2032, at a CAGR of 4.2% during the forecast period. Africa represents a 2.1% share in the global Computer Graphics Market, with increasing activity in mobile gaming, digital media, and online education. South Africa, Nigeria, and Kenya are emerging hubs for content creation and tech innovation. The region shows gradual uptake of cloud-based graphics applications for small businesses and creative agencies. It is limited by infrastructure and access to high-end hardware but benefits from mobile internet penetration. Educational platforms and online design tools are enabling broader adoption in academic and vocational training. The market is poised for growth with regional investments in tech ecosystems and digital talent development.
Key Player Analysis:
- Adobe Systems Ltd.
- Nvidia Corporation
- Autodesk Inc.
- Intel Corporation
- Walt Disney Animation Studios
- Sony Corporation
- Advanced Micro Devices (AMD) Inc.
- Siemens PLM Software
- Oracle PLM
- DreamWorks Animation
- Industrial Light & Magic
- Dassault Systèmes SA
Competitive Analysis:
The Computer Graphics Market exhibits high competition with major players continuously advancing their platforms to gain a technological edge. It is characterized by rapid innovation, particularly in GPU acceleration, rendering engines, and AI integration. Firms invest in R&D and strategic acquisitions to expand service offerings and market reach. Pricing pressures and client customization demand compel vendors to deliver scalable, efficient solutions. Startups are disrupting traditional workflows with cloud-first platforms and open-source toolchains. Established brands leverage deep partnerships and global distribution. Competitive advantage hinges on performance, usability, and ecosystem compatibility.
Recent Developments:
- In March 2025, Adobe unveiled a comprehensive suite of product innovations centered around the Adobe AI Platform at its flagship Adobe Summit. The highlight was the launch of the Adobe Experience Platform Agent Orchestrator, enabling businesses to orchestrate AI agents across Adobe and third-party ecosystems, significantly elevating customer journey orchestration and content supply chain optimization.
- In March 2025, Nvidia announced the winners of its Americas Partner Network awards at the GTC 2025 event, recognizing top solution providers that excel in deploying Nvidia’s full-stack AI platforms. Alongside this, Nvidia revealed the next-generation Blackwell Ultra AI computing platform and continued to expand its ecosystem through strategic partnerships.
- In February 2025, Sony Interactive Entertainment announced it would fully integrate its wholly-owned subsidiary SN Systems, a renowned supplier of PlayStation programming tools, into SIE by April 2025. This integration aims to enhance innovation in tools development for PlayStation and unify operational efficiencies to better empower game developers worldwide.
Market Concentration & Characteristics:
The Computer Graphics Market is moderately concentrated, with a mix of global giants and innovative startups contributing to technological progress. It spans across varied verticals, where each demands tailored graphical solutions. High-entry barriers, proprietary engines, and performance differentiation restrict new competition. Companies with strong portfolios and wide developer networks gain traction. Integration with cloud services and continuous upgrade cycles shape purchasing decisions. Client loyalty depends on quality support, ease of use, and interoperability with third-party applications.
Report Coverage:
The research report offers an in-depth analysis based on Software Segment, Services Segment, Vertical Segment and Enterprise Size Segment. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Increased use of AI in rendering will redefine realism and development efficiency.
- Cloud-based graphic engines will scale access to high-performance tools for all business sizes.
- Gaming and entertainment will continue to drive real-time visual quality innovation.
- AR/VR penetration into education and healthcare will grow significantly.
- Mobile-first optimization will push vendors to develop lighter, scalable graphics.
- Visualization in digital twins will gain momentum in smart city and industrial deployments.
- Simulation and CAD platforms will dominate engineering and defense R&D.
- Graphics-driven marketing content will surge in retail and e-commerce.
- Real-time collaboration in graphics design will become a norm via the cloud.
- Developers will demand interoperability across devices, platforms, and use cases.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Digital Content Creation Across Industries
The shift toward digital content creation in media, entertainment, architecture, and healthcare is fueling demand for advanced computer graphics tools. High-resolution graphics and 3D modeling are now essential for design, visualization, and interactive learning, making computer graphics integral to digital transformation strategies.
Immersive Technologies Driving Demand
The integration of AR and VR in enterprise operations, gaming, and training is accelerating the need for sophisticated graphics engines and real-time rendering. These immersive technologies enhance user engagement, simulation accuracy, and remote collaboration, expanding the market's reach across sectors.
Cloud-Based Graphics and GPU Advancements
Cloud deployment of graphics software and rapid GPU innovation are reducing infrastructure costs and making high-performance graphics tools accessible to a wider range of businesses, including SMBs. This scalability and flexibility are driving broader adoption and enabling new business models.
Simulation, Prototyping, and Smart Infrastructure
Industries such as engineering, automotive, and electronics increasingly rely on simulation and visualization tools for prototyping, testing, and smart infrastructure projects. The demand for accurate, real-time graphical models is boosting the adoption of advanced CAD/CAM and simulation platforms.
Mobile Optimization and Interactive Experiences
The proliferation of mobile devices and mobile-first strategies in emerging markets is driving the need for lightweight, optimized graphics solutions. Interactive 3D content, AR filters, and responsive design tools are enhancing user engagement and expanding the market's footprint in digital marketing and e-commerce.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Computer Graphics Market ?
What factors are driving the growth of the Computer Graphics Market ?
What are the key segments within the Computer Graphics Market ?
What are some challenges faced by the Computer Graphics Market?
Who are the major players in the Computer Graphics Market ?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Enterprise Size
- 1.2.1 Small and Medium Businesses
- 1.2.2 Large Enterprises
- 1.3 By Services Segment
- 1.3.1 Consulting
- 1.3.2 Training and Support
- 1.3.3 Integration
- 1.4 By Software Segment
- 1.4.1 CAD/CAM
- 1.4.2 Digital Video
- 1.4.3 Simulation
- 1.4.4 Imaging
- 1.4.5 Animation
- 1.5 By Vertical Segment
- 1.5.1 Packaging
- 1.5.2 Healthcare
- 1.5.3 Electronics and Electrical
- 1.5.4 Automotive
- 1.5.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2018: USD 24,700.00 million → 2032: USD 50,308.22 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2018
- 2.6.2 Forecast Period: 2018-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2018
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Computer Graphics Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Computer Graphics Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2018-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2018-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Computer Graphics Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2018-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Computer Graphics Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Computer Graphics Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Computer Graphics Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Computer Graphics Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Computer Graphics Market Outlook, 2018-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2018: USD 24,700.00 million → 2032: USD 50,308.22 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2018
- 11.2 Market Forecast, 2018-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Computer Graphics Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2018
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Enterprise Size - Market Size and Forecast, 2018-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2018-2032
- 12.3.4 Volume Forecast, 2018-2032
- 12.3.5 Base-Year Market Share, 2018
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Small and Medium Businesses
- 12.3.7.2 Large Enterprises
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Services Segment - Market Size and Forecast, 2018-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2018-2032
- 12.4.4 Volume Forecast, 2018-2032
- 12.4.5 Base-Year Market Share, 2018
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Consulting
- 12.4.7.2 Training and Support
- 12.4.7.3 Integration
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Software Segment - Market Size and Forecast, 2018-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2018-2032
- 12.5.4 Volume Forecast, 2018-2032
- 12.5.5 Base-Year Market Share, 2018
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 CAD/CAM
- 12.5.7.2 Digital Video
- 12.5.7.3 Simulation
- 12.5.7.4 Imaging
- 12.5.7.5 Animation
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Vertical Segment - Market Size and Forecast, 2018-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2018-2032
- 12.6.4 Volume Forecast, 2018-2032
- 12.6.5 Base-Year Market Share, 2018
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Packaging
- 12.6.7.2 Healthcare
- 12.6.7.3 Electronics and Electrical
- 12.6.7.4 Automotive
- 12.6.7.5 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Computer Graphics End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Computer Graphics Geographic Market Outlook, 2018-2032
- 14.1 Regional Market Size and Share, 2018
- 14.2 Regional Market Forecast, 2018-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Computer Graphics Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2018-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Computer Graphics Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2018
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2018-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Adobe Systems Ltd.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Nvidia Corporation
- 18.4 Autodesk Inc.
- 18.5 Intel Corporation
- 18.6 Walt Disney Animation Studios
- 18.7 Sony Corporation
- 18.8 Advanced Micro Devices (AMD) Inc.
- 18.9 Dassault Systèmes SA
- 18.10 Siemens PLM Software
- 18.11 DreamWorks Animation
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

