
Market Overview:
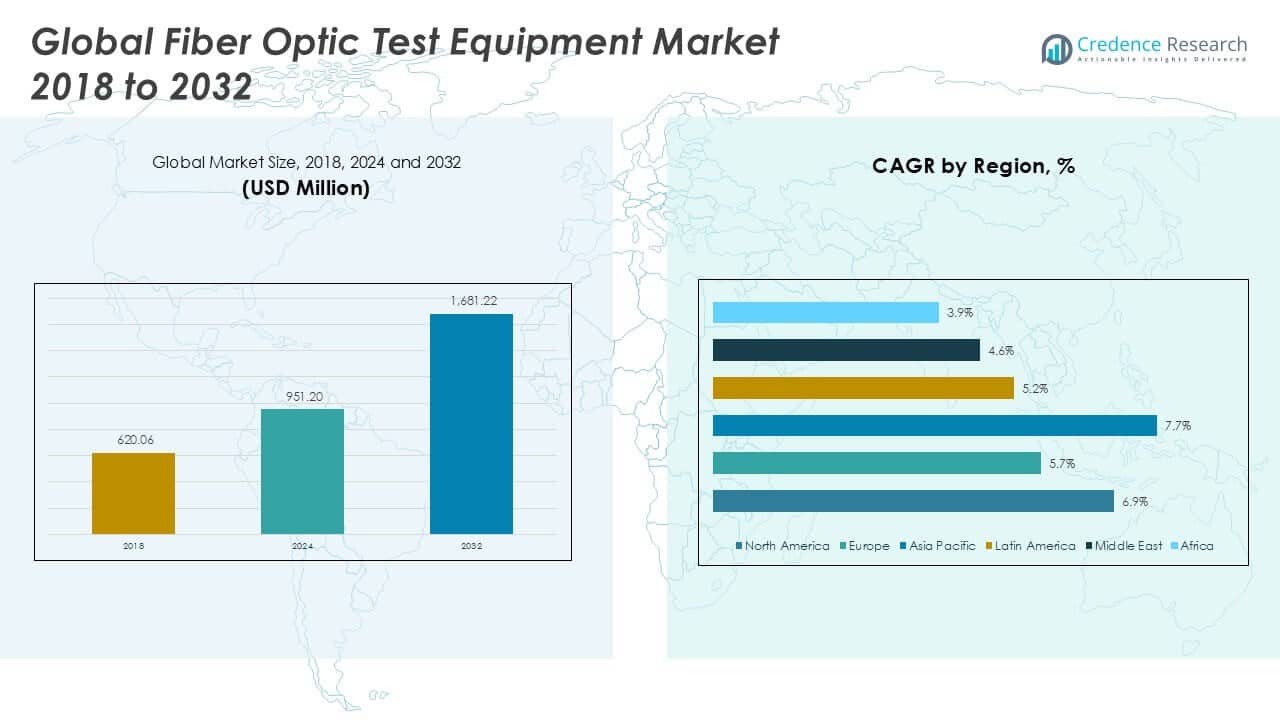
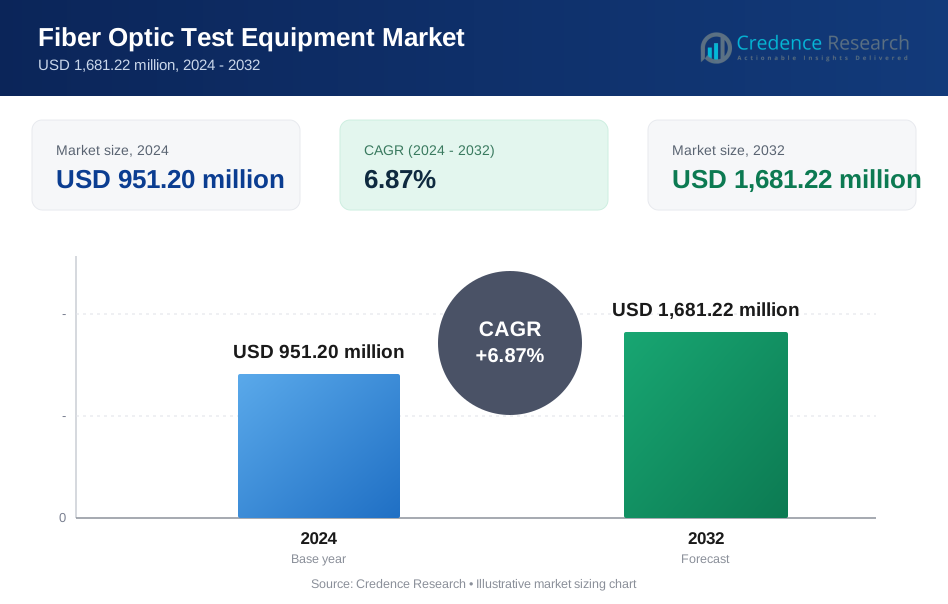
The Global Fiber Optic Test Equipment Market size was valued at USD 620.06 million in 2018 to USD 951.20 million in 2024 and is anticipated to reach USD 1,681.22 million by 2032, at a CAGR of 6.87% during the forecast period
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Fiber Optic Test Equipment Market Size 2024 | USD 951.20 Million |
| Fiber Optic Test Equipment Market, CAGR | 6.87% |
| Fiber Optic Test Equipment Market Size 2032 | USD 1,681.22 Million |
Key market drivers include the growing need for accurate network testing and certification, the rapid proliferation of fiber-to-the-home (FTTH) connections, and increasing investments in smart city initiatives. The market is further supported by ongoing technological advancements in test equipment, such as portable and automated devices, which improve operational efficiency and network reliability for service providers and enterprises. Additionally, the demand for high-speed internet and network optimization across various sectors, including healthcare and education, is driving the market forward.
Regionally, North America holds a significant share of the market, driven by early adoption of advanced communication technologies and substantial investment in network upgrades. The presence of major telecom players and the region's leadership in technological innovation contribute to North America's dominance. Asia-Pacific is expected to witness the fastest growth, fueled by rapid urbanization, government-led broadband initiatives, and the rising presence of data centers, especially in countries like China, India, and Japan. The region is also seeing a surge in demand for fiber optic testing as part of nationwide 5G infrastructure rollouts.
Market Insights:
- The Global Fiber Optic Test Equipment Market was valued at USD 620.06 million in 2018, reached USD 951.20 million in 2024, and is projected to achieve USD 1,681.22 million by 2032, with a CAGR of 6.87% during the forecast period.
- Rapid expansion of fiber optic networks and rising FTTH deployments are creating substantial demand for advanced testing solutions worldwide.
- Technological advancements in portable and automated test equipment are improving operational efficiency and supporting reliable, high-speed network performance.
- High initial investment and ongoing maintenance costs for sophisticated test devices present a significant challenge, especially for SMEs in emerging markets.
- A shortage of skilled technicians and the growing complexity of test equipment can hinder effective network deployment and maintenance.
- North America holds a dominant market share, driven by early adoption of advanced technologies and heavy investment in telecom and data center infrastructure.
- Asia Pacific is poised for the fastest growth, propelled by government-led broadband initiatives, rapid urbanization, and the expansion of digital infrastructure in countries like China, India, and Japan.
Market Drivers:
Increasing Demand for High-Speed Data Transmission
The growing demand for high-speed data transmission is a key driver for the Global Fiber Optic Test Equipment Market. The global expansion of fiber optic networks across telecommunications, data centers, and enterprise applications is creating a significant need for efficient testing solutions. Fiber optics offer unmatched bandwidth, low latency, and reliable performance, making them the preferred choice for modern communication systems. The market benefits from the surge in digital services, such as cloud computing, online streaming, and large-scale enterprise data transfers, which require robust network infrastructure. Fiber optic testing ensures proper installation, reliability, and optimal performance of these high-speed networks.
Proliferation of Fiber-to-the-Home (FTTH) Deployments
Fiber-to-the-home (FTTH) deployments are gaining traction worldwide, fueling the demand for advanced fiber optic testing solutions. As consumers demand faster internet speeds and more reliable connectivity, telecom companies are expanding fiber optic networks directly to homes and businesses. These projects require precise testing of fiber optic cables and components to ensure seamless communication and minimize service disruptions. The Global Fiber Optic Test Equipment Market benefits from the extensive FTTH investments, as it plays a crucial role in network installation, maintenance, and troubleshooting.
- For instance, Lumos Fiber operates a 7,500-mile fiber network and provides high-speed connectivity to 475,000 homes in the Mid-Atlantic region.
Technological Advancements in Test Equipment
Advancements in fiber optic test equipment technologies are another driving factor for market growth. Innovations such as portable and automated testing solutions are enhancing operational efficiency and reducing testing time. These solutions enable network technicians to perform comprehensive tests on-site, increasing productivity and accuracy. The integration of digital technologies, such as cloud-based reporting and real-time analytics, further improves decision-making and troubleshooting processes. These technological developments are expected to drive continuous demand for state-of-the-art fiber optic test equipment.
- For instance, EXFO’s FTB Lite 700 series OTDRs, introduced in 2025, offer always-connected testing with seamless cloud integration, enabling real-time job tracking and data sharing for fiber deployments across the field.
Government Initiatives and Smart City Investments
Government initiatives and investments in smart cities are playing a pivotal role in expanding the market. Nations are increasingly allocating budgets to develop modern, fiber-based communication infrastructure to support smart city projects. These include public services like smart traffic management, e-governance, healthcare, and education. Fiber optic networks form the backbone of these initiatives, requiring precise testing during installation and upgrades. As governments continue to invest in such infrastructure, the Global Fiber Optic Test Equipment Market stands to benefit from sustained demand across regions.
Market Trends:
Advancements in Automation and Remote Monitoring
The Global Fiber Optic Test Equipment Market is witnessing a shift towards automation and remote monitoring solutions. The Remote Fiber Test System (RFTS) segment is projected to exhibit the highest growth rate of approximately 8% during the forecast period 2024–2029 . These systems enable network operators to remotely monitor and diagnose fiber optic cable issues without dispatching technicians to the field. This capability is particularly valuable for maintaining extensive networks in hard-to-reach areas, reducing operational costs and improving response times. The integration of artificial intelligence (AI) with Optical Time Domain Reflectometers (OTDRs) further enhances fault detection and localization, offering predictive maintenance capabilities that minimize downtime and extend the lifespan of fiber optic infrastructures.
- For instance, an AI-powered OTDR deployment at Nokia Bell Labs demonstrated the ability to analyze 180 OTDR trace measurements with high precision and recall for event classification, enabling advanced predictive diagnostics for passive optical networks.
Growth in Demand for Handheld and Portable Testing Solutions
The demand for handheld and portable fiber optic test equipment is on the rise, driven by the need for flexibility and efficiency in field operations. These compact devices allow technicians to perform comprehensive tests on-site, facilitating quicker diagnostics and repairs. The portability of these tools is especially beneficial in urban deployments, where space constraints and the need for rapid service are paramount. The trend towards miniaturization and user-friendly interfaces in test equipment is making fiber optic testing more accessible and efficient, catering to the evolving needs of the telecommunications industry.
- For instance, EXFO's Optical Explorer, launched as the world’s first optical fiber multimeter (OFM), provides automated measurements including fiber length, loss, and optical return loss in under 3 seconds, enabling fast diagnostics in the field and boosting technician productivity.
Market Challenges Analysis:
High Initial Investment and Maintenance Costs
The Global Fiber Optic Test Equipment Market faces significant challenges due to the high initial investment and ongoing maintenance costs of advanced testing equipment. Instruments such as Optical Time Domain Reflectometers (OTDRs) and Optical Spectrum Analyzers (OSAs) are essential for accurate network diagnostics but come with substantial price tags. These expenses can be prohibitive for small and medium-sized enterprises (SMEs), particularly in emerging markets with limited budgets. Additionally, the need for regular calibration and servicing further escalates operational costs, potentially deterring investment in state-of-the-art testing solutions.
Shortage of Skilled Workforce and Technological Complexity
Another pressing challenge is the shortage of skilled technicians capable of operating complex fiber optic test equipment. The rapid evolution of fiber optic technologies necessitates continuous training and expertise to manage sophisticated testing tools effectively. This skills gap can lead to inefficiencies, increased error rates, and delays in network deployment and maintenance. Furthermore, the technological complexity of modern test equipment requires users to possess a deep understanding of both the hardware and software components, complicating the adoption process for organizations without specialized training programs.
Market Opportunities:
Expansion of 5G and Data Center Infrastructure
The ongoing global rollout of 5G networks and the rapid expansion of data centers present significant opportunities for the Global Fiber Optic Test Equipment Market. These developments necessitate the deployment of advanced fiber optic infrastructures capable of supporting high-speed, low-latency communication. Consequently, there is an increasing demand for precise and efficient testing solutions to ensure the reliability and performance of these networks. Companies specializing in fiber optic test equipment can capitalize on this trend by offering products tailored to the specific requirements of 5G and data center environments. This includes developing testing solutions that support high bandwidths, low insertion losses, and rapid fault detection to meet the stringent standards of modern communication systems.
Adoption of Smart Cities and Industrial Automation
The global shift towards smart cities and industrial automation is driving the need for robust fiber optic networks, thereby creating substantial demand for advanced testing equipment. Fiber optics serve as the backbone for various smart city applications, including traffic management, public safety, and environmental monitoring, all of which require reliable and high-performance networks. Similarly, industries adopting automation technologies rely on fiber optic systems for real-time data transmission and control. This trend opens avenues for manufacturers of fiber optic test equipment to develop specialized solutions that cater to the unique challenges of smart city infrastructure and industrial automation, such as ensuring minimal downtime and maintaining optimal network performance.
Market Segmentation Analysis:
By Equipment Type
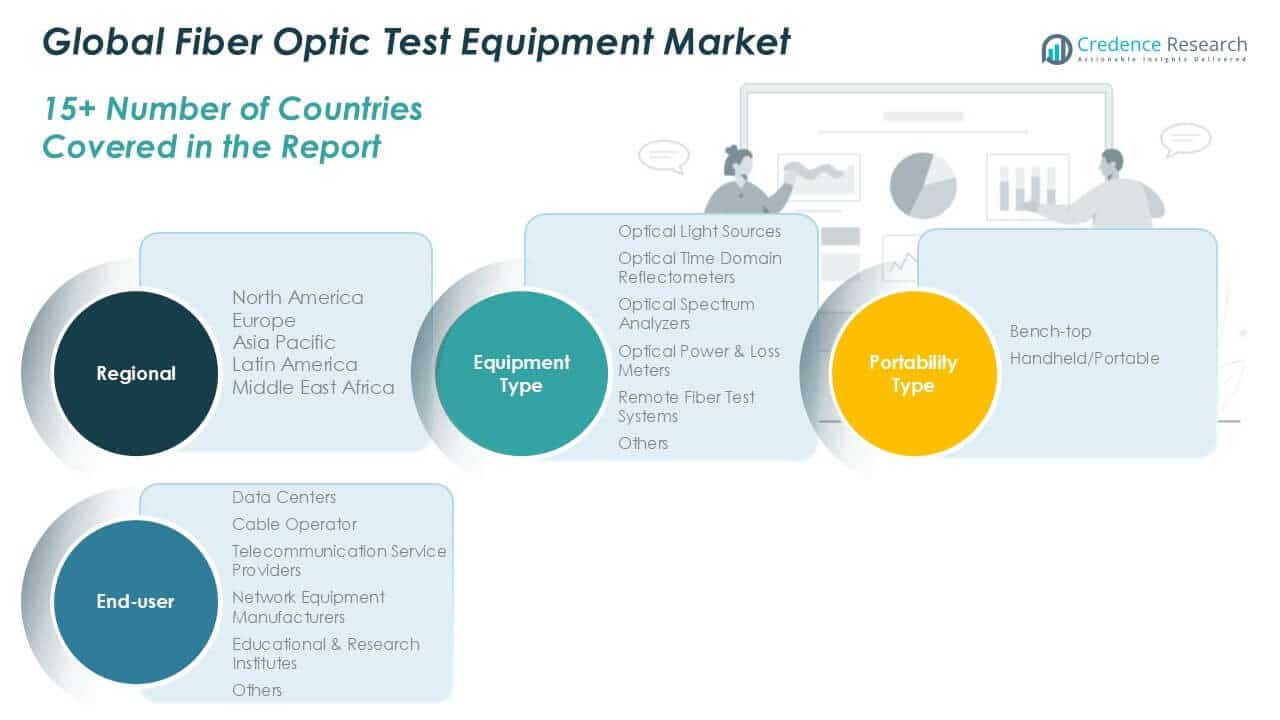
The Global Fiber Optic Test Equipment Market covers a diverse range of equipment, including optical light sources, optical time domain reflectometers, optical spectrum analyzers, optical power and loss meters, remote fiber test systems, and others. Optical time domain reflectometers and spectrum analyzers capture a significant portion of the market due to their critical function in network fault detection and signal performance measurement. Continuous advancements in these devices enhance accuracy and efficiency in fiber optic diagnostics.
- For instance, the Luna OBR 4600 can measure optical fiber latency or length with an accuracy better than 1 millimeter, which for a 30 m fiber corresponds to a latency measurement accuracy of approximately 5 picoseconds.
By Portability Type
Portability remains a vital aspect of fiber optic test equipment, segmented into bench-top and handheld/portable types. Handheld and portable equipment dominate this segment, offering greater convenience for fieldwork, installation, and quick diagnostics. The market increasingly favors lightweight and user-friendly instruments, supporting rapid deployment and flexible maintenance activities across fiber optic networks.
- For instance, the EXFO Max Tester 700B OTDR provides an impressive 12-hour battery life in a handheld design, supporting extended field operations without interruption.
By End-User
Key end-users of fiber optic test equipment include data centers, cable operators, telecommunication service providers, network equipment manufacturers, educational and research institutes, and others. Telecommunication service providers hold the largest share, underlining the critical need for reliable and efficient fiber network infrastructure. The segment also sees growing contributions from data centers and equipment manufacturers focused on maintaining optimal connectivity and supporting large-scale digital operations.
Segmentations:
By Equipment Type:
- Optical Light Sources
- Optical Time Domain Reflectometers
- Optical Spectrum Analyzers
- Optical Power & Loss Meters
- Remote Fiber Test Systems
- Others
By Portability Type:
- Bench-top
- Handheld/Portable
By End-User:
- Data Centers
- Cable Operator
- Telecommunication Service Providers
- Network Equipment Manufacturers
- Educational & Research Institutes
- Others
By Region:
- North America
- Europe
- Asia Pacific
- Latin America
- Middle East
- Africa
Regional Analysis:
North America Fiber Optic Test Equipment Market
The North America Fiber Optic Test Equipment Market size was valued at USD 177.48 million in 2018, reaching USD 267.95 million in 2024, and is anticipated to grow to USD 475.61 million by 2032, at a CAGR of 6.9% during the forecast period. North America holds a significant share of the Global Fiber Optic Test Equipment Market due to the region's early adoption of advanced communication technologies. The United States, in particular, has a robust infrastructure for telecom and data services, which continues to drive the demand for fiber optic testing solutions. Investments in 5G and data center expansion contribute to market growth in the region. The increasing demand for high-speed internet, along with government initiatives to modernize communication networks, further propels the market.
Europe Fiber Optic Test Equipment Market
The Europe Fiber Optic Test Equipment Market size was valued at USD 121.74 million in 2018, reaching USD 177.03 million in 2024, and is expected to reach USD 286.00 million by 2032, at a CAGR of 5.7% during the forecast period. Europe’s market is driven by the increasing need for fiber optic networks, especially in countries like Germany, the UK, and France. The expansion of FTTH networks and the development of 5G infrastructure have significantly influenced market demand. The region’s focus on sustainable development and green technology is also driving innovations in fiber optic testing equipment. The market is supported by the growing demand for high-speed broadband services and network optimization.
Asia Pacific Fiber Optic Test Equipment Market
The Asia Pacific Fiber Optic Test Equipment Market size was valued at USD 264.91 million in 2018, growing to USD 421.73 million in 2024, and is anticipated to reach USD 791.87 million by 2032, at a CAGR of 7.7% during the forecast period. Asia Pacific is expected to witness the highest growth in the Global Fiber Optic Test Equipment Market, driven by rapid urbanization and increasing broadband penetration. Countries such as China, India, Japan, and South Korea are investing heavily in fiber optic networks to support digital transformation, 5G deployment, and smart city initiatives. The demand for fiber optic testing solutions is further boosted by the expansion of data centers and cloud computing services in the region.
Latin America Fiber Optic Test Equipment Market
The Latin America Fiber Optic Test Equipment Market size was valued at USD 28.67 million in 2018, reaching USD 43.42 million in 2024, and is projected to reach USD 67.72 million by 2032, at a CAGR of 5.2% during the forecast period. The region’s market growth is driven by the increasing demand for broadband services, coupled with government initiatives to improve internet connectivity. Brazil and Mexico are the key contributors to market growth, with expanding fiber optic networks and rising investments in telecom infrastructure. The adoption of fiber optics for communication networks and digital transformation is expected to support the continued expansion of the market.
Middle East Fiber Optic Test Equipment Market
The Middle East Fiber Optic Test Equipment Market size was valued at USD 17.44 million in 2018, growing to USD 24.46 million in 2024, and is anticipated to reach USD 36.51 million by 2032, at a CAGR of 4.6% during the forecast period. The Middle East market is experiencing steady growth, driven by the rapid adoption of advanced communication technologies in countries like the UAE and Saudi Arabia. Large-scale infrastructure projects, including the development of smart cities, and investments in 5G and telecom networks are key drivers for fiber optic network expansion. Increasing demand for high-speed internet services and connectivity improvements further support the market’s growth in the region.
Africa Fiber Optic Test Equipment Market
The Africa Fiber Optic Test Equipment Market size was valued at USD 9.83 million in 2018, reaching USD 16.61 million in 2024, and is projected to reach USD 23.52 million by 2032, at a CAGR of 3.9% during the forecast period. The African market is still in its early stages but is steadily growing due to increasing investments in fiber optic infrastructure across key markets like South Africa, Nigeria, and Kenya. Expanding internet access, government-driven telecom projects, and the push for digital connectivity in rural areas are all contributing to the market’s growth. The rise of mobile broadband networks and e-commerce is also creating demand for more reliable fiber optic testing solutions.
Key Player Analysis:
- VIAVI Solutions Inc.
- Yokogawa Electric Corporation
- Landa Corporation Ltd.
- Keysight Technologies
- Fluke Corporation
- EXFO Inc.
- Anritsu
Competitive Analysis:
The Global Fiber Optic Test Equipment Market features a competitive landscape shaped by technological innovation and strategic expansion. Leading players such as EXFO Inc., Anritsu, Keysight Technologies, Fluke Corporation, VIAVI Solutions Inc., Yokogawa Electric Corporation, and Landa Corporation Ltd. drive growth through continuous product development and advanced testing solutions. It benefits from a strong focus on R&D, enabling companies to introduce devices with enhanced accuracy, automation, and ease of use. Market participants form alliances and partnerships to strengthen their market presence and expand their global reach. Competitive pricing and a robust distribution network also play a vital role in sustaining market leadership. Companies compete by offering customized solutions for diverse end-user applications, including telecommunications, data centers, and industrial sectors. This dynamic environment encourages ongoing investment in new technologies and positions the market for sustained advancement and innovation.
Recent Developments:
- In June 2025, Landa Digital Printing initiated a restructuring process to adapt its business structure amid economic and geopolitical uncertainties, including the ongoing war in Israel.
- In February 2025, Anritsu and Ookla announced a partnership to advance network performance and user experience insights.
- In May 2025, Anritsu added Vector Network Analyzer and Vector Voltmeter capability to its Site Master field portable instruments, expanding its solutions for field testing.
Market Concentration & Characteristics:
The Global Fiber Optic Test Equipment Market demonstrates moderate concentration, with a few leading companies controlling a significant share while several regional and niche players compete for the remainder. It is characterized by rapid technological advancements, a strong emphasis on innovation, and a high demand for product reliability and precision. The market places value on user-friendly designs and integration with digital platforms, catering to the needs of telecom, data centers, and network equipment manufacturers. Companies differentiate themselves through extensive R&D, tailored solutions, and robust after-sales support, making continuous improvement and responsiveness key characteristics of the competitive environment.
Report Coverage:
The research report offers an in-depth analysis based on Equipment Type, Portability Type, End-User and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Adoption of AI‑powered diagnostic tools will enhance fault prediction and network maintenance efficiency.
- Integration with cloud platforms will support centralized data analytics and remote monitoring capabilities.
- Portable, multi‑function testers will gain traction among field technicians for their convenience and versatility.
- Demand for higher‑bandwidth testing tools will grow in tandem with 5G and next‑gen optical networks.
- Modular test systems will offer scalable options tailored to varied deployment scenarios.
- Collaboration between test‑equipment manufacturers and telecom operators will accelerate solution innovation.
- Eco‑friendly and energy‑efficient test devices will support sustainability goals within network infrastructure.
- Software‑defined test platforms will allow customizable workflows and protocol support.
- Expansion of smart city projects and IIoT deployments will increase demand for reliable fiber‑optic testing.
- Investment in technician training programs will address the skills gap and support advanced test equipment adoption.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Global Fiber Optic Test Equipment Market?
What factors are driving the growth of the Global Fiber Optic Test Equipment Market?
What are the key segments within the Global Fiber Optic Test Equipment Market?
What are some challenges faced by the Global Fiber Optic Test Equipment Market?
Who are the major players in the Global Fiber Optic Test Equipment Market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Fiber Optic Test Equipment Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Fiber Optic Test Equipment Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 951.20 million → 2032: USD 1,681.22 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Fiber Optic Test Equipment Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Fiber Optic Test Equipment Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Fiber Optic Test Equipment Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Fiber Optic Test Equipment Market Drivers
- 3.3 Fiber Optic Test Equipment Market Restraints & Challenges
- 3.4 Fiber Optic Test Equipment Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Fiber Optic Test Equipment Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Fiber Optic Test Equipment Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Fiber Optic Test Equipment category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Fiber Optic Test Equipment Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Fiber Optic Test Equipment Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Fiber Optic Test Equipment market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Fiber Optic Test Equipment Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Fiber Optic Test Equipment Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Fiber Optic Test Equipment Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Fiber Optic Test Equipment (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Fiber Optic Test Equipment Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Fiber Optic Test Equipment Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Fiber Optic Test Equipment Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Fiber Optic Test Equipment Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Fiber Optic Test Equipment Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Fiber Optic Test Equipment Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Fiber Optic Test Equipment Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Fiber Optic Test Equipment Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Fiber Optic Test Equipment Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
