
Market Overview:
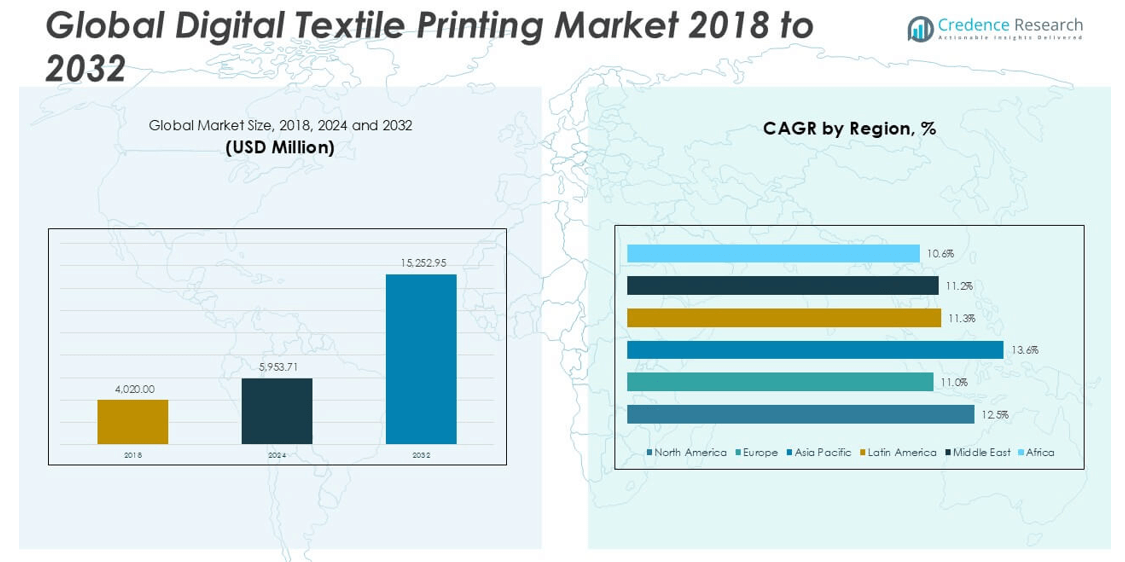
The digital textile printing market size was valued at USD 4,020.00 million in 2018, increased to USD 5,953.71 million in 2024, and is anticipated to reach USD 15,252.95 million by 2032, at a CAGR of 12.52% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Digital Textile Printing Market Size 2024 | USD 5,953.71 million |
| Digital Textile Printing Market, CAGR | 12.52% |
| Digital Textile Printing Market Size 2032 | USD 15,252.95 million |
The digital textile printing market is led by prominent players such as Seiko Epson, Mimaki Engineering, Kornit Digital, D.Gen, Roland DG Corporation, Dover Corporation, Konica Minolta, Brother Industries, and Colorjet. These companies maintain a competitive edge through continuous innovation, strong product portfolios, and strategic geographic expansion. Seiko Epson and Mimaki Engineering hold significant shares due to their advanced printing technologies and broad global reach. Regionally, North America emerged as the leading market in 2024, accounting for 39.7% of the global market share, driven by early adoption of digital printing, high demand for personalized textile products, and the presence of major technology providers.
Market Insights
- The digital textile printing market was valued at USD 5,953.71 million in 2024 and is projected to reach USD 15,252.95 million by 2032, growing at a CAGR of 12.52% during the forecast period.
- Increasing demand for sustainable, on-demand printing and customized designs is driving market growth across fashion, home décor, and soft signage applications.
- Advancements in printing technologies and ink formulations are enabling higher speed, resolution, and fabric compatibility, with cotton holding the dominant share among material segments.
- North America led the market with 39.7% share in 2024, followed by Asia Pacific at 33.7%, driven by the strong presence of leading players and fast-growing textile industries respectively.
- High initial investment and maintenance costs, along with limited material compatibility in certain applications, continue to restrain adoption in small-scale enterprises and emerging regions.
Market Segmentation Analysis:
By Process
In the digital textile printing market, the Direct to Fabric (Roll to Roll Printing) segment dominates the process category, accounting for the largest market share in 2024. This method is widely adopted due to its ability to print large volumes continuously with high speed and cost-efficiency, particularly beneficial for home textiles and soft signage. The growing demand for eco-friendly production and reduction in fabric wastage further drive the adoption of roll-to-roll printing. Additionally, advancements in printer technology and increased usage of pigment inks enhance print quality and durability, strengthening the dominance of this sub-segment.
- For instance, Durst introduced its Alpha series textile printers, which can achieve production speeds up to 1,620 linear meters per hour, offering high-speed roll-to-roll digital pigment printing with integrated drying units
By Operation
Among operation modes, the Multi Pass segment held the dominant market share in 2024. Multi-pass printing remains preferred due to its superior print resolution and ability to produce intricate designs, making it ideal for high-value applications like fashion apparel and custom fabric prints. Although slower than single-pass technology, its flexibility and precision in design output make it more suitable for varied material types and shorter production runs. The rise in customized garment demand and small-batch orders from fashion designers and boutique manufacturers further supports the growth of this segment.
- For instance, Mimaki’s TX300P-1800 multi-pass textile printer supports up to 1,440 x 1,440 dpi resolution with variable drop sizes as small as 4 picoliters, ensuring fine detailing and color depth for fashion applications.
By Material
Within the material segment, Cotton emerged as the leading sub-segment, capturing the highest market share in 2024. Cotton's dominance stems from its widespread use in apparel, household textiles, and sustainable fashion due to its natural, breathable, and biodegradable properties. The surge in eco-conscious consumer behavior and demand for organic textiles amplifies the use of cotton in digital textile printing. Furthermore, compatibility with multiple ink types like reactive and pigment inks, coupled with advancements in pre-treatment processes, supports efficient and high-quality printing on cotton fabrics, reinforcing its position in the market.
Market Overview
Rising Demand for Sustainable and Eco-Friendly Printing Solutions
The shift toward sustainable manufacturing practices is a significant growth driver in the digital textile printing market. Consumers and brands alike are increasingly prioritizing eco-friendly solutions, reducing water usage, energy consumption, and chemical waste. Digital printing enables on-demand production, minimizing overproduction and textile waste. Additionally, advancements in water-based and pigment inks align with global sustainability goals. This push toward greener alternatives is especially influential in markets such as Europe and North America, where stringent environmental regulations are accelerating the adoption of digital textile printing technologies over traditional methods.
- For instance, Kornit Digital’s Presto MAX printer eliminates water usage entirely and achieves up to 95% reduction in energy consumption compared to traditional dyeing methods, while printing up to 450 square meters per hour.
Customization and Short-Run Production Capabilities
The growing demand for personalized and short-run textile products has significantly fueled the adoption of digital textile printing. Unlike traditional bulk printing techniques, digital printing allows for cost-effective customization and rapid design changes, making it ideal for fashion, sportswear, and promotional items. E-commerce platforms and direct-to-consumer brands are leveraging these capabilities to offer unique, limited-edition collections. This trend caters to dynamic consumer preferences and supports efficient inventory management. The flexibility in handling multiple designs, colors, and materials within a short timeframe strengthens the market position of digital textile printing across various end-use industries.
- For instance, Brother GTXpro BULK supports custom one-off garment printing with a print area of up to 40.6 x 53.3 cm, achieving full-color output in less than 60 seconds per piece, enabling efficient short-run production.
Technological Advancements in Printing Equipment and Inks
Ongoing innovations in printing machinery and ink formulations have enhanced the efficiency, speed, and quality of digital textile printing. High-speed single-pass printers, precision nozzles, and improved fabric handling systems have significantly reduced production time while maintaining excellent print resolution. Simultaneously, the development of versatile ink types-such as pigment, sublimation, and reactive inks-has enabled printing on a wide range of fabrics with better color fastness and environmental compliance. These advancements are making digital printing more accessible and competitive, encouraging adoption across small to medium enterprises and established textile manufacturers alike.
Key Trends & Opportunities
Growth of Fast Fashion and On-Demand Manufacturing
The rise of fast fashion and the demand for rapid production cycles present significant opportunities for digital textile printing. Brands are increasingly moving toward on-demand manufacturing to reduce lead times and respond swiftly to changing consumer trends. Digital printing’s flexibility allows for quicker design-to-product timelines, which aligns with the short life cycles of fashion products. This trend also supports sustainability goals by reducing unsold inventory and production waste. The increasing collaboration between fashion designers and digital print service providers is expanding the application scope and revenue potential of the market.
- For instance, EFI Reggiani BOLT is capable of single-pass printing at speeds of up to 90 linear meters per minute, significantly reducing production cycles for on-demand apparel manufacturing.
Expansion in Home Décor and Interior Applications
Home décor and interior furnishing segments are emerging as promising areas for digital textile printing. The ability to customize curtains, cushions, upholstery, and wall coverings with intricate and vibrant designs is driving the application of digital printing in residential and commercial spaces. Consumers’ preference for personalized home aesthetics, combined with the rise in urban housing and remodeling activities, supports this trend. Additionally, advancements in fabric durability and UV-resistant inks make digital printing suitable for interior applications, providing long-lasting and visually appealing products.
- For instance, HP’s Stitch S1000 printer enables high-quality dye-sublimation for polyester-based interior textiles, delivering output speeds up to 220 m²/hour with color consistency and wash durability tested for over 25 laundering cycles.
Key Challenges
High Initial Investment and Maintenance Costs
One of the primary challenges hindering the widespread adoption of digital textile printing is the high initial investment required for advanced printers and associated software. Small and medium-sized enterprises often find the cost of setup and maintenance prohibitive. Additionally, skilled operators are necessary to manage digital workflows and ensure optimal print quality. The cost of specialty inks and pre-treatment chemicals further adds to the operational expenditure. These financial barriers can delay adoption, particularly in emerging economies where budget constraints are more pronounced.
Limited Color Fastness and Fabric Compatibility
Despite significant progress, digital textile printing still faces limitations in color fastness and material compatibility compared to traditional methods. Some ink types struggle to achieve long-lasting prints on certain fabrics without extensive pre- or post-treatment. For instance, pigment inks may not deliver the same vibrancy or wash durability on polyester as they do on cotton. These technical limitations restrict the versatility of digital printing across all textile categories, posing a challenge for market expansion into applications demanding higher performance standards.
Environmental and Regulatory Compliance Issues
While digital textile printing is generally more sustainable than traditional methods, compliance with environmental regulations remains a challenge. Inks and pre-treatment agents must meet safety and sustainability standards across different regions. The lack of uniform global regulations creates complexity for manufacturers and exporters. Additionally, improper disposal or treatment of digital printing waste, such as used cartridges and chemical-laden fabrics, can have environmental impacts. Navigating these compliance requirements demands consistent investment in R&D and quality control systems, which can be burdensome for smaller players.
Regional Analysis
North America
North America held the largest share of the digital textile printing market in 2024, valued at USD 2,367.16 million, growing from USD 1,616.04 million in 2018. It is projected to reach USD 6,056.97 million by 2032, registering a CAGR of 12.5% during the forecast period. In 2024, the region accounted for approximately 39.7% of the global market share. The strong presence of key industry players, demand for customized apparel, and early adoption of digital printing technologies have driven regional growth. Moreover, sustainable printing practices and the popularity of on-demand fashion further support market expansion.
Europe
Europe recorded a market size of USD 811.33 million in 2024, up from USD 588.93 million in 2018, and is expected to reach USD 1,864.71 million by 2032, expanding at a CAGR of 11.0%. The region held about 13.6% of the global digital textile printing market share in 2024. European countries lead in sustainable textile production and have well-established fashion industries, which fuel digital textile printing adoption. Strict environmental regulations and the growing use of eco-friendly pigment inks have also supported the transition from traditional printing methods to digital alternatives across the region.
Asia Pacific
Asia Pacific is the fastest-growing region in the digital textile printing market, with a CAGR of 13.6% between 2024 and 2032. The market size increased from USD 1,314.54 million in 2018 to USD 2,011.44 million in 2024, and is projected to reach USD 5,556.66 million by 2032. With a 33.7% market share in 2024, the region benefits from the presence of major textile manufacturing hubs like China, India, and Bangladesh. Rising demand for cost-effective and high-quality printing solutions, coupled with growing fashion and home décor industries, continues to accelerate digital printing adoption across the region.
Latin America
Latin America’s digital textile printing market grew from USD 217.08 million in 2018 to USD 317.87 million in 2024 and is projected to reach USD 745.41 million by 2032, registering a CAGR of 11.3%. The region accounted for around 5.3% of the global market share in 2024. Growth is driven by increased investments in textile production and a rising preference for customized prints in fashion and promotional products. Countries like Brazil and Mexico are witnessing a gradual shift toward digital technologies due to improved accessibility and the need for shorter production runs.
Middle East
The Middle East digital textile printing market was valued at USD 230.97 million in 2024, up from USD 165.62 million in 2018, and is expected to reach USD 538.51 million by 2032, growing at a CAGR of 11.2%. In 2024, the region represented approximately 3.9% of the global market share. Increasing demand for luxury textiles, personalized clothing, and growth in tourism-driven interior décor contribute to regional market expansion. Additionally, governments are investing in diversifying non-oil industries, including textiles, which promotes the adoption of advanced printing technologies across the Middle East.
Africa
Africa’s digital textile printing market reached USD 214.95 million in 2024 from USD 117.79 million in 2018 and is forecasted to grow to USD 490.68 million by 2032, at a CAGR of 10.6%. The region accounted for about 3.6% of the global market share in 2024. Growth in the African market is supported by the rise of small-scale garment enterprises, increasing access to digital printing equipment, and growing consumer interest in culturally inspired, customized apparel. Though adoption is still in early stages, initiatives to modernize the local textile industry and improve trade infrastructure are gradually accelerating market penetration.
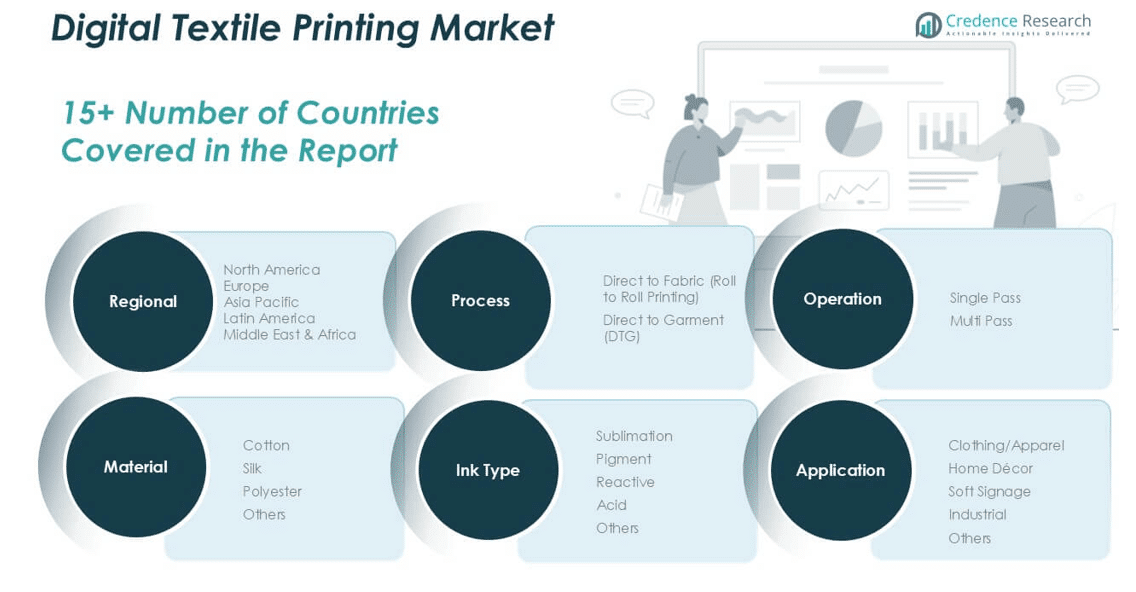
Market Segmentations:
By Process
- Direct to Fabric (Roll to Roll Printing)
- Direct to Garment (DTG)
By Operation
- Single Pass
- Multi Pass
By Material
- Cotton
- Silk
- Polyester
- Others
By Ink Type
- Sublimation
- Pigment
- Reactive
- Acid
- Others
By Application
- Clothing/Apparel
- Home Décor
- Soft Signage
- Industrial
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the digital textile printing market is characterized by the presence of several global and regional players striving to enhance their market share through technological innovation, strategic partnerships, and geographic expansion. Leading companies such as Seiko Epson, Mimaki Engineering, Kornit Digital, D.Gen, and Roland DG Corporation dominate the market with strong product portfolios and advanced printing solutions tailored to various end-user needs. These players consistently invest in R&D to develop high-speed printers, eco-friendly inks, and automated workflows. Meanwhile, companies like Dover Corporation, Konica Minolta, Brother Industries, and Colorjet focus on expanding their presence in emerging markets by offering cost-efficient and scalable printing solutions. Mergers, acquisitions, and collaborations are also common strategies to strengthen distribution networks and technological capabilities. The market remains moderately fragmented, with competition intensifying due to rising demand for customized textiles and sustainable printing practices, prompting firms to prioritize innovation and customer-centric solutions.
Key Player Analysis
- Seiko Epson
- Mimaki Engineering
- Kornit Digital
- Gen
- Roland DG Corporation
- Dover Corporation
- Konica Minolta
- Brother Industries
- Colorjet
Recent Developments
- In July 2025, Mimaki showcased its innovative TRAPIS textile pigment transfer printing system at Texworld Paris and Texworld NYC. This two-step, nearly waterless solution is designed for home textiles and apparel, significantly reducing water consumption by up to 90% compared to traditional methods. TRAPIS utilizes eco-certified, user-safe ink and allows for vibrant prints on a wide range of fabric types.
- In June 2025, Roland introduced the VersaSTUDIO BN2-30 eco-solvent printer/cutter and the BD-12 UV direct-to-object printer. The BN2-30, with its compact design and 736mm material width, is aimed at boosting productivity for businesses needing high-quality, contour-cut textile transfers, labels, and décor. The BD-12, on the other hand, focuses on direct printing onto a variety of objects, including cylindrical items with an optional rotary axis.
- In June 2025, Epson launched its Direct to Shape Printing System, which integrates compact S800 PrecisionCore printheads with Epson industrial robots to enable high-quality inkjet printing directly onto 3D objects. This technology, which includes printing on textiles and complex surfaces, improves automation, printing flexibility, and sustainability. The system reduces material and energy consumption, promoting eco-friendly digital manufacturing in the textile sector.
- In May 2025, At FESPA 2025, Kornit Digital launched Apollo, a high-throughput Direct-to-Garment (DTG) printing system bridging traditional screen and digital workflows. Apollo is aimed at enabling scalable, on-demand, mass customization with reduced environmental footprint and higher workflow flexibility, supported by Kornit's All-Inclusive Click pricing for predictable cost structure.
- In May 2025, Epson enhanced its dye-sublimation printer offerings with the introduction of the SureColor F11070 and F11070H models. These printers are designed for high-speed, high-volume textile printing, incorporating features like extended ink options and a focus on sustainability. The new models aim to deliver vibrant, vivid prints while minimizing water and energy consumption.
Market Concentration & Characteristics
The Digital Textile Printing Market demonstrates a moderately concentrated structure, with a few dominant players such as Seiko Epson, Kornit Digital, Mimaki Engineering, and Roland DG Corporation holding significant market shares. These companies lead through strong technological capabilities, extensive distribution networks, and diverse product portfolios. The market features high entry barriers due to the capital-intensive nature of digital printing equipment, the need for skilled labor, and proprietary ink formulations. It is highly dynamic, shaped by rapid innovation, evolving consumer preferences, and shifting environmental regulations. Customization, shorter production cycles, and eco-friendly practices define key operational characteristics. Demand for sustainable textiles and personalized prints drives competition across developed and emerging economies. The market exhibits strong growth potential in Asia Pacific and Latin America, supported by expanding textile manufacturing bases. Pricing pressure persists due to rising competition, but product differentiation through technology, speed, and material versatility enables leading companies to maintain a competitive edge.
Report Coverage
The research report offers an in-depth analysis based on Process, Operation, Material, Ink Type, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will continue to expand due to rising demand for personalized and short-run textile production.
- Technological advancements in high-speed and multi-material printers will improve production efficiency.
- Sustainable printing solutions will gain more traction as environmental regulations tighten globally.
- Fashion and apparel will remain the dominant application segment, supported by fast fashion trends.
- Home décor and interior textile printing will grow steadily, driven by consumer preference for customization.
- Asia Pacific will strengthen its position as a major production hub due to cost advantages and industrial capacity.
- Cloud-based design software and automation integration will streamline workflows across textile printing operations.
- The use of pigment inks will increase due to their broad fabric compatibility and lower environmental impact.
- Strategic partnerships and acquisitions will shape the competitive landscape and drive product innovation.
- Small and medium enterprises will adopt digital printing as solutions become more accessible and cost-effective.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Sustainable and Eco-Friendly Printing Solutions
The shift toward sustainable manufacturing and eco-friendly printing is accelerating digital textile printing adoption, as brands and consumers seek to reduce water, energy, and chemical usage. Digital processes enable on-demand production, minimizing waste and aligning with stringent environmental regulations, especially in Europe and North America.
Customization and Short-Run Production
Digital textile printing allows for cost-effective, rapid customization and short production runs, which is increasingly demanded by fashion, sportswear, and home décor brands. The ability to efficiently produce unique, limited-edition designs supports e-commerce and direct-to-consumer business models.
Technological Advancements in Printing Equipment and Inks
Continuous innovation in high-speed printers, precision nozzles, and versatile ink formulations has improved print quality, speed, and fabric compatibility. These advancements make digital textile printing more accessible and competitive, encouraging adoption by both large manufacturers and SMEs.
Growth of Fast Fashion and On-Demand Manufacturing
The fast fashion industry’s need for rapid design-to-product cycles and reduced inventory waste is driving the adoption of digital textile printing. On-demand manufacturing enabled by digital printing supports quick response to changing trends and sustainability goals.
Expansion in Home Décor and Interior Applications
Rising consumer preference for personalized home textiles and the growth of urban housing are boosting demand for digitally printed curtains, upholstery, and wall coverings. Improved fabric durability and ink performance are making digital printing more viable for interior applications.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected market size of the Digital Textile Printing Market by 2032?
What drives the growth of the digital textile printing market?
Which regions dominate the digital textile printing market?
What challenges does the market face?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Process
- 1.2.1 Direct to Fabric (Roll to Roll Printing)
- 1.2.2 Direct to Garment (DTG)
- 1.3 By Material
- 1.3.1 Cotton
- 1.3.2 Silk
- 1.3.3 Polyester
- 1.3.4 Others
- 1.4 By Operation
- 1.4.1 Single Pass
- 1.4.2 Multi Pass
- 1.5 By Application
- 1.5.1 Clothing/Apparel
- 1.5.2 Home Décor
- 1.5.3 Soft Signage
- 1.5.4 Industrial
- 1.5.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
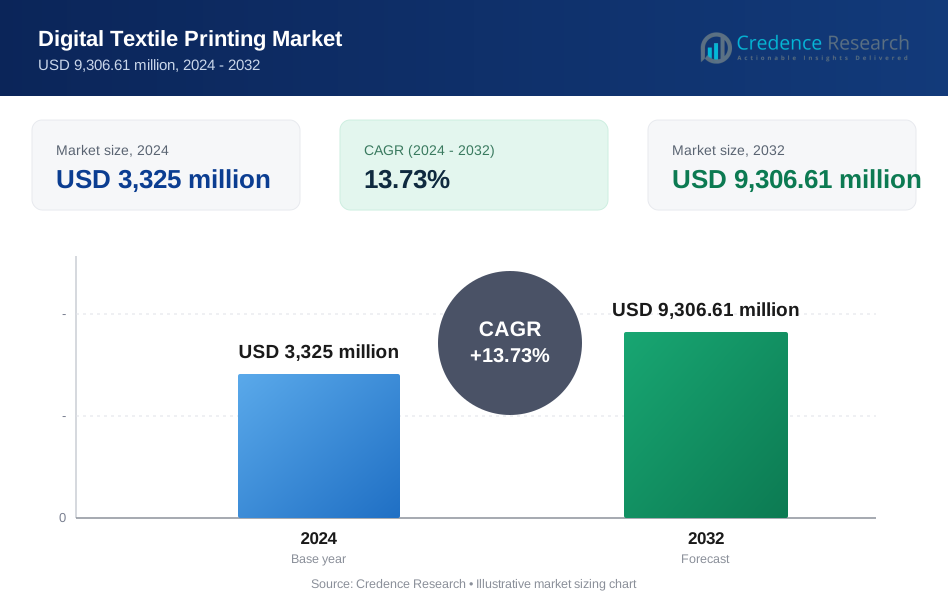
- 2.5.1 2024: USD 3,325 million → 2032: USD 9,306.61 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Digital Textile Printing Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Digital Textile Printing Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Digital Textile Printing Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Digital Textile Printing Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Digital Textile Printing Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Digital Textile Printing Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Digital Textile Printing Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Digital Textile Printing Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 3,325 million → 2032: USD 9,306.61 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Digital Textile Printing Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Process - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Direct to Fabric (Roll to Roll Printing)
- 12.3.7.2 Direct to Garment (DTG)
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Material - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Cotton
- 12.4.7.2 Silk
- 12.4.7.3 Polyester
- 12.4.7.4 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Operation - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Single Pass
- 12.5.7.2 Multi Pass
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Application - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Clothing/Apparel
- 12.6.7.2 Home Décor
- 12.6.7.3 Soft Signage
- 12.6.7.4 Industrial
- 12.6.7.5 Others
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Digital Textile Printing End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Digital Textile Printing Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Digital Textile Printing Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Digital Textile Printing Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Seiko Epson
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Mimaki Engineering
- 18.4 Kornit Digital
- 18.5 D.Gen
- 18.6 Roland DG Corporation
- 18.7 Dover Corporation
- 18.8 Konica Minolta
- 18.9 Brother Industries
- 18.10 Colorjet
- 18.11 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

