
Market overview
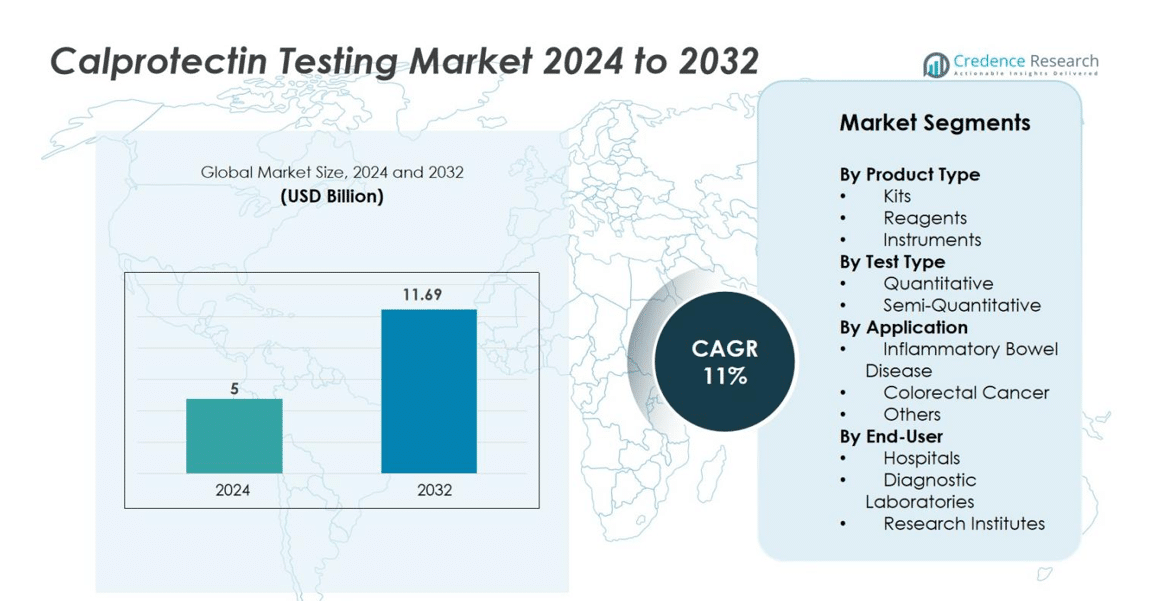
Calprotectin Testing market size was valued at USD 5 billion in 2024 and is anticipated to reach USD 11.69 billion by 2032, at a CAGR of 11% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Calprotectin Testing Market Size 2024 | USD 5 billion |
| Calprotectin Testing Market, CAGR | 11% |
| Calprotectin Testing Market Size 2032 | USD 11.69 billion |
The Calprotectin Testing market is driven by strong participation from major diagnostic companies, including Biohit Oyj, R-Biopharm AG, F. Hoffmann-La Roche Ltd, Siemens Healthineers AG, Danaher Corporation, DiaSorin S.p.A., Quidel Corporation, EKF Diagnostics Holdings plc, Alere Inc., and Bio-Rad Laboratories. These players compete through advancements in quantitative assays, automated analyzers, and high-sensitivity testing kits that support rapid and accurate gastrointestinal diagnostics. North America remains the leading region, holding 38 percent of the global market share in 2024, supported by advanced healthcare infrastructure, high IBD prevalence, and strong laboratory adoption of standardized calprotectin testing technologies.
Market Insights
- The Calprotectin Testing market was valued at USD 5 billion in 2024 and is projected to reach USD 11.69 billion by 2032, registering a CAGR of 11% during the forecast period.
- Market growth is driven by the rising prevalence of inflammatory bowel disease and increasing demand for non-invasive diagnostics, with kits accounting for the largest product share at 55 % due to ease of use and strong adoption in clinical laboratories.
- Key trends include the rapid shift toward quantitative testing, which dominated with 62 % share, along with expanding use of automated platforms and growing interest in home-based and point-of-care calprotectin testing.
- The competitive landscape features major players such as Biohit Oyj, R-Biopharm AG, Roche, Siemens Healthineers, Danaher, and DiaSorin, all focusing on advanced immunoassays, automated analyzers, and broader global distribution.
- Regionally, North America led with 38 percent of the market in 2024, followed by Europe at % while Asia-Pacific captured 20% and remains the fastest-growing region due to expanding diagnostic capabilities.
Market Segmentation Analysis
By Product Type
Kits dominated the Calprotectin Testing market in 2024, capturing an estimated 55% share, driven by their ease of use, standardized protocols, and suitability for high-throughput diagnostic workflows. Reagents and instruments followed, supported by rising adoption of automated analyzers in clinical laboratories. The strong demand for reliable, rapid stool-based biomarkers in gastrointestinal diagnostics continues to push hospitals and reference labs toward ready-to-use kits that reduce workflow variability. Growing emphasis on early detection of inflammatory and neoplastic conditions further strengthens the preference for kit-based testing.
- For instance, Epitope Diagnostics, Inc.’s KT-112 rapid test kit for fecal calprotectin includes 20 tests per kit and can detect calprotectin levels at or above 50 ng/g stool using a lateral flow format.
By Test Type
The Quantitative segment held the leading position with 62% market share in 2024, propelled by its superior accuracy, reproducibility, and ability to support clinical decision-making through precise calprotectin concentration measurement. Quantitative tests are increasingly preferred for monitoring disease activity in chronic conditions such as IBD, where clinicians rely on exact values to adjust therapy. Semi-quantitative tests remain relevant due to affordability and suitability for point-of-care settings, but rising demand for standardized, instrument-based diagnostics continues to reinforce the dominance of quantitative testing.
- For instance, Quantum Blue® fCAL High Range (LF-CHR25) from BÜHLMANN Laboratories AG provides a measurable range of 100-1,800 µg/g fecal calprotectin with results delivered in approximately 12 minutes.
By Application
Inflammatory Bowel Disease (IBD) was the top application area, accounting for 58% of the market in 2024, supported by the growing global prevalence of Crohn’s disease and ulcerative colitis. The need for non-invasive biomarkers that accurately assess mucosal inflammation and reduce reliance on colonoscopy drives widespread adoption of calprotectin testing in IBD management. Colorectal cancer screening and other gastrointestinal disorders form the remaining segments, benefiting from expanding clinical guidelines that recognize calprotectin as a valuable diagnostic and monitoring tool.
Key Growth Drivers
Rising Prevalence of Gastrointestinal Disorders
The rising incidence of gastrointestinal disorders, particularly IBD, is a major driver of calprotectin test demand. Growing cases of Crohn’s disease and ulcerative colitis push clinicians to adopt non-invasive tools for early diagnosis and disease monitoring. Calprotectin testing helps reduce reliance on colonoscopy by offering a reliable assessment of intestinal inflammation. Increasing patient awareness, expanding screening programs, and the growing elderly population further accelerate routine use of calprotectin tests across hospitals and diagnostic laboratories worldwide.
- For instance, a global systematic review reported a prevalence of IBD at approximately 229.7 cases per 100,000 persons (95 % CI: 212.4 to 247.0).
Shift Toward Non-Invasive Diagnostic Modalities
Healthcare systems increasingly prefer non-invasive diagnostic solutions that improve patient comfort and reduce procedural risks. Calprotectin testing aligns with this trend by providing a simple, stool-based test that avoids costly and invasive endoscopic procedures. Its ability to support frequent monitoring makes it valuable for managing chronic gastrointestinal conditions. Faster turnaround times, improved assay accuracy, and broader acceptance among clinicians further support adoption. As patient-centric care models expand, the demand for non-invasive calprotectin tests continues to rise.
- For instance, Calpro AS offers its CalproSmart home-test kit enabling patients to quantify fecal calprotectin themselves (for example sample volumes ~75 µL) and transmit data remotely for clinician review.
Technological Advancements in Diagnostic Platforms
Ongoing advancements in diagnostic technologies significantly strengthen the calprotectin testing landscape. Automated analyzers, improved immunoassay platforms, and digital data integration enhance accuracy, speed, and workflow efficiency. Instrument-based quantitative tests offer high reproducibility, supporting better clinical decisions. Emerging point-of-care devices also enable decentralized testing, expanding access in outpatient and remote settings. Manufacturers continue to develop robust, analyzer-compatible kits and reagents, improving scalability and ease of use. These technological improvements broaden clinical applications and boost market adoption.
Key Trends & Opportunities
Growing Adoption of Home-Based and Point-of-Care Testing
The shift toward decentralized diagnostics presents a major opportunity for calprotectin testing. Home-based and point-of-care solutions offer convenience, faster results, and better disease monitoring for chronic conditions like IBD. The rise of telehealth further supports tools that allow patients to test at home and share results digitally with clinicians. Manufacturers are introducing user-friendly devices with improved accuracy to meet this demand. This trend enhances patient engagement, reduces clinic visits, and supports earlier detection of inflammatory flare-ups.
- For instance, the device SmarTest Calprotectin Home Test (by Preventis GmbH) supports a measuring range of 31-4,000 µg/g and uploads each result to a clinician’s online portal for remote monitoring.
Expansion into Emerging Markets
Emerging economies offer significant growth potential as healthcare infrastructure improves and diagnostic capabilities expand. Rising awareness of gastrointestinal disorders and increasing adoption of advanced laboratory techniques support calprotectin test uptake in regions such as Asia-Pacific and Latin America. Government initiatives promoting screening programs and early diagnosis further accelerate demand. With low penetration levels compared to developed markets, these regions present strong opportunities for affordable and scalable testing solutions tailored to resource-limited environments.
- For instance, South Korea is experiencing a growing demand for calprotectin testing, a reliable noninvasive indicator for inflammatory bowel disease, with the market projected to grow significantly. The adoption of these tests is driven by increased awareness of early disease detection and the availability of advanced healthcare infrastructure.
Key Challenges
Variability in Test Results and Lack of Standardization
A key challenge in the calprotectin testing market is the variability of results across different platforms, kits, and laboratory protocols. Differences in assay sensitivity, sample preparation, and cut-off values can lead to inconsistent outcomes, complicating clinical interpretation. This lack of standardization reduces confidence among clinicians and may affect treatment decisions, especially for chronic disease monitoring. Advancing regulatory guidelines and harmonizing testing procedures are essential to improving result consistency and enhancing diagnostic reliability.
Limited Awareness and Accessibility in Low-Resource Settings
In many low-resource regions, calprotectin testing adoption remains limited due to insufficient healthcare infrastructure, low clinician awareness, and restricted access to advanced diagnostic equipment. Cost constraints, limited reimbursement coverage, and patient unfamiliarity with stool-based diagnostics further hinder market penetration. Many providers still depend on traditional, invasive diagnostic methods. Improving accessibility will require targeted education, cost-effective test options, and stronger distribution networks to support early diagnosis and improve outcomes in underserved populations.
Regional Analysis
North America
North America held the largest share of the Calprotectin Testing market in 2024, accounting for 38% of global revenue. Strong healthcare infrastructure, high awareness of gastrointestinal disorders, and widespread adoption of advanced diagnostic technologies support market leadership. The region’s high prevalence of IBD, particularly in the U.S. and Canada, drives consistent demand for non-invasive biomarkers such as calprotectin. Favorable reimbursement policies, increasing use of quantitative assays, and strong presence of major diagnostic companies further accelerate growth. Continued investment in research and broader integration of automated analyzers are expected to enhance expansion.
Europe
Europe represented the second-largest market, contributing 32% of global share in 2024. The region maintains strong clinical adoption of fecal calprotectin testing, supported by structured guidelines for early detection and IBD monitoring. Countries such as the U.K., Germany, and the Nordic nations use calprotectin as a triage tool to reduce unnecessary colonoscopies. Robust laboratory networks, increased utilization of point-of-care assays, and strong healthcare policies promote test penetration. Rising emphasis on colorectal cancer screening and continuous advancements in diagnostic automation further reinforce Europe’s strong market position.
Asia-Pacific
Asia-Pacific accounted for 20% of the global calprotectin testing market in 2024 and remains the fastest-growing region. Rapid healthcare infrastructure development, rising awareness of gastrointestinal disorders, and increased preference for non-invasive diagnostics are key growth factors. China, Japan, South Korea, and Australia are experiencing growing demand for quantitative assays due to increasing IBD incidence and expanding diagnostic capabilities. Government-led initiatives, laboratory modernization, and higher healthcare spending contribute to long-term market potential. The region’s large population base makes it a critical contributor to future global demand.
Latin America
Latin America captured 6% share of the Calprotectin Testing market in 2024, supported by growing diagnostic adoption in Brazil, Mexico, Argentina, and Chile. Rising awareness of gastrointestinal issues, expanding private healthcare infrastructure, and increasing acceptance of non-invasive stool tests are driving market growth. Although overall penetration remains below that of developed regions, improving laboratory capacity and broader clinician awareness support steady expansion. Partnerships with global diagnostic companies and strengthening public health initiatives are expected to enhance test accessibility over the coming years.
Middle East & Africa
The Middle East & Africa region accounted for 4% of global market share in 2024, with adoption largely concentrated in Gulf countries such as the UAE and Saudi Arabia. Expanding diagnostic laboratory networks, higher healthcare spending, and increasing recognition of gastrointestinal disorders support regional growth. However, limited awareness, budget constraints, and uneven access to advanced diagnostic tools restrict broader adoption in several African countries. Despite these limitations, ongoing healthcare reforms and rising investment in diagnostic modernization are expected to gradually improve calprotectin testing uptake.
Market Segmentations
By Product Type
- Kits
- Reagents
- Instruments
By Test Type
- Quantitative
- Semi-Quantitative
By Application
- Inflammatory Bowel Disease
- Colorectal Cancer
- Others
By End-User
- Hospitals
- Diagnostic Laboratories
- Research Institutes
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Calprotectin Testing market is characterized by the presence of several established diagnostic companies and emerging innovators focused on expanding non-invasive gastrointestinal diagnostics. Key players include Biohit Oyj, R-Biopharm AG, F. Hoffmann-La Roche Ltd, Siemens Healthineers AG, Danaher Corporation, DiaSorin S.p.A., Quidel Corporation, EKF Diagnostics Holdings plc, Alere Inc., and Bio-Rad Laboratories. These companies compete on assay accuracy, automation capabilities, product reliability, and global distribution strength. Many are investing in quantitative immunoassay platforms, automated analyzers, and point-of-care solutions to meet rising demand for rapid and standardized testing. Strategic partnerships, product launches, and clinical validation studies remain central to strengthening market presence. Additionally, manufacturers are expanding their portfolios with high-sensitivity kits and analyzer-compatible reagents to improve laboratory efficiency and clinical applicability. As gastrointestinal disease prevalence rises, competition is expected to intensify, driving continuous innovation and broader adoption across hospital, reference lab, and home-based testing environments.
Key Player Analysis
- Quidel Corporation
- Bio-Rad Laboratories
- DiaSorin S.p.A.
- Siemens Healthineers AG
- Biohit Oyj
- EKF Diagnostics Holdings plc
- Alere Inc.
- Danaher Corporation
- F. Hoffmann-La Roche Ltd
- R-Biopharm AG
Recent Developments
- In May 2025, ALPCO announced the European commercial launch of its Calprotectin Immunoturbidimetric assay.
- In June 2024, BÜHLMANN Laboratories AG released an enhanced version of their IBDoc Home Test App for calprotectin home-monitoring.
- In May 2024, Thermo Fisher Scientific Inc. launched a high-sensitivity fecal calprotectin ELISA test designed for monitoring disease activity and early detection of inflammation.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Test Type, Application, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will continue expanding as demand rises for non-invasive tools to diagnose and monitor gastrointestinal diseases.
- Adoption of quantitative calprotectin assays will strengthen due to their superior accuracy and clinical decision-making value.
- Growth in automated and high-throughput analyzers will enhance testing efficiency across hospital and reference laboratories.
- Point-of-care and home-based calprotectin testing will gain traction as remote patient monitoring becomes more common.
- Emerging markets will witness faster adoption as healthcare infrastructure and diagnostic awareness improve.
- Integration of digital reporting and connected platforms will streamline result sharing between patients and clinicians.
- Manufacturers will invest in improved assay standardization to reduce variability and support global clinical acceptance.
- Rising prevalence of IBD and colorectal disorders will continue driving routine testing demand worldwide.
- Strategic partnerships and product innovations will intensify competition among established diagnostic companies.
- Expanding clinical guidelines endorsing calprotectin will boost its role in early detection and disease management.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence of Gastrointestinal Disorders
The increasing incidence of inflammatory bowel disease (IBD), Crohn’s disease, and ulcerative colitis is driving demand for calprotectin testing as clinicians seek non-invasive, reliable biomarkers for early diagnosis and disease monitoring.
Shift Toward Non-Invasive Diagnostic Modalities
Healthcare providers and patients are increasingly favoring non-invasive stool-based tests like calprotectin over traditional endoscopic procedures, as they offer greater comfort, lower risk, and enable frequent disease monitoring.
Technological Advancements in Diagnostic Platforms
Ongoing improvements in automated analyzers, quantitative immunoassays, and digital data integration are enhancing test accuracy, speed, and workflow efficiency, making calprotectin testing more accessible and reliable for clinical use.
Expansion of Home-Based and Point-of-Care Testing
The development and adoption of home-based and point-of-care calprotectin tests are enabling remote patient monitoring and faster clinical decision-making, particularly for chronic disease management and telehealth applications.
Growing Diagnostic Infrastructure in Emerging Markets
Rising healthcare investment, government-led screening initiatives, and increasing awareness of gastrointestinal disorders in Asia-Pacific and Latin America are expanding the adoption of calprotectin testing in these high-growth regions.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Calprotectin Testing Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Calprotectin Testing Market projected to grow between 2025 and 2032?
Which segment is leading the market share in terms of Sample?
Which Indication segment governs the second largest market demand for Calprotectin testings in the world?
Which segment is expected to post the highest CAGR during the forecast period?
Which region is fueling the growth of the Calprotectin testing industry?
Who are the major players in the global Calprotectin testing market?
What are the major market drivers of the Calprotectin testing industry?
What are the major market restraints of the Calprotectin testing industry?
Who are the leading companies in the Calprotectin Testing Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-User
- 1.2.1 Hospitals
- 1.2.2 Diagnostic Laboratories
- 1.2.3 Research Institutes
- 1.3 By Test Type
- 1.3.1 Quantitative
- 1.3.2 Semi-Quantitative
- 1.4 By Application
- 1.4.1 Inflammatory Bowel Disease
- 1.4.2 Colorectal Cancer
- 1.4.3 Others
- 1.5 By Product Type
- 1.5.1 Kits
- 1.5.2 Reagents
- 1.5.3 Instruments
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 5 billion → 2032: USD 11.69 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Calprotectin Testing Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Calprotectin Testing Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Calprotectin Testing Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Calprotectin Testing Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Calprotectin Testing Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Calprotectin Testing Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Calprotectin Testing Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Calprotectin Testing Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 5 billion → 2032: USD 11.69 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Calprotectin Testing Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Hospitals
- 12.3.7.2 Diagnostic Laboratories
- 12.3.7.3 Research Institutes
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Test Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Quantitative
- 12.4.7.2 Semi-Quantitative
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Inflammatory Bowel Disease
- 12.5.7.2 Colorectal Cancer
- 12.5.7.3 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Product Type - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Kits
- 12.6.7.2 Reagents
- 12.6.7.3 Instruments
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Calprotectin Testing End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Calprotectin Testing Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Calprotectin Testing Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Calprotectin Testing Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Biohit Oyj
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 R-Biopharm AG
- 18.4 F. Hoffmann-La Roche Ltd
- 18.5 Siemens Healthineers AG
- 18.6 Danaher Corporation
- 18.7 DiaSorin S.p.A.
- 18.8 Quidel Corporation
- 18.9 EKF Diagnostics Holdings plc
- 18.10 Alere Inc.
- 18.11 Bio-Rad Laboratories
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

