
Market Overview
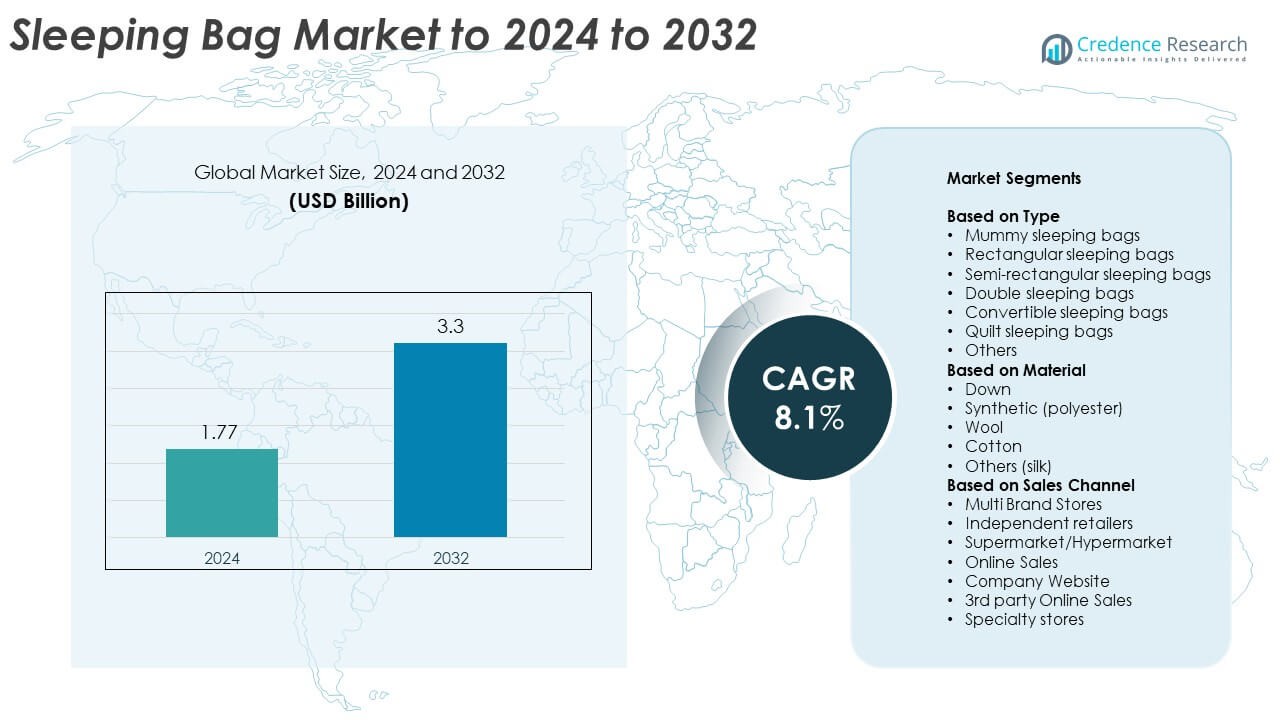
Sleeping Bag Market size was valued USD 1.77 billion in 2024 and is anticipated to reach USD 3.3 billion by 2032, at a CAGR of 8.1% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Sleeping Bag Market Size 2024 | USD 1.77 Billion |
| Sleeping Bag Market, CAGR | 8.1% |
| Sleeping Bag Market Size 2032 | USD 3.3 Billion |
The sleeping bag market is led by key players including Marmot, Western Mountaineering, REI Co-op, Big Agnes, NEMO Equipment, The North Face, Feathered Friends, Sea to Summit, Coleman, Sierra Designs, L.L.Bean, Mountain Hardwear, Rab, Therm-a-Rest, and Kelty. These brands hold strong positions through advanced insulation materials, product innovation, and diversified retail presence. North America dominated the global market in 2024 with a 36.8% share, driven by high outdoor recreation participation and established brand networks. Europe followed with 28.4% market share, supported by growing adventure tourism. Asia Pacific, with 22.7% share, emerged as the fastest-growing region, fueled by increasing camping and trekking activities.
Market Insights
- The sleeping bag market was valued at USD 1.77 billion in 2024 and is projected to reach USD 3.3 billion by 2032, growing at a CAGR of 8.1%.
- Rising participation in camping, trekking, and adventure tourism is driving strong demand for high-performance and lightweight sleeping bags.
- Increasing adoption of eco-friendly and recycled materials, along with smart temperature-regulating features, is shaping current market trends.
- The market remains highly competitive, with leading brands focusing on product innovation, sustainability, and e-commerce expansion to gain a wider consumer base.
- North America led the market with a 36.8% share in 2024, followed by Europe at 28.4% and Asia Pacific at 22.7%, while the mummy sleeping bag type dominated with a 37.2% share.
Market Segmentation Analysis:
By Type
The mummy sleeping bags segment dominated the market in 2024 with a 37.2% share. These bags offer superior thermal efficiency and body-hugging insulation, making them ideal for cold-weather camping. Their compact design and lightweight nature attract professional hikers and mountaineers. Rectangular and semi-rectangular bags follow due to their comfort and ease of movement, preferred by casual campers. Increasing demand for lightweight, compressible, and high-performance gear is driving the adoption of mummy sleeping bags across adventure tourism and outdoor recreational activities.
- For instance, Western Mountaineering lists the Kodiak MF mummy bag at 2 lb 12 oz (1.25 kg) and 0 °F / −18 °C rating, showing high warmth-to-weight design.
By Material
The synthetic (polyester) segment led the sleeping bag market with a 45.6% share in 2024. Synthetic sleeping bags are valued for their affordability, moisture resistance, and easy maintenance. These properties make them suitable for varied weather conditions and mass-market appeal. Down materials are also growing rapidly due to their premium insulation quality and comfort, particularly in extreme conditions. Expanding product innovations in recycled polyester fabrics are further promoting the segment’s dominance and sustainability appeal among eco-conscious consumers.
- For instance, Sea to Summit specifies ReviveLoft is 100% RCS-certified post-consumer recycled polyester insulation in its synthetic bags.
By Sales Channel
Online sales dominated the market in 2024 with a 34.9% share, driven by rising e-commerce penetration and brand-led digital campaigns. Consumers prefer online platforms for product variety, reviews, and price comparisons. Third-party online retailers and company websites offer discounts and customization options that enhance accessibility. Supermarkets and specialty stores continue to serve as key offline channels for consumers seeking in-person evaluation. The growth of omnichannel retail strategies and influencer-driven marketing continues to fuel online sales expansion globally.
Key Growth Drivers
Rising Outdoor Recreation and Camping Activities
The growing participation in outdoor recreation and adventure tourism is a primary driver for the sleeping bag market. Increasing consumer interest in hiking, trekking, and camping, especially among younger demographics, is boosting product demand. Governments and tourism agencies promoting eco-tourism and adventure destinations also support market expansion. The accessibility of organized camping sites and improved outdoor infrastructure further encourage consumers to invest in high-quality sleeping bags designed for comfort and temperature regulation.
- For instance, the Outdoor Industry reports 175.8 million U.S. participants in 2023 (57.3% of people aged six+), underpinning sleeping bag uptake.
Technological Advancements in Insulation Materials
Continuous innovation in lightweight, durable, and thermally efficient materials is fueling market growth. Manufacturers are adopting advanced insulation technologies using synthetic and down blends for enhanced warmth retention and moisture control. Improved compressibility and resistance to environmental conditions are also increasing product appeal among professional travelers. Developments in sustainable materials, including recycled polyester and eco-friendly coatings, are driving demand from environmentally conscious consumers and strengthening brand competitiveness.
- For instance, PrimaLoft Cross Core shows 11–52% more warmth at the same weight versus standard Gold Insulation.
Expansion of E-commerce and Omni-channel Distribution
The expansion of digital retail channels is significantly influencing market growth. Consumers are increasingly purchasing sleeping bags online due to convenience, product variety, and transparent reviews. Brands are adopting omnichannel strategies that integrate physical stores with digital platforms to improve accessibility and customer experience. Discounted pricing, fast delivery, and exclusive online launches by leading brands are attracting new consumers globally, further accelerating sales across the online distribution network.
Key Trends & Opportunities
Growing Demand for Sustainable and Recycled Materials
Sustainability has emerged as a major market trend as consumers prioritize eco-friendly products. Manufacturers are shifting to recycled polyester, organic cotton, and biodegradable fillings to meet environmental standards. This transition aligns with global sustainability goals and attracts eco-conscious buyers. Companies investing in green certifications and low-carbon manufacturing practices are gaining competitive advantages, opening opportunities for product differentiation and brand loyalty in developed and emerging markets.
- For instance, For the Fall 2025 season, Patagonia reports on its official website that 98% of all polyester-based fabrics by weight were made using recycled polyester fabric
Product Customization and Smart Features
Customization and integration of smart features are transforming the market landscape. Adjustable temperature zones, compact designs, and sensor-based comfort controls are enhancing user convenience. Some sleeping bags now include connectivity features for temperature monitoring and integrated power ports for outdoor electronics. These technological innovations not only improve usability but also target premium customer segments, offering strong potential for differentiation in the competitive outdoor equipment market.
- For instance, Coleman OneSource heated bags offer 4 heat settings with runtimes of 2 h (high), 2.5 h (medium), 4 h (low), and 3 h (pulse) per battery.
Key Challenges
High Price of Premium Materials
The cost of advanced materials such as down insulation and high-grade synthetics remains a major challenge. Price-sensitive consumers often opt for low-cost alternatives, limiting the adoption of premium sleeping bags. Fluctuations in raw material prices and production costs also affect profit margins. This poses challenges for manufacturers aiming to balance quality and affordability while maintaining competitiveness in both developed and emerging markets.
Seasonal Demand Fluctuations
Seasonal buying patterns impact the overall market stability. Sleeping bag sales peak during camping and holiday seasons but drop significantly in colder or off-tourism months. These fluctuations create challenges in managing inventory, supply chains, and pricing strategies. To mitigate this, manufacturers are diversifying product applications for indoor and travel use, but consistent year-round demand remains difficult to achieve in several regions.
Regional Analysis
North America
North America dominated the sleeping bag market in 2024 with a 36.8% share. The region’s strong outdoor culture, coupled with high participation in camping and adventure sports, drives consistent demand. The United States leads due to extensive national park networks and established outdoor brands offering innovative designs. Consumers increasingly favor lightweight, insulated, and eco-friendly products. Canada also contributes significantly, supported by cold-weather camping and hiking activities. The rising popularity of digital retail platforms and sustainability-focused product offerings further strengthen the region’s leadership in the global sleeping bag market.
Europe
Europe accounted for a 28.4% share of the sleeping bag market in 2024, driven by a growing interest in recreational camping and nature-based tourism. Countries such as Germany, France, and the United Kingdom are key contributors due to their strong outdoor sports culture and increasing adventure tourism activities. Demand for lightweight and high-insulation sleeping bags suitable for diverse climates continues to grow. The expansion of eco-certified and recycled material products aligns with the region’s stringent environmental standards, while well-established retail networks further support market growth.
Asia Pacific
Asia Pacific held a 22.7% share of the sleeping bag market in 2024, emerging as the fastest-growing region. The increasing popularity of trekking, mountaineering, and camping across China, Japan, India, and Australia drives demand. Rising disposable incomes and lifestyle shifts toward outdoor leisure activities further support expansion. Manufacturers are targeting regional preferences by offering compact, affordable, and climate-appropriate products. The growth of e-commerce platforms and brand collaborations with travel communities are accelerating adoption, positioning Asia Pacific as a key growth hub in the global sleeping bag industry.
Latin America
Latin America captured an 8.1% share of the sleeping bag market in 2024. Growth is supported by rising adventure tourism and expanding participation in outdoor recreation across Brazil, Chile, and Argentina. The increasing promotion of camping and eco-tourism activities by regional governments also fuels product demand. Consumers favor durable, breathable, and affordable sleeping bags suited to varied climates. Local and international brands are focusing on online retail expansion and regional partnerships to enhance distribution, contributing to steady growth across emerging outdoor recreation markets.
Middle East & Africa
The Middle East and Africa region accounted for a 4% share of the sleeping bag market in 2024. Growth is driven by increasing camping tourism, desert expeditions, and mountaineering activities in countries such as the UAE, South Africa, and Kenya. Rising disposable incomes and improving adventure tourism infrastructure are creating new opportunities for global brands. Consumers seek durable, lightweight, and temperature-adaptable sleeping bags. Although market penetration remains moderate, increasing awareness of outdoor leisure and growing retail availability are gradually strengthening regional demand.
Market Segmentations:
By Type
- Mummy sleeping bags
- Rectangular sleeping bags
- Semi-rectangular sleeping bags
- Double sleeping bags
- Convertible sleeping bags
- Quilt sleeping bags
- Others
By Material
- Down
- Synthetic (polyester)
- Wool
- Cotton
- Others (silk)
By Sales Channel
- Multi Brand Stores
- Independent retailers
- Supermarket/Hypermarket
- Online Sales
- Company Website
- 3rd party Online Sales
- Specialty stores
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The sleeping bag market features strong competition among leading players such as Marmot, Western Mountaineering, REI Co-op, Big Agnes, NEMO Equipment, The North Face, Feathered Friends, Sea to Summit, Coleman, Sierra Designs, L.L.Bean, Mountain Hardwear, Rab, Therm-a-Rest, and Kelty. These companies compete through product innovation, material advancements, and performance-oriented designs targeting diverse camping and trekking needs. Manufacturers emphasize lightweight, weather-resistant, and thermally efficient sleeping bags that meet both recreational and professional user requirements. Increasing focus on eco-friendly fabrics, sustainable insulation, and recyclable components is shaping product development strategies. Companies are also expanding their global reach through online channels, direct-to-consumer platforms, and strategic partnerships with outdoor retailers. The growing adoption of premium and customizable sleeping bags for extreme weather conditions further intensifies market competition, pushing brands to differentiate through innovation, comfort, and durability while maintaining affordability across key consumer segments worldwide.
Key Player Analysis
- Marmot
- Western Mountaineering
- REI Co-op
- Big Agnes
- NEMO Equipment
- The North Face
- Feathered Friends
- Sea to Summit
- Coleman
- Sierra Designs
- L.Bean
- Mountain Hardwear
- Rab
- Therm-a-Rest
- Kelty
Recent Developments
- In 2025, Big Agnes showcased new backpacking sleeping bags with PFAS-free water resistance, focusing on warmth and packability for modern adventure.
- In 2024, Sierra Designs continued to emphasize its existing innovative and award-winning sleeping bag lines, such as the Cloud and Nitro series, which feature designs focused on comfort and functionality.
- In 2023, NEMO updated its popular Disco and Riff down sleeping bags to be part of its Endless Promise Collection, a sustainability initiative ensuring the bags are designed for full recyclability at the end of their lives
Report Coverage
The research report offers an in-depth analysis based on Type, Material, Sales Channel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The sleeping bag market will expand steadily, driven by rising outdoor and adventure activities.
- Demand for lightweight, compact, and high-insulation products will continue to grow.
- Manufacturers will focus more on sustainable and recycled material innovations.
- Online sales channels will become the primary mode of product distribution worldwide.
- Asia Pacific will witness the fastest growth due to increasing camping participation.
- Technological advancements in insulation and moisture resistance will enhance product appeal.
- Customizable and multifunctional sleeping bags will attract premium consumers.
- Partnerships with tourism and outdoor gear brands will boost global visibility.
- Rising consumer awareness of eco-friendly travel products will shape purchasing trends.
- Continuous product innovation and ergonomic design improvements will strengthen market competitiveness.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Outdoor Recreation and Camping Activities
Increasing participation in camping, trekking, and adventure tourism - especially among younger demographics - is fueling demand for sleeping bags. Government and tourism agency promotion of eco-tourism and improved outdoor infrastructure further support market expansion.
Technological Advancements in Insulation Materials
Continuous innovation in lightweight, durable, and thermally efficient materials, including advanced synthetic and down blends, is enhancing product performance. These advancements improve warmth retention, moisture control, and compressibility, attracting both recreational and professional users.
Expansion of E-commerce and Omni-channel Distribution
The growth of digital retail channels and omnichannel strategies is making sleeping bags more accessible to consumers worldwide. Online platforms offer greater product variety, transparent reviews, and competitive pricing, driving higher sales and market penetration.
Growing Demand for Sustainable and Recycled Materials
Consumers are increasingly prioritizing eco-friendly products, prompting manufacturers to use recycled polyester, organic cotton, and biodegradable fillings. This shift aligns with global sustainability goals and attracts environmentally conscious buyers, creating new opportunities for differentiation.
Product Customization and Smart Features
The integration of adjustable temperature zones, compact designs, and smart features such as sensor-based comfort controls and connectivity is enhancing user convenience. These innovations appeal to premium segments and help brands stand out in a competitive market.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Sleeping Bag Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Sleeping Bag Market projected to grow between 2025 and 2032?
Which Sleeping Bag Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Sleeping Bag Market?
Who are the leading companies in the Sleeping Bag Market?
Which region commanded the largest share of the Sleeping Bag Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Mummy sleeping bags
- 1.2.2 Rectangular sleeping bags
- 1.2.3 Semi-rectangular sleeping bags
- 1.2.4 Double sleeping bags
- 1.2.5 Convertible sleeping bags
- 1.2.6 Quilt sleeping bags
- 1.2.7 Others
- 1.3 By Material
- 1.3.1 Down
- 1.3.2 Synthetic (polyester)
- 1.3.3 Wool
- 1.3.4 Cotton
- 1.3.5 Others (silk)
- 1.4 By Sales Channel
- 1.4.1 Multi Brand Stores
- 1.4.2 Independent retailers
- 1.4.3 Supermarket/Hypermarket
- 1.4.4 Online Sales
- 1.4.5 Company Website
- 1.4.6 3rd party Online Sales
- 1.4.7 Specialty stores
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1.77 billion → 2032: USD 3.3 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Sleeping Bags Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Sleeping Bags Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Sleeping Bags Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Sleeping Bags Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Sleeping Bags Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Sleeping Bags Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Sleeping Bags Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Sleeping Bags Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1.77 billion → 2032: USD 3.3 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Sleeping Bags Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Mummy sleeping bags
- 12.3.7.2 Rectangular sleeping bags
- 12.3.7.3 Semi-rectangular sleeping bags
- 12.3.7.4 Double sleeping bags
- 12.3.7.5 Convertible sleeping bags
- 12.3.7.6 Quilt sleeping bags
- 12.3.7.7 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Material - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Down
- 12.4.7.2 Synthetic (polyester)
- 12.4.7.3 Wool
- 12.4.7.4 Cotton
- 12.4.7.5 Others (silk)
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Sales Channel - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Multi Brand Stores
- 12.5.7.2 Independent retailers
- 12.5.7.3 Supermarket/Hypermarket
- 12.5.7.4 Online Sales
- 12.5.7.5 Company Website
- 12.5.7.6 3rd party Online Sales
- 12.5.7.7 Specialty stores
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Sleeping Bags Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Sleeping Bags Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Sleeping Bags Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Marmot
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Western Mountaineering
- 17.4 REI Co-op
- 17.5 Big Agnes
- 17.6 NEMO Equipment
- 17.7 The North Face
- 17.8 Feathered Friends
- 17.9 Sea to Summit
- 17.10 Coleman
- 17.11 Sierra Designs
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

