
Market Overview
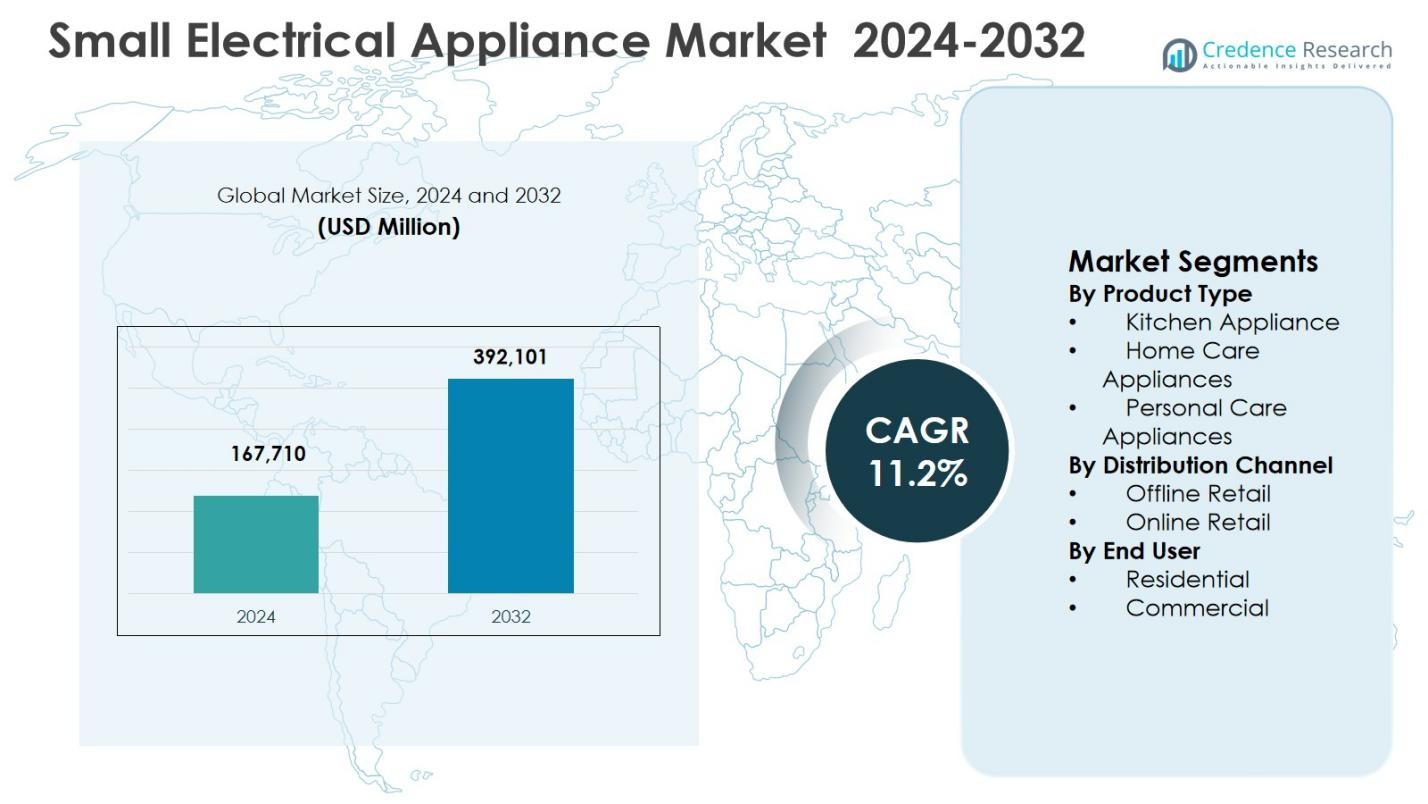
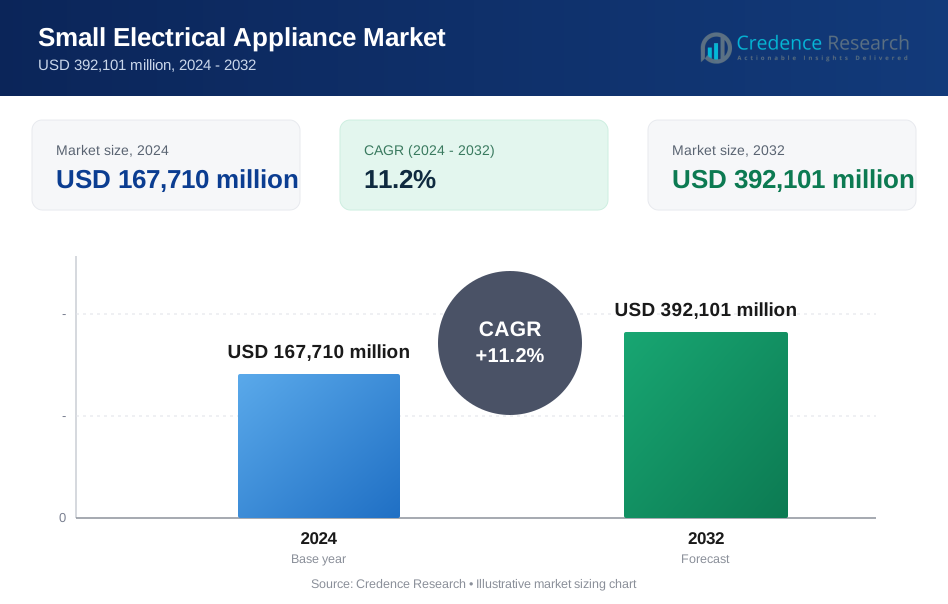
The Small Electrical Appliance Market size was valued at USD 167,710 million in 2024 and is anticipated to reach USD 392,101 million by 2032, growing at a CAGR of 11.2% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Small Electrical Appliance Market Size 2024 | USD 167,710 Million |
| Small Electrical Appliance Market, CAGR | 11.2% |
| Small Electrical Appliance Market Size 2032 | USD 392,101 Million |
The Small Electrical Appliance Market is led by key players such as Whirlpool Corporation, LG Electronics Inc., Samsung Electronics Co., Panasonic Holdings Corporation, Koninklijke Philips N.V., BSH Hausgeräte GmbH, Electrolux AB, Haier Group Corporation, SEB Group, and Breville Group Ltd. These companies drive growth through continuous product innovation, technological advancements, and expansion of distribution networks across both offline and online channels. North America emerges as the leading region with 31.5% market share in 2024, followed by Europe at 28.4% and Asia-Pacific at 25.7%, reflecting strong demand for kitchen, personal care, and home care appliances. Manufacturers focus on smart, energy-efficient, and multifunctional devices to cater to urban lifestyles, rising disposable incomes, and growing awareness of convenience and hygiene. Regional expansions, product launches, and after-sales services further enhance brand presence and adoption across residential and commercial segments worldwide.
Market Insights
- The Small Electrical Appliance Market was valued at USD 167,710 million in 2024 and is projected to reach USD 392,101 million by 2032, growing at a CAGR of 11.2%. Kitchen Appliances led the product type segment with 42.8% market share in 2024.
- Rising urbanization, increasing disposable incomes, and demand for time-saving, multifunctional appliances are driving growth across residential and commercial segments globally. Smart and energy-efficient appliances further support adoption.
- The market is witnessing trends such as IoT-enabled and app-controlled devices, eco-friendly and low-power consumption products, and growth of online retail platforms enhancing accessibility and product visibility.
- Leading players like Whirlpool Corporation, LG Electronics, Samsung Electronics, Panasonic Holdings, and Koninklijke Philips are driving innovation, expanding distribution networks, and focusing on after-sales services to strengthen market position.
- Regionally, North America leads with 31.5% share in 2024, Europe holds 28.4%, Asia-Pacific 25.7%, Latin America 8.6%, and Middle East & Africa 5.8%, reflecting strong demand across both developed and emerging markets.
Market Segmentation Analysis:
By Product Type:
The Small Electrical Appliance Market by product type is dominated by Kitchen Appliances, which accounted for 42.8% market share in 2024. Strong demand for coffee makers, blenders, mixers, and toasters supports this leadership, driven by rising home cooking trends, busy urban lifestyles, and growing adoption of convenient, time-saving appliances. Increasing penetration of smart kitchen devices, energy-efficient designs, and compact multifunctional products further strengthens demand. Continuous product innovation focused on performance, durability, and aesthetics also encourages frequent replacement cycles, reinforcing the dominance of kitchen appliances within the overall Small Electrical Appliance Market.
- For instance, KitchenAid's bowl-lift stand mixers feature 11 speeds including a half-speed for folding, with up to 7-quart capacity for dense doughs, offering 2x the bowl power of tilt-head models.
By Distribution Channel:
In the Small Electrical Appliance Market, Offline Retail emerged as the dominant distribution channel, capturing 58.6% market share in 2024. Specialty stores, supermarkets, and hypermarkets benefit from strong consumer preference for physical product evaluation, brand comparison, and immediate availability. In-store demonstrations, promotional discounts, and bundled offers further enhance purchasing decisions. Offline channels also maintain strong after-sales service networks, which remain critical for appliances requiring maintenance or warranty support. These advantages continue to sustain higher sales volumes through brick-and-mortar retail despite the growing presence of digital commerce platforms.
- For instance, Dyson operates demo stores where customers receive hands-on styling sessions with the Supersonic hair dryer, allowing hair analysis and real-time demonstrations of features like reduced heat damage, which drives conversions through direct product trials.
By End User:
The Residential segment led the Small Electrical Appliance Market by end user, holding 71.3% market share in 2024. High ownership rates of kitchen, personal care, and home care appliances across urban and semi-urban households drive this dominance. Rising disposable incomes, increasing focus on convenience, and growing awareness of hygiene and personal grooming contribute to sustained residential demand. Additionally, expanding nuclear families and higher adoption of smart and energy-efficient appliances support frequent upgrades. These factors collectively strengthen the residential segment’s position over commercial applications such as hotels, cafés, and offices.
Key Growth Drivers
Rising Urbanization and Changing Lifestyles
Rapid urbanization and busier lifestyles are driving demand for small electrical appliances, particularly in kitchens and personal care. Consumers increasingly prefer time-saving, convenient, and multifunctional devices such as blenders, coffee makers, and hair dryers. Growing nuclear households and dual-income families fuel the need for appliances that enhance efficiency and reduce manual effort. Additionally, awareness of energy-efficient and compact products supports adoption in apartments and urban homes, sustaining continuous growth across residential segments in the Small Electrical Appliance Market.
- For instance, Breville's BOV900BSS Smart Oven Air uses Element IQ technology with six quartz elements for precise cooking, accommodating a 14-pound turkey in its 21.4″ x 17.2″ x 12.8″ footprint, perfect for urban homes needing multifunctional baking and air frying without heating the entire kitchen.
Technological Advancements and Smart Appliances
Integration of smart technologies in small electrical appliances significantly drives market growth. IoT-enabled devices, app-controlled kitchen appliances, and automated personal care tools improve usability, convenience, and energy efficiency. Features such as remote monitoring, programmable functions, and safety enhancements attract tech-savvy consumers seeking modern, connected lifestyles. Continuous innovation by manufacturers, including AI-based smart cooking devices and self-cleaning appliances, strengthens product differentiation and encourages repeat purchases, positioning technology as a key growth engine for the Small Electrical Appliance Market.
- For instance, Philips HomeID app connects to Wi-Fi-enabled Airfryers, allowing remote control of temperature and cooking duration from smartphones, along with recipe sending directly to the appliance.
Rising Disposable Incomes and Consumer Spending
Increasing disposable incomes across emerging and developed economies are driving higher adoption of small electrical appliances. Consumers are willing to invest in premium, durable, and energy-efficient products that enhance lifestyle quality. Spending on personal care, home care, and kitchen convenience products grows in tandem with awareness of health, hygiene, and comfort. This trend, combined with urbanization and lifestyle shifts, encourages households to upgrade existing appliances, fueling sales growth. Manufacturers benefit from this demand through diversified portfolios catering to mid- and high-income consumer segments.
Key Trends & Opportunities
Shift Towards Online Retail and E-Commerce Expansion
The growing penetration of online retail platforms presents significant opportunities for the Small Electrical Appliance Market. E-commerce enables manufacturers to reach wider audiences, offer competitive pricing, and provide product customization. Consumers increasingly prefer online purchases due to convenience, detailed product information, and doorstep delivery. Digital marketing campaigns, brand-owned websites, and online-exclusive product launches enhance visibility. This trend allows brands to tap into emerging markets and expand regional reach, complementing offline retail while creating growth potential for new product categories and innovative appliance models.
- For instance, Dyson launched an interactive virtual store on its website, featuring three-dimensional product views and explosive technology displays for small appliances like air purifiers and hair stylers.
Sustainability and Energy-Efficient Products
Sustainability is emerging as a critical trend and opportunity in the Small Electrical Appliance Market. Consumers increasingly favor energy-efficient, recyclable, and environmentally friendly appliances. Manufacturers are responding with low-power consumption devices, eco-certified products, and compact designs that reduce material usage. Government initiatives promoting energy-saving appliances and consumer awareness about environmental impact further drive adoption. This trend encourages innovation in product design, materials, and manufacturing processes, providing a growth pathway while aligning with global sustainability objectives and enhancing brand reputation.
- For instance, Bosch dishwashers feature PerfectDry with Zeolith technology, which activates natural minerals to dry loads perfectly using minimal energy.
Key Challenges
High Product Costs and Price Sensitivity
High upfront costs of premium small electrical appliances can limit adoption, particularly in price-sensitive emerging markets. Consumers often prioritize affordability over advanced features, slowing the penetration of smart and energy-efficient products. Frequent competition from low-cost local brands further intensifies pricing pressure. Manufacturers must balance innovation and cost-effectiveness, invest in localized production, and offer financing or bundled solutions to overcome resistance. Price sensitivity remains a critical challenge in achieving widespread market penetration without compromising profit margins or brand positioning.
Regulatory Compliance and Safety Standards
Stringent safety regulations, energy efficiency standards, and certification requirements pose challenges for manufacturers in the Small Electrical Appliance Market. Variations in regional compliance norms necessitate product adaptations, increasing production complexity and costs. Non-compliance risks penalties, recalls, or reputational damage. Additionally, evolving regulations on electrical safety, materials, and environmental impact require continuous monitoring and adjustment. Ensuring adherence to international and local standards remains essential to maintain market credibility, consumer trust, and seamless distribution across multiple geographies.
Regional Analysis
North America
The North America Small Electrical Appliance Market is led by the United States, capturing 31.5% market share in 2024. Strong consumer demand for kitchen, home care, and personal care appliances drives growth, supported by high disposable incomes, urban lifestyles, and increasing smart home adoption. The presence of established brands, extensive retail networks, and e-commerce penetration enhances product accessibility. Continuous product innovation, particularly in energy-efficient and IoT-enabled appliances, fuels replacement cycles. Rising health awareness and convenience-focused consumption further stimulate adoption across residential and commercial segments, positioning North America as a significant contributor to global Small Electrical Appliance Market growth.
Europe
Europe holds a 28.4% market share in 2024 in the Small Electrical Appliance Market, driven by strong demand in Germany, France, and the UK. Consumers prioritize energy-efficient, smart, and aesthetically designed kitchen, home care, and personal care appliances. Government incentives promoting eco-friendly and low-power consumption appliances encourage adoption. Mature retail infrastructure, including specialty stores and supermarkets, along with growing e-commerce platforms, supports extensive distribution. Lifestyle trends emphasizing convenience, health, and hygiene accelerate replacement and upgrade cycles. Continuous technological innovation by key players in smart and connected devices further strengthens Europe’s leadership in the Small Electrical Appliance Market.
Asia-Pacific
The Asia-Pacific Small Electrical Appliance Market captured 25.7% market share in 2024, with China, Japan, and India driving growth. Rising urbanization, expanding middle-class populations, and increasing disposable incomes fuel demand for kitchen, home care, and personal care appliances. E-commerce platforms and growing offline retail networks enhance product accessibility. Rapid adoption of smart, compact, and energy-efficient devices is driven by busy lifestyles and limited urban living spaces. Government initiatives promoting electrification and appliance penetration, coupled with increasing brand awareness, support sustained growth. Asia-Pacific represents a high-growth region for Small Electrical Appliance Market players targeting both residential and commercial consumers.
Latin America
Latin America accounts for 8.6% market share in 2024 in the Small Electrical Appliance Market, with Brazil and Mexico leading demand. Rising disposable incomes, urbanization, and growing interest in convenience appliances drive adoption across residential households. Offline retail channels remain dominant, complemented by increasing online retail penetration in urban centers. Demand for affordable, durable, and energy-efficient kitchen, home care, and personal care appliances supports market expansion. Government policies promoting household electrification and safety standards encourage adoption. Regional players and global brands leverage distribution networks to tap into both premium and value segments, positioning Latin America as an emerging growth market.
Middle East & Africa
The Middle East & Africa Small Electrical Appliance Market held 5.8% market share in 2024, led by the UAE, Saudi Arabia, and South Africa. Rising urbanization, increasing disposable incomes, and modernization of households drive demand for kitchen, personal care, and home care appliances. Strong retail infrastructure, including specialty stores and e-commerce platforms, enhances market reach. Growing preference for premium, energy-efficient, and smart appliances among urban consumers supports market growth. Regional investments in residential and commercial construction, along with rising lifestyle-oriented consumption, create opportunities for manufacturers. Market players focus on product customization, after-sales service, and regional partnerships to expand their presence.
Market Segmentations:
By Product Type
- Kitchen Appliance
- Home Care Appliances
- Personal Care Appliances
By Distribution Channel
- Offline Retail
- Online Retail
By End User
- Residential
- Commercial
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Competitive landscape in the Small Electrical Appliance Market features key players such as Whirlpool Corporation, LG Electronics Inc., Samsung Electronics Co., Panasonic Holdings Corporation, Koninklijke Philips N.V., BSH Hausgeräte GmbH, Electrolux AB, Haier Group Corporation, SEB Group, and Breville Group Ltd. The market is characterized by intense competition driven by continuous product innovation, technological advancements, and expanding distribution networks. Leading players focus on launching smart, energy-efficient, and multifunctional appliances to cater to evolving consumer preferences. Strategic initiatives, including mergers, acquisitions, partnerships, and regional expansions, enhance market presence and brand visibility. Companies also emphasize marketing campaigns, after-sales services, and customization to strengthen customer loyalty. The competition is further intensified by regional and local players offering affordable alternatives, compelling global brands to differentiate through quality, design, and technological superiority. Innovation in IoT-enabled and compact appliances continues to be a key driver shaping market dynamics.
Key Player Analysis
- Whirlpool Corporation
- LG Electronics Inc.
- Samsung Electronics Co., Ltd.
- Panasonic Holdings Corporation
- Koninklijke Philips N.V.
- BSH Hausgeräte GmbH
- Electrolux AB
- Haier Group Corporation
- SEB Group
- Breville Group Ltd
Recent Developments
- In July 2025, Reliance Retail acquired the iconic home appliance brand Kelvinator, strengthening its portfolio in consumer durables and expanding its presence in the small electrical appliance segment in India.
- In December 2025, LG Electronics continued its innovation trajectory by introducing a new range of AI‑powered washing machines in India, enhancing household convenience through intelligent fabric detection and energy‑efficient performance.
- In September 2025, Dyson unveiled 11 new and upgraded small electrical appliances, including the PencilVac™ the world's slimmest vacuum cleaner at 38mm diameter and the V16 Piston Animal cordless vacuum with AI-driven cleaning.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Distribution Channel, End User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market is expected to witness sustained growth driven by rising urbanization and busy lifestyles.
- Increasing adoption of smart and IoT-enabled appliances will shape future product demand.
- Energy-efficient and eco-friendly appliances will gain prominence due to environmental awareness.
- E-commerce expansion will enhance accessibility and accelerate regional market penetration.
- Continuous innovation in multifunctional and compact appliances will drive replacement cycles.
- Rising disposable incomes in emerging economies will boost consumer spending on premium appliances.
- Expansion of after-sales services will strengthen customer loyalty and repeat purchases.
- Growth in residential and commercial construction will support appliance adoption across sectors.
- Partnerships and collaborations among global and regional players will drive market consolidation.
- Increasing focus on health, hygiene, and convenience will create new opportunities for product development.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Urbanization and Changing Lifestyles
Rapid urbanization and increasingly busy lifestyles are fueling demand for small electrical appliances that offer convenience, time savings, and multifunctionality, especially in kitchens and personal care. The growth of nuclear families and dual-income households further accelerates adoption as consumers seek to enhance efficiency and reduce manual effort.
Technological Advancements and Smart Appliances
The integration of IoT, app control, and automation in small electrical appliances is driving market growth by improving usability, energy efficiency, and safety. Smart features such as remote monitoring and programmable functions attract tech-savvy consumers and encourage frequent upgrades.
Increasing Disposable Incomes and Consumer Spending
Rising disposable incomes in both developed and emerging economies are enabling consumers to invest in premium, durable, and energy-efficient appliances. This trend is supported by growing awareness of health, hygiene, and comfort, leading to higher spending on personal care, home care, and kitchen convenience products.
Expansion of E-Commerce and Online Retail
The proliferation of online retail platforms is making small electrical appliances more accessible, offering consumers convenience, competitive pricing, and a wider product selection. E-commerce also enables brands to reach new markets and launch online-exclusive products, accelerating market penetration.
Focus on Sustainability and Energy Efficiency
Growing consumer preference for eco-friendly, low-power consumption, and recyclable appliances is prompting manufacturers to innovate in product design and materials. Government incentives and regulations promoting energy-saving appliances further drive adoption, aligning with global sustainability goals.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Small Electrical Appliance Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Small Electrical Appliance Market projected to grow between 2024 and 2032?
Which Small Electrical Appliance Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Small Electrical Appliance Market?
Who are the leading companies in the Small Electrical Appliance Market?
Which region commanded the largest share of the Small Electrical Appliance Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Residential
- 1.2.2 Commercial
- 1.3 By Product Type
- 1.3.1 Kitchen Appliance
- 1.3.2 Home Care Appliances
- 1.3.3 Personal Care Appliances
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 167,710 million → 2032: USD 392,101 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Small Electrical Appliance Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Small Electrical Appliance Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Small Electrical Appliance Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Small Electrical Appliance Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Small Electrical Appliance Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Small Electrical Appliance Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Small Electrical Appliance Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Small Electrical Appliance Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 167,710 million → 2032: USD 392,101 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Small Electrical Appliance Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Residential
- 12.3.7.2 Commercial
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Kitchen Appliance
- 12.4.7.2 Home Care Appliances
- 12.4.7.3 Personal Care Appliances
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Small Electrical Appliance End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Small Electrical Appliance Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Small Electrical Appliance Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Small Electrical Appliance Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Whirlpool Corporation
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 LG Electronics Inc.
- 18.4 Samsung Electronics Co., Ltd.
- 18.5 Panasonic Holdings Corporation
- 18.6 Koninklijke Philips N.V.
- 18.7 BSH Hausgeräte GmbH
- 18.8 Electrolux AB
- 18.9 Haier Group Corporation
- 18.10 SEB Group
- 18.11 Breville Group Ltd
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

