
Market Overview
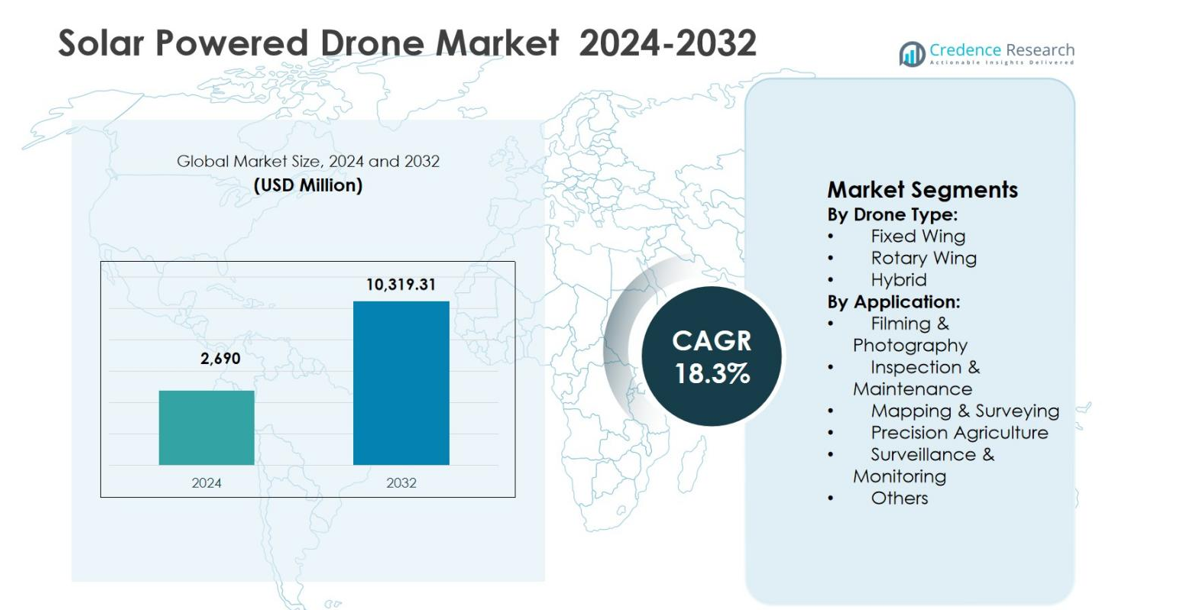
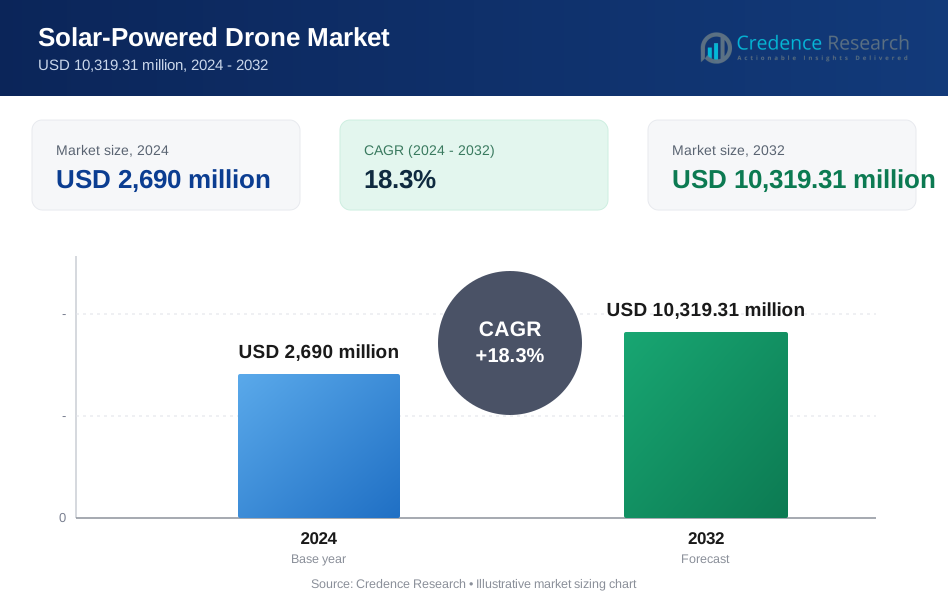
The Solar Powered Drone Market size was valued at USD 2,690 million in 2024 and is anticipated to reach USD 10,319.31 million by 2032, growing at a CAGR of 18.3% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Solar Powered Drone Market Size 2024 | USD 2,690 million |
| Solar Powered Drone Market, CAGR | 18.3% |
| Solar Powered Drone Market Size 2032 | USD 10,319.31 million |
The Solar Powered Drone Market is shaped by the presence of established aerospace firms and specialized UAV developers focusing on long-endurance, energy-efficient aerial platforms. Key players such as Airbus Defence and Space, Aurora Flight Sciences, AeroVironment, Kea Aerospace, Silent Falcon UAS Technologies, AtlantikSolar, XSun, DJI, and Parrot Drones are advancing solar-integrated drone designs for surveillance, mapping, and communications applications. These companies emphasize lightweight airframes, high-efficiency solar cells, and autonomous flight capabilities to enhance mission duration and reliability. Regionally, North America led the Solar Powered Drone Market with a 38% market share in 2024, driven by strong defense spending, advanced UAV research, and early adoption of long-endurance platforms, followed by Asia-Pacific and Europe with growing commercial and governmental deployments.
Market Insights
- Solar Powered Drone Market was valued at USD 2,690 million in 2024 and is projected to reach USD 10,319.31 million by 2032, growing at a CAGR of 18.3% during the forecast period, driven by rising adoption of long-endurance unmanned aerial platforms.
- Market growth is driven by increasing demand for persistent aerial surveillance, environmental monitoring, and infrastructure inspection, with fixed wing drones dominating the market by holding a 52.6% share in 2024 due to superior endurance and payload efficiency.
- Key market trends include integration of high-efficiency solar cells, lightweight composite materials, and AI-enabled autonomous navigation, while leading players focus on extending flight duration and enhancing data collection capabilities across defense and commercial applications.
- Market expansion faces restraints from high initial development costs, complex certification processes, and performance limitations under low-sunlight conditions, which impact adoption among small-scale commercial users.
- Regionally, North America led the market with a 38% share in 2024, followed by Asia-Pacific at 28% and Europe at 22%, while Surveillance & Monitoring remained the leading application segment with a 34.8% market share.
Market Segmentation Analysis:
By Drone Type:
The Solar Powered Drone Market, by drone type, is led by the Fixed Wing segment, which accounted for 52.6% market share in 2024, driven by its superior endurance, higher payload efficiency, and ability to operate over long distances using continuous solar energy harvesting. Fixed-wing solar drones are widely deployed for high-altitude, long-endurance missions such as border surveillance, atmospheric research, and large-area mapping. The Hybrid segment follows, holding 29.1% share, supported by rising demand for vertical takeoff combined with extended flight time. Rotary Wing drones captured 18.3% share, mainly used for short-range, precision tasks.
- For instance, Airbus's Zephyr S, a fixed-wing high-altitude pseudo-satellite (HAPS), completed a maiden flight of over 25 days in Arizona, reaching daytime altitudes around 74,000 feet powered by solar panels on its 25-meter wingspan.
By Application:
By application, Surveillance & Monitoring dominated the Solar Powered Drone Market with a 34.8% market share in 2024, supported by growing defense, homeland security, and environmental monitoring requirements. Solar-powered drones enable persistent aerial surveillance with reduced operational costs and minimal refueling needs. Mapping & Surveying held 21.6% share, driven by adoption in infrastructure planning, mining, and land management. Inspection & Maintenance accounted for 17.9% share, benefiting from utility and telecom inspections. Precision Agriculture captured 14.2% share, while Filming & Photography and Others jointly represented 11.5% share, supported by niche commercial uses.
- For instance, Sunbirds' SB4 Phoenix supports large-scale surveillance missions, flying up to seven hours on solar power for real-time monitoring in sunny regions.
Key Growth Drivers
Rising Demand for Long-Endurance Aerial Operations
The Solar Powered Drone Market is strongly driven by the increasing need for long-endurance aerial platforms across defense, telecommunications, environmental monitoring, and disaster management applications. Solar-powered drones offer extended flight durations ranging from several days to weeks, enabling continuous data collection over large geographic areas. This capability significantly reduces operational interruptions and refueling requirements compared to conventional battery-powered drones. Governments and commercial operators increasingly deploy these systems for border surveillance, maritime monitoring, and climate observation, reinforcing demand for high-altitude, long-endurance unmanned aerial solutions.
- For instance, Garuda Aerospace's SURAJ drone, unveiled at Aero India 2023, features J-shaped solar-powered wings and an auxiliary battery for 12-hour endurance at 3,000 feet altitude.
Expansion of Renewable Energy and Sustainability Initiatives
Growing global emphasis on renewable energy adoption and carbon footprint reduction is accelerating growth in the Solar Powered Drone Market. Solar-powered drones align with sustainability objectives by minimizing reliance on fossil fuels and reducing operational emissions. Public-sector agencies, research institutions, and enterprises are prioritizing environmentally responsible technologies for aerial monitoring and inspection tasks. Regulatory support for clean-energy solutions and rising investments in green aviation technologies further strengthen adoption. These factors collectively position solar-powered drones as an integral component of future low-emission aerial infrastructure.
- For instance, Airbus's Zephyr UAV set three world records in 2010, including a longest endurance flight of 336 hours powered solely by solar energy, enabling persistent surveillance without fossil fuel use.
Increasing Adoption Across Commercial and Industrial Applications
The expanding use of drones across commercial and industrial sectors is a key growth driver for the Solar Powered Drone Market. Industries such as agriculture, utilities, oil and gas, and infrastructure increasingly rely on drones for mapping, inspection, and monitoring. Solar-powered drones provide cost-efficient operations by lowering maintenance and energy expenses while extending mission duration. Their ability to cover vast agricultural fields, power transmission lines, and remote industrial assets without frequent landings supports productivity gains, making them attractive for large-scale, recurring operational deployments.
Key Trends & Opportunities
Advancements in Lightweight Materials and Solar Cell Efficiency
Technological advancements in lightweight composite materials and high-efficiency photovoltaic cells are creating significant opportunities in the Solar Powered Drone Market. Improved solar cell conversion rates enhance onboard power generation, while lightweight airframes increase payload capacity and flight endurance. These innovations enable manufacturers to design drones capable of operating at higher altitudes with greater reliability. Ongoing research into flexible solar panels and energy storage integration further supports next-generation drone development, opening opportunities for expanded commercial, scientific, and defense-oriented applications.
- For instance, Titan Aerospace's Solara 50 employs a carbon fiber composite frame with 3,000 photovoltaic cells across a 50-meter wingspan, enabling stratospheric flights at 20km altitude for extended durations.
Growing Integration with AI and Advanced Data Analytics
The integration of artificial intelligence and advanced data analytics represents a major trend in the Solar Powered Drone Market. Solar-powered drones increasingly incorporate AI-driven navigation, real-time image processing, and autonomous decision-making capabilities. These features enhance mission efficiency for applications such as precision agriculture, infrastructure inspection, and surveillance. The ability to analyze large datasets during extended flights improves situational awareness and reduces data processing delays. This trend creates opportunities for solution providers offering intelligent drone platforms with integrated analytics and cloud-based data management systems.
- For instance, XSun's SolarXOne drone employs an advanced autopilot system with Embention’s Veronte for 100% automated flight, including AI-enabled adaptive control, real-time RTK positioning to centimeter accuracy, and obstacle avoidance during extended solar-powered missions up to 600 km.
Key Challenges
High Initial Development and Deployment Costs
High initial development and deployment costs remain a significant challenge in the Solar Powered Drone Market. Advanced materials, high-efficiency solar panels, and specialized avionics increase manufacturing expenses compared to conventional drones. Additionally, extensive research, testing, and certification requirements add to overall investment costs. These financial barriers can limit adoption among small and mid-sized enterprises. While long-term operational savings are substantial, the upfront capital requirement continues to restrain market penetration, particularly in price-sensitive commercial segments.
Technical Limitations and Weather Dependency
Technical limitations related to weather dependency pose challenges for the Solar Powered Drone Market. Solar-powered drones rely heavily on consistent sunlight, making performance vulnerable to cloud cover, seasonal variations, and adverse weather conditions. Limited energy generation during low-light environments can restrict payload operation and mission reliability. Furthermore, balancing power storage, weight constraints, and flight stability remains complex. Addressing these challenges requires continuous advancements in energy storage systems, hybrid power integration, and adaptive flight technologies to ensure consistent performance across diverse operating environments.
Regional Analysis
North America
North America led the Solar Powered Drone Market in 2024, holding a market share of 38% due to strong defense spending, advanced drone technology adoption, and robust government initiatives supporting solar energy integration. The United States and Canada prioritized long-endurance unmanned aerial missions for border security, environmental monitoring, and disaster response, which amplified demand for solar-powered platforms. A mature aerospace ecosystem, ongoing R&D investments, and supportive regulatory frameworks further bolstered growth. Strategic collaborations between military agencies and tech firms reinforced North America’s leadership in rugged, high-performance solar drone deployment.
Europe
Europe accounted for a market share of 22% in the Solar Powered Drone Market in 2024, propelled by sustainability initiatives and increasing commercial applications. European countries, including Germany, France, and the UK, invested in long-endurance UAVs for environmental monitoring, precision agriculture, and infrastructure inspection. Strong policy support for renewable energy adoption and carbon reduction targets encouraged solar-drone integration into national security and civilian programs. Rising partnerships between aerospace manufacturers and energy-tech providers further stimulated expansion. Growth was further supported by improved regulatory harmonization for beyond-visual-line-of-sight (BVLOS) operations and green technology funding.
Asia-Pacific
Asia-Pacific captured a market share of 28% in 2024, driven by government modernization programs, expanding defense budgets, and quick adoption in agriculture and logistics. China, Japan, India, and South Korea emerged as key contributors, focusing on solar-powered drones for border security, disaster management, and large-scale agricultural surveying. Rapid infrastructure development and increasing investments in renewable technologies supported the region’s growth trajectory. Additionally, rising commercial drone startups and partnerships with international tech firms helped Asia-Pacific narrow the gap with Western markets, reinforcing the region’s strategic importance in future solar UAV deployment.
Latin America
Latin America held a market share of 7% in the Solar Powered Drone Market in 2024, with notable growth in environmental monitoring, mining operations, and agricultural applications. Countries such as Brazil and Argentina increased use of solar drones to survey vast rural landscapes, conduct forestry monitoring, and support precision farming. Limited infrastructure and geographic challenges made solar drones attractive for low-cost, long-duration missions. However, slower regulatory progress and constrained R&D funding moderated regional expansion. Continued investment in drone training, technology adaptation, and cross-border collaborations is expected to strengthen Latin America’s market position.
Middle East & Africa
The Middle East & Africa region accounted for a market share of 5% in 2024, supported by defense modernization and energy sector applications. Gulf Cooperation Council (GCC) countries prioritized solar-powered drones for border surveillance, oilfield inspection, and environmental monitoring in remote desert areas. African markets showed emerging adoption in wildlife protection and agricultural data collection, leveraging solar drones’ long-endurance capabilities where infrastructure is limited. Regional growth was tempered by economic constraints and investment gaps. Nonetheless, strategic defense contracts and renewable energy partnerships provide opportunities for future expansion.
Market Segmentations:
By Drone Type:
- Fixed Wing
- Rotary Wing
- Hybrid
By Application:
- Filming & Photography
- Inspection & Maintenance
- Mapping & Surveying
- Precision Agriculture
- Surveillance & Monitoring
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Airbus Defence and Space, BAE Systems, AeroVironment, Aurora Flight Sciences, Kea Aerospace, Silent Falcon UAS Technologies, AtlantikSolar, XSun, DJI, Parrot Drones. The Solar Powered Drone Market features a mix of aerospace primes, defense innovators, and specialist UAV startups competing on endurance, payload efficiency, autonomy, and reliable high-altitude operations. Established aerospace and defense firms leverage deep R&D budgets, flight-test infrastructure, and government relationships to advance high-altitude, long-endurance platforms for persistent surveillance and communications. Specialist players differentiate through lightweight airframes, high-efficiency photovoltaic integration, and mission-specific sensor packages for mapping, monitoring, and inspection use cases. Commercial drone brands increasingly explore solar augmentation and energy-optimized platforms to extend flight times in permissive environments. Partnerships with telecom operators, component suppliers, and analytics providers strengthen end-to-end offerings, while regulatory progress for BVLOS operations and airspace integration shapes go-to-market speed and deployment scale.
Key Player Analysis
- DJI
- Silent Falcon UAS Technologies
- Aurora Flight Sciences
- LG Uplus
- Atlantiksolar
- Kea Aerospace
- KT Corp
- UAV Instruments
- Parrot Drones
- Xsun
Recent Developments
- In December 2025, VisionWave Holdings announced the acquisition of Solar Drone Ltd., an autonomous robotics company specializing in solar-powered drones for defense and solar operations and maintenance.
- In July 2025, XSun partnered with H3 Dynamics to develop a new UAV combining solar energy, hydrogen fuel cells, and battery storage for extended flight endurance. This tri-source system targets VTOL, STOL, and HTOL platforms with intelligent power management.
- In February 2025, Kea Aerospace completed a solar-powered stratospheric flight with its Kea Atmos platform, marking progress in high-altitude imaging and long-endurance missions.
Report Coverage
The research report offers an in-depth analysis based on Drone Type, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Solar powered drones will see wider adoption for long-endurance surveillance and monitoring missions across defense and civil applications.
- Continuous improvements in solar cell efficiency will significantly enhance flight endurance and operational reliability.
- Integration of artificial intelligence will enable higher levels of autonomous navigation and real-time data processing.
- Commercial sectors such as agriculture, utilities, and infrastructure will increasingly deploy solar powered drones for large-area coverage.
- Regulatory advancements for beyond-visual-line-of-sight operations will accelerate large-scale commercial deployments.
- Hybrid power architectures will gain traction to address energy variability and mission flexibility.
- Telecom and connectivity applications will expand, using solar powered drones as aerial communication platforms.
- Manufacturing costs will gradually decline as lightweight materials and standardized components mature.
- Strategic partnerships between drone manufacturers and renewable energy providers will intensify.
- Emerging economies will present new growth opportunities driven by remote monitoring and sustainability initiatives.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Demand for Long-Endurance Aerial Operations
Solar-powered drones enable missions lasting days or weeks, supporting persistent surveillance, border security, and environmental monitoring with minimal refueling, which is highly valued by defense and government agencies.
Expansion of Renewable Energy and Sustainability Initiatives
Global emphasis on reducing carbon emissions and adopting clean energy technologies is driving the adoption of solar-powered drones, as they offer low-emission, energy-efficient alternatives for aerial operations.
Technological Advancements in Solar Cells and Lightweight Materials
Improvements in photovoltaic efficiency and composite materials are increasing drone endurance and payload capacity, making solar-powered drones more viable for high-altitude and long-range missions.
Growth in Commercial and Industrial Applications
Industries such as agriculture, utilities, and infrastructure are increasingly deploying solar-powered drones for large-area mapping, inspection, and monitoring, benefiting from reduced operational costs and extended flight times.
Integration of AI and Autonomous Capabilities
The adoption of AI-driven navigation and real-time data analytics enhances the operational efficiency and autonomy of solar-powered drones, enabling more complex and data-intensive missions across various sectors.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Solar Powered Drone Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Solar Powered Drone Market projected to grow between 2024 and 2032?
How efficient are the latest solar panels used in solar-powered drones?
What challenges does the solar-powered drone market face in terms of regulations?
Are there any notable collaborations between drone manufacturers and solar technology companies?
Who are the leading companies in the Solar Powered Drone Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Drone Type
- 1.2.1 Fixed Wing
- 1.2.2 Rotary Wing
- 1.2.3 Hybrid
- 1.3 By Application
- 1.3.1 Surveillance & Monitoring
- 1.3.2 Mapping & Surveying
- 1.3.3 Inspection & Maintenance
- 1.3.4 Precision Agriculture
- 1.3.5 Filming & Photography
- 1.3.6 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 2,690 million → 2032: USD 10,319.31 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Solar-Powered Drone Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Solar-Powered Drone Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Solar-Powered Drone Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Solar-Powered Drone Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Solar-Powered Drone Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Solar-Powered Drone Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Solar-Powered Drone Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Solar-Powered Drone Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 2,690 million → 2032: USD 10,319.31 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Solar-Powered Drone Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Drone Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Fixed Wing
- 12.3.7.2 Rotary Wing
- 12.3.7.3 Hybrid
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Surveillance & Monitoring
- 12.4.7.2 Mapping & Surveying
- 12.4.7.3 Inspection & Maintenance
- 12.4.7.4 Precision Agriculture
- 12.4.7.5 Filming & Photography
- 12.4.7.6 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Solar-Powered Drone End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Solar-Powered Drone Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Solar-Powered Drone Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Solar-Powered Drone Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Airbus Defence and Space
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 AeroVironment
- 18.4 Aurora Flight Sciences
- 18.5 Kea Aerospace
- 18.6 Silent Falcon UAS Technologies
- 18.7 AtlantikSolar
- 18.8 XSun
- 18.9 DJI
- 18.10 Parrot Drones
- 18.11 BAE Systems
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

