
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Airport Ground and Cargo Handling Services Market 2023 | USD 37.7 billion |
| Airport Ground and Cargo Handling Services Market, CAGR | 6.96% |
| Airport Ground and Cargo Handling Services Market Size 2032 | USD 73.3 billion |
Market Overview
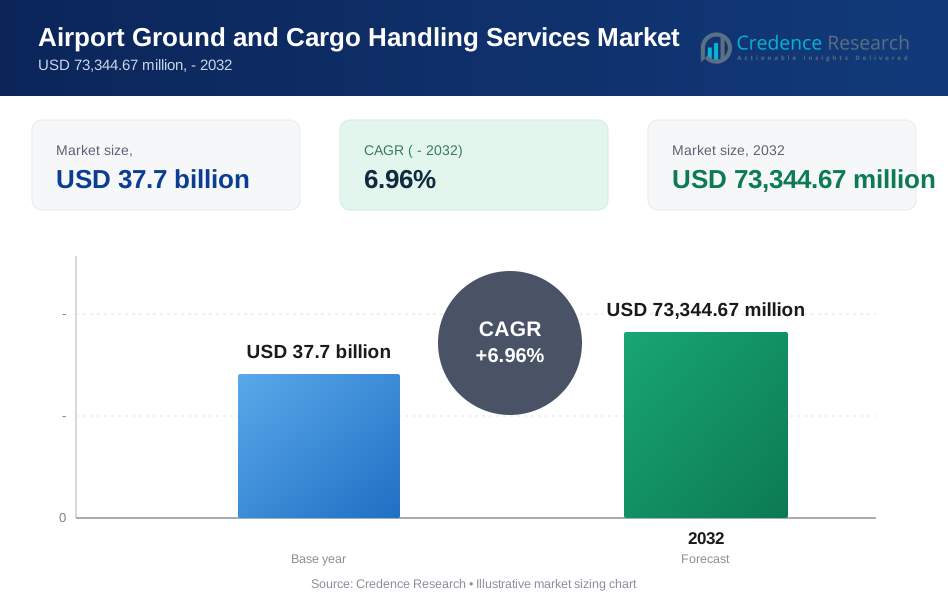
The Airport Ground and Cargo Handling Services Market is expected to surge from USD 37.7 billion in 2023 to USD 73.3 billion by 2032, growing at a CAGR of 6.96% between 2024 and 2032.
As air travel continues to surge, especially in emerging economies, airports are witnessing a corresponding increase in demand for ground and cargo handling services. This market evolution is driven by a confluence of factors including rising passenger traffic, burgeoning e-commerce activities, and globalization, which collectively underscore the criticality of efficient ground and cargo handling operations in the aviation sector.
One of the primary drivers fueling this market expansion is the escalating air passenger traffic globally. As disposable incomes rise and travel becomes more accessible, airports are experiencing a surge in the number of flights and passengers. This heightened activity necessitates streamlined ground handling services to ensure smooth operations, minimize delays, and enhance passenger experience. Additionally, the exponential growth of e-commerce has catalyzed a surge in air cargo volumes, further underscoring the significance of efficient cargo handling services. With consumers increasingly relying on online shopping, the demand for rapid and reliable cargo transportation solutions is escalating, driving the need for advanced ground handling infrastructure and services.
Furthermore, globalization has intensified trade activities, prompting airports to fortify their cargo handling capabilities to accommodate the burgeoning freight volumes. As businesses increasingly engage in cross-border trade, airports serve as pivotal hubs facilitating the movement of goods between regions. Consequently, airport operators are investing in state-of-the-art cargo handling facilities and technologies to bolster their competitive edge and cater to the evolving demands of the logistics industry. Moreover, the emphasis on sustainability and environmental stewardship is influencing market dynamics, with airports endeavoring to adopt eco-friendly ground handling practices and technologies to mitigate their carbon footprint and comply with stringent regulatory mandates.
The Airport Ground and Cargo Handling Services Market are on a robust growth trajectory, propelled by escalating air travel demand, burgeoning e-commerce activities, and globalization. With the market poised to almost double in value over the next decade, stakeholders across the aviation and logistics sectors are poised to capitalize on emerging opportunities. However, to harness the full potential of this market, industry players must prioritize innovation, operational efficiency, and sustainability to meet the evolving needs of airlines, logistics firms, and passengers alike.
Segmentation Analysis
By Services
- Ground Handling Services: This segment encompasses a wide range of services including baggage handling, aircraft marshalling, fueling, and catering. Ground handling services are essential for ensuring the efficient turnaround of aircraft, minimizing ground time, and enhancing overall operational efficiency.
- Cargo Handling Services: Cargo handling services involve the loading, unloading, and transportation of freight, parcels, and mail. With the exponential growth of e-commerce and international trade, the demand for efficient cargo handling services is soaring, driving investments in advanced cargo handling infrastructure and technologies.
- Passenger Handling Services: Passenger handling services encompass check-in, boarding, security screening, and passenger assistance. As airports strive to enhance the passenger experience and streamline passenger flows, investments in innovative technologies such as biometric authentication and self-service kiosks are gaining traction.
By Airport Type
- Commercial Airports: Commercial airports serve scheduled passenger flights and handle a significant volume of cargo traffic. These airports require comprehensive ground and cargo handling services to accommodate diverse aircraft types and manage peak traffic periods efficiently.
- Cargo Airports: Cargo airports primarily focus on handling freight traffic and often specialize in expedited cargo operations. These airports require specialized infrastructure such as dedicated cargo terminals, warehousing facilities, and advanced cargo handling equipment to support rapid cargo processing and distribution.
- General Aviation Airports: General aviation airports cater to private, corporate, and recreational aviation activities. While the demand for ground and cargo handling services at general aviation airports is relatively lower compared to commercial and cargo airports, these facilities still require basic handling services for passengers and light aircraft.
By Infrastructure Type
- Terminal Facilities: Terminal facilities encompass passenger terminals, cargo terminals, and ancillary facilities such as lounges, retail outlets, and restaurants. Investments in terminal infrastructure are crucial for enhancing passenger comfort, optimizing operational flows, and accommodating evolving security requirements.
- Ground Support Equipment (GSE): GSE includes a diverse range of equipment such as aircraft tugs, baggage loaders, and ground power units essential for aircraft ground operations. Upgrading and modernizing GSE infrastructure is imperative for improving operational efficiency, reducing turnaround times, and minimizing environmental impact.
- Cargo Handling Infrastructure: Cargo handling infrastructure comprises cargo terminals, warehouses, and specialized equipment such as cargo loaders, forklifts, and palletizing systems. Robust cargo handling infrastructure is essential for facilitating the seamless flow of goods, optimizing storage capacity, and ensuring the timely delivery of cargo shipments.
Segmentations
By Services
- Ground Handling Services
- Cargo Handling Services
- Passenger Handling Services
By Airport Type
- Commercial Airports
- Cargo Airports
- General Aviation Airports
By Infrastructure Type
- Terminal Facilities
- Ground Support Equipment (GSE)
- Cargo Handling Infrastructure
- North America
- The U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
Market Drivers
Escalating Air Passenger Traffic:
The relentless growth in air passenger traffic globally serves as a primary driver propelling the Airport Ground and Cargo Handling Services Market forward. For instance, the air passenger traffic growth rate was 31.2% year-on-year in October 2023. With increasing affluence, urbanization, and accessibility of air travel, airports are witnessing a surge in the number of flights and passengers. This escalating demand necessitates efficient ground handling services to manage aircraft turnarounds, baggage handling, and passenger services. As airports strive to optimize their operational efficiency and enhance passenger experience, investments in advanced ground handling infrastructure, technologies, and workforce training are intensifying. Moreover, the rising trend of leisure and business travel, coupled with the emergence of low-cost carriers, further amplifies the demand for ground handling services, driving market growth.
Booming E-commerce Activities:
The exponential growth of e-commerce has revolutionized the logistics landscape, profoundly impacting the Airport Ground and Cargo Handling Services Market. As consumers increasingly prefer online shopping, there has been an unprecedented surge in air cargo volumes, driving the demand for efficient cargo handling services. E-commerce giants and retailers are increasingly relying on air freight to fulfill their delivery commitments, necessitating rapid and reliable cargo transportation solutions. Consequently, airports are investing in specialized cargo terminals, automated handling systems, and advanced tracking technologies to accommodate the burgeoning demand for air cargo services. Additionally, the integration of e-commerce supply chains with air transportation networks is fostering collaborations between airports, logistics firms, and e-commerce players, further fueling market growth.
Globalization and Trade Expansion:
The ongoing process of globalization and the expansion of international trade are instrumental in driving the growth of the Airport Ground and Cargo Handling Services Market. As businesses increasingly engage in cross-border trade, airports serve as pivotal hubs facilitating the movement of goods between regions. This burgeoning trade activity translates into a higher demand for cargo handling services, ranging from customs clearance to warehousing and distribution. For instance, the share of output moving across the world’s borders has fallen from 28.1 percent in 2007 to 22.5 percent in 2017. Airport operators are thus compelled to enhance their cargo handling infrastructure, invest in cutting-edge technologies, and streamline customs procedures to expedite the flow of goods and maintain competitiveness. Moreover, the proliferation of free trade agreements and economic corridors is further catalyzing trade volumes, thereby augmenting the demand for cargo handling services at airports worldwide.
Market Trends
Adoption of Automation and Robotics:
One prevailing trend in the airport ground and cargo handling services market is the increasing adoption of automation and robotics to streamline operations and enhance efficiency. Airport operators are deploying automated baggage handling systems, robotic cargo loaders, and autonomous ground vehicles to expedite handling processes, minimize human error, and improve throughput. These advanced technologies not only optimize resource utilization but also contribute to faster turnaround times, ultimately enhancing overall operational efficiency at airports. For instance, the new World Robotics report shows an all-time high of 517,385 new industrial robots installed in 2021 in factories around the world. This represents a growth rate of 31% year-on-year and exceeds the pre-pandemic record of robot installation in 2018 by 22%.
Emphasis on Sustainability and Environmental Initiatives:
With growing concerns about environmental sustainability, there is a notable trend within the airport ground and cargo handling services market towards implementing eco-friendly practices and technologies. Airport operators are investing in electric ground support equipment, renewable energy sources, and eco-efficient infrastructure to reduce carbon emissions and mitigate environmental impacts. Additionally, initiatives such as waste reduction, recycling programs, and water conservation measures are becoming increasingly prevalent as airports strive to align with sustainability goals and regulatory requirements.
Integration of Digital Solutions and IoT:
Another significant trend shaping the airport ground and cargo handling services market is the integration of digital solutions and Internet of Things (IoT) technology to enhance operational visibility and decision-making. Airport stakeholders are leveraging IoT sensors, data analytics platforms, and real-time monitoring systems to track assets, optimize resource allocation, and proactively manage ground and cargo handling processes.
Focus on Enhancing the Passenger Experience:
In response to evolving passenger expectations, there is a growing trend towards prioritizing the enhancement of the passenger experience within the airport ground and cargo handling services market. Airport operators are investing in innovative technologies such as self-service kiosks, biometric authentication systems, and digital wayfinding solutions to streamline passenger flows, reduce wait times, and provide personalized services. Moreover, amenities such as lounges, retail outlets, and dining options are being upgraded to offer a more comfortable and engaging airport experience for travelers.
Rise of Urban Air Mobility (UAM):
The emergence of urban air mobility (UAM) solutions, including electric vertical takeoff and landing (eVTOL) aircraft and autonomous drones, is fueling a new trend in the airport ground and cargo handling services market. As cities explore aerial mobility options for urban transportation and logistics, airports are adapting their infrastructure and services to accommodate these next-generation aircraft. Ground handling providers are gearing up to support the unique requirements of UAM operations, including rapid turnaround times, charging infrastructure, and airspace management, thereby positioning themselves to capitalize on this burgeoning market segment.
Increasing Focus on Resilience and Business Continuity:
In light of recent disruptions such as natural disasters, pandemics, and geopolitical tensions, there is a heightened focus within the Airport Ground and Cargo Handling Services Market on resilience and business continuity planning. Airport operators are investing in robust contingency measures, redundancy strategies, and crisis management protocols to ensure the uninterrupted flow of goods and passengers during unforeseen events. This includes the development of flexible infrastructure, remote monitoring capabilities, and contingency staffing arrangements to adapt to rapidly changing operational conditions and maintain service reliability.
Market Restraints and Challenges
Infrastructure Constraints:
One of the primary challenges facing the Airport Ground and Cargo Handling Services Market is the limitations posed by existing infrastructure. Many airports, particularly those in densely populated urban areas, struggle with constrained land availability and outdated facilities, which hinder their ability to expand and modernize ground and cargo handling operations. The lack of adequate space for additional runways, taxiways, and cargo terminals constrains capacity growth and exacerbates congestion, leading to operational inefficiencies and delays. Addressing these infrastructure constraints requires significant investments in land acquisition, facility expansion, and infrastructure upgrades, which can be time-consuming and capital-intensive.
Regulatory Compliance and Security Requirements:
The stringent regulatory environment governing airport operations, coupled with evolving security mandates, presents a considerable challenge for stakeholders in the Airport Ground and Cargo Handling Services Market. Airport operators must adhere to a myriad of regulations imposed by civil aviation authorities, customs agencies, and security agencies, ranging from safety standards to cargo screening protocols. Compliance with these regulations necessitates continuous investment in training, technology upgrades, and procedural enhancements, adding complexity and costs to ground and cargo handling operations. Moreover, the dynamic nature of security threats requires airports to remain vigilant and adaptable, further straining resources and operational resilience.
Labor Shortages and Skilled Workforce:
Another significant challenge confronting the Airport Ground and Cargo Handling Services Market is the persistent shortage of skilled labor and trained workforce. Ground handling tasks such as baggage loading, aircraft marshalling, and cargo handling require specialized skills and expertise, yet the industry grapples with recruitment and retention challenges. Factors contributing to the shortage of skilled workers include demographic shifts, competition from other industries, and the demanding nature of airport operations. Additionally, the seasonal nature of air travel exacerbates workforce fluctuations, leading to operational disruptions and service inconsistencies. To address this challenge, industry stakeholders must invest in training and development programs, adopt innovative workforce management strategies, and explore automation solutions to augment human labor.
Cost Pressures and Profit Margins:
Airport Ground and Cargo Handling Services Market face ongoing pressures to reduce costs and maintain competitive pricing amidst escalating operational expenses. Airport operators are under constant pressure to optimize resource utilization, minimize turnaround times, and enhance productivity, all while balancing the need for quality service and safety standards. However, rising costs associated with labor, fuel, infrastructure maintenance, and regulatory compliance strain profit margins, particularly for ground handling providers operating on thin margins. Furthermore, competitive pricing dynamics and contract negotiations with airlines and cargo operators add further complexity to revenue generation and profitability. To remain viable in this challenging environment, companies must implement cost-saving measures, explore revenue diversification opportunities, and seek operational efficiencies through technological innovations.
Key players
- Swissport International Ltd.
- dnata
- Worldwide Flight Services (WFS)
- SATS Ltd.
- Menzies Aviation
- Japan Airport Terminal Co., Ltd.
- Celebi Aviation Holding
- Lufthansa Cargo AG
- Air France-KLM Cargo & Martinair Cargo
- CargoTec Holding GmbH
Recent Developments
- Swissport and Unilode Aviation Solutions Partnership (June 15, 2023): Swissport International Ltd. teams up with Unilode Aviation Solutions to boost its cargo handling capabilities. This collaboration focuses on enhancing ULD pooling, tracking, and management, aiming to improve ULD utilization, operational efficiency, and cargo visibility across Swissport's global airport network. This move highlights Swissport's dedication to innovation and superior customer service in the airport ground and cargo handling sector.
- WFS Opens New Cargo Terminal at JFK (August 22, 2023): Worldwide Flight Services (WFS) expands its cargo handling services with a new, advanced cargo terminal at JFK International Airport. This state-of-the-art facility boosts WFS's capacity and introduces sustainable handling technologies, responding to the increasing demand for air cargo services in North America and reinforcing WFS's leadership in ground and cargo handling solutions.
- SATS, Airbus, and Rolls-Royce SAF Initiative (October 10, 2023): SATS Ltd. partners with Airbus and Rolls-Royce on a groundbreaking pilot to use sustainable aviation fuel (SAF) in ground support equipment (GSE) at Singapore Changi Airport. This initiative aims to cut carbon emissions, supporting SATS's commitment to sustainability and innovation in the airport services market. It aligns with Singapore's ambition to become a top sustainable aviation hub and highlights the aviation industry's push towards decarbonization.
Regional Analysis
The Airport Ground and Cargo Handling Services Market exhibit significant regional variations, shaped by factors such as economic development, air travel demand, infrastructure investments, and regulatory frameworks. North America dominates the market, accounting for the largest share with approximately 35% of the global market. The region's leading position can be attributed to its well-established aviation infrastructure, robust trade activities, and the presence of major airports serving as key international hubs. The United States, in particular, boasts a vast network of airports and a thriving air cargo industry, driving demand for ground and cargo handling services.
Following closely behind, Europe commands a substantial market share of around 30%. The region benefits from a dense network of airports, serving both passenger and cargo traffic across diverse markets. Countries such as Germany, the United Kingdom, and France host major airports that play pivotal roles in connecting global trade routes. Additionally, the European Union's stringent regulations regarding safety, security, and environmental standards drive investments in advanced ground handling infrastructure and technologies, further bolstering market growth.
Asia Pacific emerges as a rapidly growing region in the Airport Ground and Cargo Handling Services Market, capturing approximately 25% of the global market share. The region's dynamic economic growth, burgeoning middle class, and expanding e-commerce activities drive robust air passenger and cargo traffic. Countries like China, India, and Japan witness significant investments in airport infrastructure and logistics facilities to accommodate the escalating demand for aviation services. Moreover, the rise of low-cost carriers and the emergence of mega-airports in the region contribute to the increasing need for efficient ground and cargo handling services.
Latin America and the Middle East & Africa regions collectively account for the remaining 10% of the global market share. While these regions exhibit considerable growth potential, they face unique challenges such as political instability, infrastructure constraints, and regulatory complexities. Nevertheless, strategic initiatives aimed at modernizing airport facilities, enhancing connectivity, and fostering trade relationships are driving investments in ground and cargo handling services across these regions. Additionally, the Middle East's strategic geographic location as a global aviation crossroads and Latin America's growing role in global trade contribute to the market's expansion in these regions.
Future Outlook
- The Airport Ground and Cargo Handling Services Market are projected to witness sustained growth in the coming years, driven by increasing air passenger and cargo traffic globally.
- Ongoing advancements in automation, robotics, and digitalization will revolutionize ground handling operations, enhancing efficiency and reliability.
- There will be a heightened focus on sustainability initiatives, with airports investing in eco-friendly infrastructure and practices to mitigate environmental impact.
- The integration of artificial intelligence (AI) and Internet of Things (IoT) technology will enable predictive maintenance, real-time tracking, and data-driven decision-making in ground handling processes.
- Airports will prioritize enhancing the passenger experience through seamless check-in procedures, personalized services, and innovative amenities.
- Airports will adapt to the rise of urban air mobility (UAM) technologies, catering to the growing demand for electric vertical takeoff and landing (eVTOL) aircraft and drone deliveries.
- There will be a greater emphasis on resilience and business continuity planning, with airports investing in redundancy measures and crisis management protocols to mitigate disruptions.
- Compliance with evolving regulatory standards, particularly in areas such as safety, security, and environmental sustainability, will remain a key focus for airport operators.
- The expansion of international trade and the proliferation of free trade agreements will drive demand for cargo handling services, necessitating investments in cargo infrastructure and logistics capabilities.
- Industry stakeholders will increasingly collaborate to optimize operational efficiencies, share resources, and address common challenges, fostering innovation and competitiveness in the market.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Escalating Air Passenger Traffic
The continuous rise in global air passenger numbers, driven by increasing affluence, urbanization, and the proliferation of low-cost carriers, is boosting demand for efficient ground and passenger handling services at airports to ensure smooth operations and minimize delays.
Booming E-commerce Activities
The rapid expansion of e-commerce has led to a surge in air cargo volumes, requiring airports to invest in advanced cargo handling infrastructure and technologies to meet the need for fast, reliable, and high-capacity cargo services.
Globalization and Trade Expansion
Growing international trade and cross-border business activities are increasing the volume of goods transported by air, compelling airports to enhance their cargo handling capabilities and streamline customs and logistics processes.
Adoption of Automation and Digital Solutions
Airports and service providers are increasingly implementing automation, robotics, and IoT technologies to optimize ground and cargo handling operations, reduce human error, and improve turnaround times, thereby supporting market growth.
Focus on Sustainability and Environmental Initiatives
Rising regulatory and societal pressure for greener operations is driving airports to adopt eco-friendly ground support equipment and sustainable practices, which not only reduce environmental impact but also align with evolving industry standards and customer expectations.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected market size of the Airport Ground and Cargo Handling Services Market for 2023, 2032, and the Compound Annual Growth Rate (CAGR)?
What factors are driving the growth of the Airport Ground and Cargo Handling Services Market?
What are some key trends shaping the Airport Ground and Cargo Handling Services Market?
What are the main challenges faced by stakeholders in the Airport Ground and Cargo Handling Services Market?
Which regions hold significant market share in the Airport Ground and Cargo Handling Services Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Services
- 1.2.1 Ground Handling Services
- 1.2.2 Cargo Handling Services
- 1.2.3 Passenger Handling Services
- 1.3 By Airport Type
- 1.3.1 Commercial Airports
- 1.3.2 Cargo Airports
- 1.3.3 General Aviation Airports
- 1.4 By Infrastructure Type
- 1.4.1 Terminal Facilities
- 1.4.2 Ground Support Equipment (GSE)
- 1.4.3 Cargo Handling Infrastructure
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 37.7 billion → 2032: USD 73,344.67 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Airport Ground and Cargo Handling Services Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Airport Ground and Cargo Handling Services Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Airport Ground and Cargo Handling Services Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Airport Ground and Cargo Handling Services Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Airport Ground and Cargo Handling Services Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Airport Ground and Cargo Handling Services Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Airport Ground and Cargo Handling Services Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Airport Ground and Cargo Handling Services Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 37.7 billion → 2032: USD 73,344.67 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Airport Ground and Cargo Handling Services Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Services - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Base-Year Market Share, 2023
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Ground Handling Services
- 12.3.6.2 Cargo Handling Services
- 12.3.6.3 Passenger Handling Services
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Airport Type - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Base-Year Market Share, 2023
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Commercial Airports
- 12.4.6.2 Cargo Airports
- 12.4.6.3 General Aviation Airports
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Infrastructure Type - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Base-Year Market Share, 2023
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Terminal Facilities
- 12.5.6.2 Ground Support Equipment (GSE)
- 12.5.6.3 Cargo Handling Infrastructure
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Airport Ground and Cargo Handling Services Geographic Market Outlook, 2023-2032
- 13.1 Regional Market Size and Share, 2023
- 13.2 Regional Market Forecast, 2023-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Airport Ground and Cargo Handling Services Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Energy Efficiency and Resource Management
- 14.7 Sustainability, Recycling and Circularity
- 14.8 Technology Roadmap, 2023-2032
- 14.9 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Airport Ground and Cargo Handling Services Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2023
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2023-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Swissport International Ltd.
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Financial Performance and Investment
- 17.2.6 Market Share and Competitive Position
- 17.2.7 Technology and Innovation Capabilities
- 17.2.8 Strategic Alliances or Partnerships
- 17.2.9 Recent Developments
- 17.2.10 Growth Strategy and Outlook
- 17.3 dnata
- 17.4 Worldwide Flight Services (WFS)
- 17.5 SATS Ltd.
- 17.6 Menzies Aviation
- 17.7 Japan Airport Terminal Co., Ltd.
- 17.8 Celebi Aviation Holding
- 17.9 Lufthansa Cargo AG
- 17.10 Air France-KLM Cargo & Martinair Cargo
- 17.11 CargoTec Holding GmbH
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

