
Market Overview
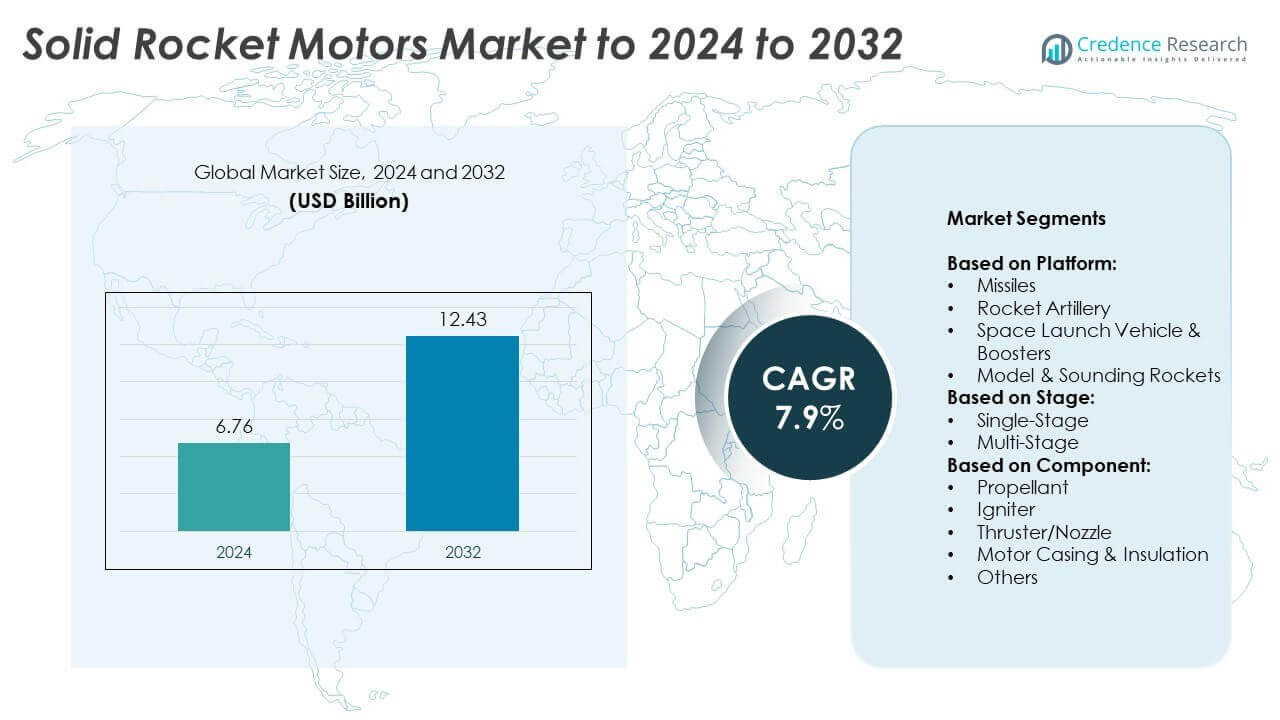
The Solid Rocket Motors Market size was valued at USD 6.76 billion in 2024 and is anticipated to reach USD 12.43 billion by 2032, at a CAGR of 7.9% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Solid Rocket Motors Market Size 2024 | USD 6.76 Billion |
| Solid Rocket Motors Market, CAGR | 7.9% |
| Solid Rocket Motors Market Size 2032 | USD 12.43 Billion |
The Solid Rocket Motors market is driven by prominent players including Northrop Grumman Corp, Aerojet Rocketdyne, Nammo AS, Rafael Advanced Defense Systems, Avio S.p.A., L3Harris Technologies Inc., and China Aerospace Science and Technology Corporation. These companies focus on advanced propulsion technologies, defense modernization, and space launch programs to maintain competitiveness. North America led the global market in 2024 with a 38% share, supported by strong defense budgets and active space initiatives. Europe followed with 27%, driven by missile development and ESA-backed space programs, while Asia Pacific held 22%, emerging as the fastest-growing region due to expanding missile systems and ambitious space exploration projects.
 Market Insights
- The Solid Rocket Motors market size was valued at USD 6.76 billion in 2024 and is projected to reach USD 12.43 billion by 2032, growing at a CAGR of 7.9%.
- Rising defense expenditure and increasing demand for tactical and strategic missile systems are driving steady market expansion worldwide.
- Emerging trends include the integration of solid rocket motors into hypersonic systems, advances in composite propellants, and miniaturized modular designs for flexible applications.
- The market is highly competitive with established players focusing on R&D, strategic contracts, and collaborations with private space firms to strengthen their global presence.
- North America led with 38% share in 2024, followed by Europe at 27% and Asia Pacific at 22%; missiles dominated by platform with 45% share, while single-stage motors accounted for 55% of the stage segment, making them the most widely adopted across defense and space applications.
Market Segmentation Analysis:
By Platform
The missiles segment accounted for the largest share of the Solid Rocket Motors market in 2024, holding nearly 45%. Demand is driven by rising defense modernization programs and investments in missile systems for national security. Countries such as the U.S., China, and India are expanding missile stockpiles, boosting adoption of solid rocket motors due to their reliability and rapid launch capabilities. Space launch vehicles and boosters also show strong growth, supported by increasing satellite launches and commercial space exploration initiatives, but remain behind missiles in overall market share.
- For instance, NASA’s SLS uses two SRBs, each at 3.6 million lbf thrust for 126 s, with 1.6 million lb total weight. These SRBs burn about six tons per second.
By Stage
Single-stage solid rocket motors dominated the market with a share of around 55% in 2024. Their simplicity, cost-effectiveness, and widespread application in tactical missiles and short-range rockets make them the preferred choice. Multi-stage motors are growing at a faster pace, mainly fueled by the rising number of space launches and long-range missile programs. The flexibility and performance of multi-stage systems enhance thrust efficiency, but single-stage solutions remain dominant due to high-volume adoption across defense and artillery applications.
- For instance, the European Space Agency's (ESA) P120C solid rocket motor carries 142,000 kg of solid propellant, burns for approximately 130-135 seconds, and delivers a maximum thrust of 4,650 kN.
By Component
Propellant led the component segment with over 40% share in 2024, as it is the core material determining motor performance, burn rate, and payload capacity. Increasing R&D for high-energy composite propellants strengthens its position in defense and space applications. The motor casing and insulation also play a significant role, ensuring structural integrity under extreme pressure and temperature conditions. However, propellants remain the dominant sub-segment, supported by ongoing advances in energetic materials that enhance propulsion efficiency and reduce overall launch costs.
Key Growth Drivers
Rising Defense Expenditure
Increasing defense spending across major economies is the leading growth driver for the Solid Rocket Motors market. Countries such as the U.S., China, Russia, and India are allocating higher budgets to strengthen missile capabilities and upgrade their existing defense systems. Solid rocket motors are preferred in military applications because of their rapid launch readiness, long storage life, and high reliability under combat conditions. Governments are expanding procurement of tactical and strategic missile systems, boosting large-scale production of solid rocket motors. The growing emphasis on national security, missile defense programs, and modernization of armed forces ensures that demand for these propulsion systems remains strong and sustained over the coming years.
- For instance, Lockheed Martin produced 500+ PAC-3 MSE interceptors in 2024, with plans targeting 650 per year by 2027. Reported deliveries in 2025 are projected at ~600+ units.
Expansion of Space Exploration Programs
The growing focus on satellite deployment, interplanetary missions, and commercial space travel has created strong demand for solid rocket motors. Government agencies like NASA, ESA, ISRO, and CNSA, along with private companies, are increasingly using solid rocket boosters for their ability to deliver powerful initial thrust and support heavy payload launches. Solid motors remain integral in multi-stage rockets, offering high energy efficiency at relatively lower costs. The surge in low-Earth orbit satellite constellations for communications and navigation also drives usage. Furthermore, the increasing interest in lunar exploration and Mars missions amplifies their demand. With both government-backed and private-led exploration activities expanding, space applications are becoming one of the most lucrative growth drivers for the market.
- For instance, the first stage of ISRO's Polar Satellite Launch Vehicle (PSLV) carries 138 metric tons of HTPB-based solid propellant, producing a maximum thrust of approximately 4,800 kN.
Technological Advancements in Propellants
Innovations in propellant chemistry and design have significantly strengthened the efficiency of solid rocket motors. Advancements in composite propellants allow for improved burn rates, enhanced thrust, and better stability under extreme conditions, which directly benefits defense and space applications. In addition, the integration of lightweight materials and additive manufacturing is reducing production costs while improving design flexibility and performance. Efforts to develop eco-friendly and low-toxicity propellants are also gaining momentum as regulatory pressures grow. These technological shifts are reshaping the industry by providing more reliable and environmentally conscious propulsion systems. Continuous R&D investments ensure that improvements in thrust capability, fuel efficiency, and structural integrity keep solid rocket motors highly competitive against alternative propulsion technologies.
Key Trends & Opportunities
Commercialization of Space Activities
The growing role of private aerospace companies is reshaping the solid rocket motors landscape, creating fresh opportunities for propulsion suppliers. Firms like SpaceX, Rocket Lab, and Blue Origin are ramping up launches for telecommunications, navigation, and scientific research, often requiring reliable boosters and motor stages. The rise in small satellite constellations has created new demand for cost-effective launch vehicles where solid motors play a crucial role. With more companies entering the space sector and developing affordable launch services, the dependence on solid rocket motors is expected to increase. This commercialization trend broadens the customer base beyond government agencies and drives sustained long-term growth opportunities.
- For instance, Ariane 6/Vega-C P120C uses a carbon-fibre filament-wound case and HTPB propellant of ~142 t. This reduces mass while maintaining high thrust.
Integration with Hypersonic Systems
Hypersonic weapon development is a major trend shaping the solid rocket motors market. Defense organizations are focusing on missiles capable of speeds above Mach 5, which demand high-thrust propulsion systems. Solid rocket motors are being adapted to meet these requirements, providing the initial acceleration and energy needed for hypersonic glide vehicles and maneuverable warheads. Countries like the U.S., China, and Russia are heavily investing in these programs, opening significant opportunities for manufacturers to align with next-generation defense technologies. The rapid global race for hypersonic supremacy ensures that demand for advanced solid rocket motors will remain high in the near future.
- For instance, L3Harris (formerly via Aerojet Rocketdyne) hot-fired the eSR-19 solid motor design, which uses a graphite composite case and improved propellant formulation.
Miniaturized and Modular Designs
The development of compact, modular solid rocket motors is emerging as a vital trend to serve evolving defense and space needs. These motors provide flexibility for integration across small tactical missiles, portable rocket artillery, and low-cost satellite launches. Modular designs also reduce costs, simplify production, and enhance scalability across applications. Growing demand for responsive launch capabilities, particularly for micro- and nano-satellites, further strengthens this trend. By addressing the needs of both large defense contractors and small aerospace companies, miniaturized and modular solutions are creating new market segments and unlocking wider adoption opportunities.
Key Challenges
Environmental and Safety Concerns
Environmental and safety issues are among the most pressing challenges in the solid rocket motors market. Traditional propellants contain chemicals that release toxic emissions during production, testing, and launches, raising ecological and health concerns. International environmental regulations are becoming more stringent, forcing manufacturers to adopt sustainable solutions or risk compliance penalties. Additionally, handling and storing hazardous propellant materials require strict safety measures and advanced facilities, increasing operational complexity and cost. Companies are investing in developing greener propellants, but the transition is slow and expensive. Addressing these environmental and safety concerns is crucial to ensuring long-term market growth without regulatory restrictions.
High Development and Testing Costs
The production and validation of solid rocket motors involve extremely high costs, limiting participation from smaller firms and emerging players. Advanced facilities are needed for propellant formulation, casing design, and full-scale testing, making the process capital intensive. Defense and space applications demand rigorous quality checks, adding further expense and complexity. The reliance on specialized materials and technologies drives costs even higher, slowing down new entrants and innovation cycles. For established companies, scaling production is feasible, but for smaller players, barriers to entry remain high. These financial challenges continue to restrict the competitive landscape and create dependency on large government contracts for revenue sustainability.
Regional Analysis
North America
North America held the largest share of the Solid Rocket Motors market in 2024, accounting for nearly 38%. The region benefits from strong defense budgets, advanced aerospace capabilities, and active space exploration programs led by NASA and private firms. The U.S. dominates regional demand with continuous investments in missile defense, tactical weapon systems, and satellite launches. Canada also contributes through defense modernization and collaborations with U.S. aerospace companies. Growing adoption of hypersonic programs further supports market expansion, positioning North America as the global leader in solid rocket motor development and deployment during the forecast period.
Europe
Europe captured around 27% of the global Solid Rocket Motors market in 2024, driven by increasing missile programs and space missions led by ESA and national defense agencies. Countries such as France, Germany, and the UK are investing in tactical and long-range missile systems, strengthening defense reliance on solid rocket propulsion. The Ariane space launch program also contributes significantly to demand for boosters and multi-stage motors. Collaborative defense initiatives and NATO-backed modernization projects further fuel adoption. With emphasis on both defense security and space innovation, Europe remains a strong market, maintaining its position as the second-largest regional contributor.
Asia Pacific
Asia Pacific accounted for nearly 22% of the Solid Rocket Motors market in 2024, supported by rising defense modernization and rapid growth in space activities. China, India, Japan, and South Korea are expanding missile programs while boosting satellite launch capabilities. ISRO’s frequent launches and China’s ambitious lunar and planetary missions highlight growing reliance on solid rocket boosters. Rising territorial tensions also accelerate demand for missile-based defense systems across the region. With expanding government funding and increasing participation of private aerospace companies, Asia Pacific is projected to witness the fastest growth among all regions in the forecast period.
Middle East & Africa
The Middle East & Africa region represented about 8% of the global Solid Rocket Motors market in 2024. Growth is primarily driven by strong defense investments in countries like Saudi Arabia, Israel, and the UAE, where missile defense programs remain a strategic priority. Local collaborations with international defense suppliers further enhance regional capabilities. Africa shows limited adoption but is gradually increasing participation through joint defense projects. Although smaller in share, the region demonstrates consistent growth prospects due to rising geopolitical tensions and the continuous focus on strengthening national security through advanced missile systems and propulsion technologies.
Latin America
Latin America held a 5% share of the global Solid Rocket Motors market in 2024, with Brazil being the primary contributor due to its space program and defense modernization efforts. The Brazilian Space Agency’s satellite launches and missile development initiatives drive regional demand. Other countries like Argentina and Mexico show limited adoption but are gradually increasing defense spending. Although the region lags behind others in scale, investments in space exploration and localized defense industries are supporting steady growth. The focus on expanding aerospace capabilities ensures that Latin America remains a developing but important contributor to the global market.
Market Segmentations:
By Platform:
- Missiles
- Rocket Artillery
- Space Launch Vehicle & Boosters
- Model & Sounding Rockets
By Stage:
- Single-Stage
- Multi-Stage
By Component:
- Propellant
- Igniter
- Thruster/Nozzle
- Motor Casing & Insulation
- Others
By Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Solid Rocket Motors market is shaped by leading companies such as Kratos Defense & Security Solutions, Nammo AS, Rafael Advanced Defense Systems, Ursa Major, Avio S.p.A., L3Harris Technologies, China Aerospace Science and Technology Corporation, Anduril, Bayern-Chemie, Aerojet Rocketdyne, X-Bow, IHI Corporation, and Northrop Grumman Corp. These companies compete through advanced product portfolios, strategic partnerships, and investments in new technologies to strengthen their positions in defense and space applications. The market is characterized by innovation in high-energy propellants, modular designs, and eco-friendly propulsion systems. Global players are focusing on meeting rising defense demands for tactical and strategic missiles, while also catering to the growing commercial space sector. Strategic contracts with defense agencies, expansion into emerging regions, and collaboration with private space firms are key competitive strategies. Strong R&D pipelines, coupled with large-scale production capabilities, ensure these players maintain a dominant role in the evolving global solid rocket motors market.
Key Player Analysis
- Kratos Defense & Security Solutions (U.S.)
- Nammo AS (Norway)
- Rafael Advanced Defense Systems Ltd (Israeli)
- Ursa Major (U.S.)
- Avio S.p.A. (Italy)
- L3Harris Technologies Inc. (U.S.)
- China Aerospace Science and Technology Corporation (China)
- Anduril (U.S.)
- Bayern-Chemie (Germany)
- Aerojet Rocketdyne
- X-Bow (U.S.)
- IHI Corporation (Japan)
- Northrop Grumman Corp (U.S.)
Recent Developments
- In 2023, Northrop Grumman successfully manufactured the first set of solid rocket motor cases for the Missile Defense Agency's NGI program, demonstrating new case designs and manufacturing processes.
- In 2023, Aerojet Rocketdyne secured a $215.6 million cooperative agreement with the Department of Defense (DoD). This investment was used to modernize and expand production facilities in Arkansas, Alabama, and Virginia to increase output of GMLRS, Stinger, and Javelin missiles.
- In 2023, Anduril acquired Adranos, a specialized manufacturer of solid rocket motors. This acquisition was aimed at increasing competition and strengthening the US SRM supply base.
Report Coverage
The research report offers an in-depth analysis based on Platform, Stage, Component and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will grow steadily, supported by defense modernization programs worldwide.
- Missile systems will remain the dominant application due to rising security concerns.
- Space launch vehicles will gain traction with increasing satellite deployment.
- Technological innovation in composite propellants will enhance motor efficiency.
- Hypersonic missile development will create strong demand for advanced solid rocket motors.
- Modular and miniaturized designs will expand adoption across defense and space sectors.
- North America will continue leading, while Asia Pacific will record the fastest growth.
- Environmental regulations will push research toward greener propellant alternatives.
- High R&D investments will drive competitiveness among global players.
- Collaboration between defense agencies and private space firms will accelerate market expansion.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Defense Expenditure
Major economies are increasing defense budgets to modernize missile systems and strengthen national security, directly boosting demand for solid rocket motors due to their reliability and rapid launch capabilities.
Expansion of Space Exploration Programs
Government agencies and private companies are launching more satellites and interplanetary missions, driving the need for solid rocket motors as essential boosters for heavy payloads and multi-stage rockets.
Technological Advancements in Propellants
Innovations in composite propellants and manufacturing processes are improving thrust, efficiency, and environmental performance, making solid rocket motors more attractive for both defense and space applications.
Commercialization of Space Activities
The entry of private aerospace firms and the growth of small satellite constellations are expanding the customer base for solid rocket motors, creating new opportunities beyond traditional government contracts.
Integration with Hypersonic Systems
The global race to develop hypersonic weapons is increasing demand for advanced solid rocket motors capable of delivering high thrust and rapid acceleration for next-generation missile systems.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Solid Rocket Motors Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Solid Rocket Motors Market projected to grow between 2025 and 2032?
Which Solid Rocket Motors Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Solid Rocket Motors Market?
Who are the leading companies in the Solid Rocket Motors Market?
Which region commanded the largest share of the Solid Rocket Motors Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Stage
- 1.2.1 Single-Stage
- 1.2.2 Multi-Stage
- 1.3 By Platform
- 1.3.1 Missiles
- 1.3.2 Rocket Artillery
- 1.3.3 Space Launch Vehicle & Boosters
- 1.3.4 Model & Sounding Rockets
- 1.4 By Component
- 1.4.1 Propellant
- 1.4.2 Igniter
- 1.4.3 Thruster/Nozzle
- 1.4.4 Motor Casing & Insulation
- 1.4.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 6.76 billion → 2032: USD 12.43 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Solid Rocket Motors Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Solid Rocket Motors Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Solid Rocket Motors Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Solid Rocket Motors Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Solid Rocket Motors Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Solid Rocket Motors Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Solid Rocket Motors Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Solid Rocket Motors Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 6.76 billion → 2032: USD 12.43 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Solid Rocket Motors Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Stage - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Single-Stage
- 12.3.7.2 Multi-Stage
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Platform - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Missiles
- 12.4.7.2 Rocket Artillery
- 12.4.7.3 Space Launch Vehicle & Boosters
- 12.4.7.4 Model & Sounding Rockets
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Component - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Propellant
- 12.5.7.2 Igniter
- 12.5.7.3 Thruster/Nozzle
- 12.5.7.4 Motor Casing & Insulation
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Solid Rocket Motors Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Solid Rocket Motors Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Solid Rocket Motors Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Northrop Grumman Corp
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Aerojet Rocketdyne
- 17.4 Nammo AS
- 17.5 Rafael Advanced Defense Systems
- 17.6 Avio S.p.A.
- 17.7 L3Harris Technologies Inc.
- 17.8 China Aerospace Science and Technology Corporation
- 17.9 Kratos Defense & Security Solutions
- 17.10 Bayern-Chemie
- 17.11 IHI Corporation
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

