
Market Overview
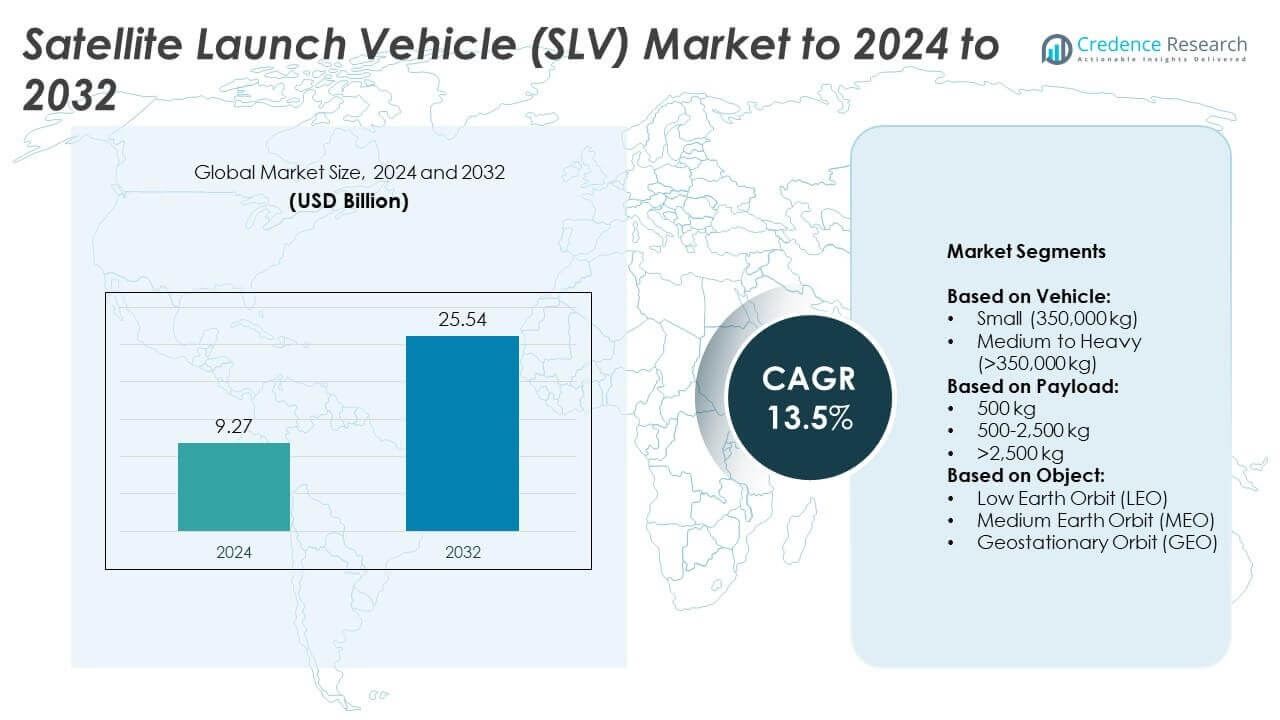
Satellite Launch Vehicle (SLV) Market size was valued at USD 9.27 Billion in 2024 and is anticipated to reach USD 25.54 Billion by 2032, at a CAGR of 13.5% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Satellite Launch Vehicle (SLV) Market Size 2024 | USD 9.27 Billion |
| Satellite Launch Vehicle (SLV) Market, CAGR | 13.5% |
| Satellite Launch Vehicle (SLV) Market Size 2032 | USD 25.54 Billion |
The Satellite Launch Vehicle (SLV) market is driven by prominent players including Relativity Space, SpaceX, Blue Origin, Northrop Grumman Corporation, United Launch Alliance (ULA), ISRO, Arianespace, Rocket Lab USA, Inc., Firefly Aerospace, Boeing Defense, Space & Security, Lockheed Martin Corporation, Mitsubishi Heavy Industries, Rocket Factory Augsburg (RFA), and Virgin Orbit. These companies compete through advancements in reusable launch technologies, cost-efficient small satellite launch services, and strategic collaborations. Regionally, North America held the largest share with 40% in 2024, supported by strong government programs and private investments. Asia Pacific followed with 28% share, fueled by China, India, and Japan’s expanding launch capabilities, while Europe accounted for 25%, highlighting its established infrastructure and ESA-driven projects.
 Market Insights
- The Satellite Launch Vehicle market size was USD 9.27 billion in 2024 and is expected to reach USD 25.54 billion by 2032, growing at a CAGR of 13.5%.
- Growth is driven by rising demand for small satellite launches, supported by government funding and advancements in reusable technologies that reduce launch costs and improve turnaround times.
- Key trends include expansion of mega-constellation projects for global broadband coverage and increasing private sector participation, offering flexible and rapid launch solutions.
- The market is competitive with major players focusing on innovation, partnerships, and expanding payload capacities; companies are investing in sustainable propulsion systems and reusable vehicles to strengthen their positions.
- Regionally, North America led with 40% share in 2024, followed by Asia Pacific at 28% and Europe at 25%, while the rest of the world contributed 7%; small vehicle launches dominated by holding over 55% segment share in 2024.
Market Segmentation Analysis:
By Vehicle
The small satellite launch vehicle segment, with a capacity of up to 350,000 kg, held the dominant market share of over 55% in 2024. Growth is fueled by rising demand for small satellite constellations supporting Earth observation, remote sensing, and communication services. Companies and governments favor smaller vehicles due to cost efficiency, quicker turnaround times, and dedicated payload deployment. Increasing adoption of CubeSats and nanosatellites further accelerates demand. Startups and private launch service providers have strengthened this segment by offering responsive, low-cost access to space for commercial and defense applications.
- For instance, Rocket Lab's Electron vehicle completed its 70th launch on August 23, 2025. As of late September 2025, the Electron vehicle has completed 71 launches in total.
By Payload
The 500–2,500 kg payload segment accounted for the largest market share, exceeding 50% in 2024. This range balances cost-effectiveness and capability, making it suitable for communications, navigation, and Earth observation satellites. Demand is rising from commercial operators deploying small and medium-sized satellite constellations for broadband and imaging services. Flexibility to support both civil and defense missions further strengthens adoption. Expanding government space programs and private ventures are boosting investments in mid-range payload capacities, ensuring consistent demand across established players and new entrants in the SLV market.
- For instance, Arianespace's Vega-C launcher successfully placed the 296 kg LARES-2 satellite, along with six other satellites, into orbit on its inaugural flight in July 2022. The total payload mass for the mission was approximately 474 kg.
By Object
Low Earth Orbit (LEO) dominated the market, representing more than 60% share in 2024. Its dominance is driven by rising deployment of satellite constellations for broadband internet, Earth monitoring, and defense surveillance. LEO offers reduced latency, lower launch costs, and shorter satellite replacement cycles, making it the preferred choice for commercial players such as satellite internet providers. Rapid advancements in reusable launch vehicle technology and growing support for mega-constellation projects strengthen this orbit category. Increased demand for real-time data services and global connectivity ensures sustained growth in LEO-focused launch vehicle deployments.
Key Growth Drivers
Rising Demand for Small Satellites
The increasing deployment of small satellite constellations for communication, Earth observation, and remote sensing is a key growth driver in the SLV market. Organizations are launching CubeSats and nanosatellites to support applications like broadband internet and disaster management. This demand fuels the need for cost-effective and flexible small satellite launch vehicles. Growing commercial participation and defense applications are further accelerating the adoption of dedicated small satellite launches. As a result, the segment’s expansion is pushing overall market growth and creating new opportunities for private launch providers.
- For instance, SpaceX in 2023 launched a total of 96 Falcon family missions, which consisted of 91 Falcon 9 and five Falcon Heavy rockets. Most of these missions delivered payloads to Low Earth Orbit (LEO).
Government Investments in Space Programs
Rising investments from governments and space agencies remain a major growth driver. National space programs across the U.S., Europe, China, and India are expanding launch vehicle capabilities to strengthen global positioning, security, and scientific missions. Strategic funding supports both reusable technologies and next-generation heavy-lift vehicles. Countries are prioritizing sovereign space access, increasing collaboration with private companies, and driving infrastructure development. These initiatives enhance launch frequency and innovation, directly boosting demand for SLVs. Government-backed missions also offer stability to the industry, ensuring consistent growth and technological progress.
- For instance, Planet Labs operates over 200 active satellites globally in its Earth-imaging constellations.
Advancement in Reusable Launch Technology
The development of reusable launch vehicles is a key growth driver, reducing launch costs and improving turnaround times. Companies such as SpaceX and Blue Origin are demonstrating successful reusability, encouraging adoption across the industry. Reusability enhances efficiency by lowering the per-launch expense and increasing operational sustainability. This advancement is particularly beneficial for commercial satellite operators deploying large constellations. It also attracts new entrants by making launches more accessible. As reusability technology matures, it will significantly reshape the SLV market’s cost dynamics and competitiveness.
Key Trends & Opportunities
Growth of Mega-Constellation Projects
The rapid expansion of mega-constellation projects presents a major trend in the SLV market. Operators like SpaceX, OneWeb, and Amazon’s Kuiper Project are planning thousands of satellite launches for global broadband coverage. This surge drives consistent demand for frequent and cost-effective launches. It also fuels opportunities for small and medium-capacity launch vehicles. The increasing requirement for coordinated, high-volume deployment creates space for partnerships between launch providers and satellite manufacturers. Mega-constellations represent one of the most significant opportunities for long-term SLV market growth.
- For instance, ISRO’s PSLV-C58 mission launched on January 1, 2024, with the primary payload XPoSat. After placing XPoSat in orbit, the mission conducted experiments with 10 other payloads on the PSLV Orbital Experimental Module-3 (POEM-3).
Increasing Private Sector Participation
Private sector involvement is a key opportunity, shaping innovation and competition. Startups and established aerospace firms are developing dedicated launch services with faster timelines and customized solutions. Rising venture capital funding and favorable regulatory reforms further support commercialization. Private players are addressing niche markets, such as quick-response launches and micro-satellite deployments. Their agility in adopting reusable technology and digital manufacturing enhances competitiveness. This trend expands the market ecosystem and offers new growth opportunities beyond traditional government contracts, creating a more dynamic and diversified industry landscape.
- For instance, Amazon's Project Kuiper is licensed by the FCC to launch a full constellation of 3,236 satellites, but the first deployment phase consists of 578 satellites at a 630 km altitude. Limited service may begin once this initial phase is complete, and launches for the constellation began in April 2025.
Key Challenges
High Development and Launch Costs
The significant capital required for SLV development remains a key challenge. Designing and manufacturing launch vehicles involves high material costs, rigorous testing, and advanced infrastructure. Even with reusable systems, initial investments remain steep for new entrants. Unsuccessful launches also risk financial losses and delays in satellite programs. Limited access to funding in developing countries further restricts participation. These factors create entry barriers and intensify competition among existing players. Cost pressures continue to challenge market expansion, particularly for small and emerging companies.
Stringent Regulatory and Safety Standards
The SLV market faces challenges due to strict regulatory frameworks and safety requirements. Launches must comply with international treaties, national laws, and space debris mitigation standards. Meeting these requirements increases compliance costs and lengthens approval processes. Safety concerns during launches also demand heavy investment in testing and monitoring systems. These complexities often delay missions and raise operational risks for providers. As global launch activity grows, navigating evolving regulatory landscapes and ensuring sustainable space operations remain ongoing challenges for both government and private players.
Regional Analysis
North America
North America held the largest share of the Satellite Launch Vehicle market in 2024, accounting for 40%. The region benefits from strong presence of key players, extensive government funding, and private sector initiatives. SpaceX, Blue Origin, and United Launch Alliance lead advancements in reusable technologies and heavy-lift vehicles. Growing demand for commercial satellite launches, defense applications, and communication networks further drives growth. NASA’s programs and increasing defense budgets support consistent launch activities. Strategic collaborations between government and private firms ensure technological innovation, reinforcing North America’s leadership in the global SLV market.
Europe
Europe captured 25% share of the Satellite Launch Vehicle market in 2024, supported by well-established space infrastructure and joint projects. The European Space Agency (ESA) drives advancements through programs focusing on sustainability and commercial access to space. Countries like France, Germany, and the United Kingdom play major roles with active contributions to satellite launches. Development of the Ariane and Vega series highlights regional innovation in heavy and medium vehicles. Emphasis on space autonomy, environmental responsibility, and growing partnerships with commercial operators help Europe maintain a strong position in the global SLV industry.
Asia Pacific
Asia Pacific accounted for 28% share of the Satellite Launch Vehicle market in 2024, emerging as a dynamic growth hub. China, India, and Japan drive regional expansion with increasing investments in space exploration and commercial launches. China’s Long March series and India’s PSLV and GSLV programs highlight capabilities in low-cost, reliable launches. Rising demand for internet connectivity, Earth observation, and defense satellites boosts activity. Government-backed missions combined with private sector participation strengthen competitiveness. The region’s growing infrastructure and innovation in reusable technologies ensure Asia Pacific remains a critical contributor to future SLV market growth.
Latin America, the Middle East, and Africa
The rest of the world represented 7% share of the Satellite Launch Vehicle market in 2024, with contributions from regions such as Latin America, the Middle East, and Africa. Countries including Brazil and the United Arab Emirates are investing in space programs to strengthen national capabilities. These markets are gradually expanding through partnerships with global launch providers and technology transfers. Infrastructure development and policy reforms are encouraging commercial space activities. Although the share remains small, growing interest in space exploration and emerging satellite applications signal steady opportunities for regional growth in the long term.
Market Segmentations:
By Vehicle:
- Small (350,000 kg)
- Medium to Heavy (>350,000 kg)
By Payload:
- 500 kg
- 500-2,500 kg
- >2,500 kg
By Object:
- Low Earth Orbit (LEO)
- Medium Earth Orbit (MEO)
- Geostationary Orbit (GEO)
By Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Satellite Launch Vehicle (SLV) market is highly competitive, shaped by leading players such as Relativity Space, Northrop Grumman Corporation, Virgin Orbit, Rocket Lab USA, Inc., Boeing Defense, Space & Security, Firefly Aerospace, United Launch Alliance (ULA), ISRO, Arianespace, SpaceX, Lockheed Martin Corporation, Mitsubishi Heavy Industries, Rocket Factory Augsburg (RFA), and Blue Origin. The competitive landscape is driven by rapid advancements in reusable technology, cost-effective small satellite launches, and increasing demand for mega-constellation projects. Companies focus on developing reliable, flexible, and sustainable launch solutions to address diverse commercial, defense, and governmental needs. Strategic collaborations, joint ventures, and public-private partnerships are common approaches to enhance technological capabilities and expand market reach. Continuous investment in research and development supports innovation in payload capacity, turnaround efficiency, and eco-friendly propulsion systems. Competition remains intense, with firms striving to differentiate through specialized services, rapid response launch offerings, and integrated solutions for satellite deployment across various orbital levels.
Key Player Analysis
- Relativity Space
- Northrop Grumman Corporation
- Virgin Orbit
- Rocket Lab USA, Inc.
- Boeing Defense, Space & Security
- Firefly Aerospace
- United Launch Alliance (ULA)
- ISRO (Indian Space Research Organisation)
- Arianespace
- SpaceX
- Lockheed Martin Corporation
- Mitsubishi Heavy Industries, Ltd.
- Rocket Factory Augsburg (RFA)
- Blue Origin
Recent Developments
- In 2025, Ariane 6 successfully completed its first commercial mission, launching the CSO-3 military observation satellite for the French Ministry of Defense.
- In 2025, SpaceX (USA) 10th test flight of Starship, achieved key milestones, including the successful deployment of Starlink mass simulator satellites and an in-orbit engine reignition.
- In 2025, United Launch Alliance (ULA) (USA) Vulcan launched its first national security mission (USSF-106) for the U.S. Space Force, after receiving certification.
Report Coverage
The research report offers an in-depth analysis based on Vehicle, Payload, Object and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for small satellite launches will continue to dominate due to cost efficiency.
- Reusable launch vehicle technology will gain wider adoption and reduce per-launch expenses.
- Mega-constellation projects will drive consistent demand for frequent and reliable launches.
- Government investments in national space programs will strengthen long-term market stability.
- Private companies will expand services with faster, flexible, and low-cost launch options.
- Low Earth Orbit deployments will remain the primary focus for commercial operators.
- Emerging markets will invest in space infrastructure and collaborate with global providers.
- Technological innovation will improve payload capacity and launch turnaround times.
- Regulatory frameworks will evolve to address space traffic management and debris control.
- Strategic partnerships between governments and private firms will shape global competitiveness.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Proliferation of Small Satellite Constellations
The surge in demand for small satellites, including CubeSats and nanosatellites, for applications such as Earth observation, broadband internet, and remote sensing is driving the need for frequent, cost-effective, and flexible launch solutions, particularly favoring small launch vehicles.
Advancements in Reusable Launch Technologies
Innovations in reusable rocket technology, led by companies like SpaceX and Blue Origin, are significantly reducing per-launch costs and turnaround times, making satellite launches more accessible and economically viable for both commercial and government operators.
Government Investments and National Space Programs
Substantial funding and strategic initiatives from governments and space agencies in the U.S., Europe, China, and India are expanding launch vehicle capabilities, supporting infrastructure development, and ensuring a steady pipeline of missions for scientific, defense, and commercial purposes.
Expansion of Mega-Constellation Projects
Large-scale projects such as Starlink, OneWeb, and Amazon Kuiper are planning thousands of satellite launches for global broadband coverage, creating sustained, high-volume demand for launch vehicles across multiple payload classes and orbits.
Increasing Private Sector Participation
The entry of private companies and startups, supported by venture capital and regulatory reforms, is fostering innovation, competition, and the development of specialized launch services, including rapid-response and dedicated micro-satellite launches.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Satellite Launch Vehicle (SLV) Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Satellite Launch Vehicle (SLV) Market projected to grow between 2025 and 2032?
Which Satellite Launch Vehicle (SLV) Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Satellite Launch Vehicle (SLV) Market?
Who are the major players in the Satellite Launch Vehicle Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Object
- 1.2.1 Low Earth Orbit (LEO)
- 1.2.2 Medium Earth Orbit (MEO)
- 1.2.3 Geostationary Orbit (GEO)
- 1.3 By Payload
- 1.3.1 ≤500 kg
- 1.3.2 500-2,500 kg
- 1.3.3 >2,500 kg
- 1.4 By Vehicle
- 1.4.1 Small (≤350,000 kg)
- 1.4.2 Medium to Heavy (>350,000 kg)
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 9.27 billion → 2032: USD 25.54 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Satellite Launch Vehicle Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Satellite Launch Vehicle Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Satellite Launch Vehicle Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Satellite Launch Vehicle Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Satellite Launch Vehicle Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Satellite Launch Vehicle Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Satellite Launch Vehicle Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Satellite Launch Vehicle Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 9.27 billion → 2032: USD 25.54 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Satellite Launch Vehicle Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Object - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Low Earth Orbit (LEO)
- 12.3.7.2 Medium Earth Orbit (MEO)
- 12.3.7.3 Geostationary Orbit (GEO)
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Payload - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 ≤500 kg
- 12.4.7.2 500-2,500 kg
- 12.4.7.3 >2,500 kg
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Vehicle - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Small (≤350,000 kg)
- 12.5.7.2 Medium to Heavy (>350,000 kg)
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Satellite Launch Vehicle Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Satellite Launch Vehicle Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Satellite Launch Vehicle Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 SpaceX
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Blue Origin
- 17.4 Arianespace
- 17.5 Rocket Lab USA, Inc.
- 17.6 United Launch Alliance (ULA)
- 17.7 ISRO
- 17.8 Northrop Grumman Corporation
- 17.9 Boeing Defense, Space & Security
- 17.10 Mitsubishi Heavy Industries
- 17.11 Relativity Space
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

