
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Soy-Based Chemicals Market Size 2024 | USD 28,996.80 million |
| Soy-Based Chemicals Market, CAGR | 7.59% |
| Soy-Based Chemicals Market Size 2032 | USD 52,069.72 million |
Market Overview
The global soy-based chemicals market is projected to grow from USD 28,996.80 million in 2024 to an estimated USD 52,069.72 million by 2032, with a compound annual growth rate (CAGR) of 7.59% from 2025 to 2032. This growth is driven by the increasing demand for sustainable and renewable alternatives to petroleum-based chemicals, as well as advancements in soy processing technologies.
Key drivers of this market include the rising demand for eco-friendly products, government incentives for bio-based materials, and technological advancements in soy processing. These factors are contributing to the widespread adoption of soy-based chemicals across various industries.
Geographically, North America holds a significant share of the soy-based chemicals market, attributed to its established soybean cultivation and processing infrastructure. The Asia-Pacific region is experiencing rapid growth, driven by industrial expansion and increasing awareness of sustainable practices. Major players in the market include Dow, Cargill, Archer Daniels Midland Company (ADM), Bunge Limited, and Elevance Renewable Sciences.
Market Insights
- The global soy-based chemicals market is projected to grow from USD 28,996.80 million in 2024 to USD 52,069.72 million by 2032, driven by a CAGR of 7.59% from 2025 to 2032.
- Increasing demand for eco-friendly and sustainable alternatives to petroleum-based chemicals is a key driver, with industries seeking renewable, biodegradable options.
- Advancements in soy processing technologies are enhancing production efficiency, driving the growth of soy-based chemicals across diverse industries.
- Government incentives and favorable policies promoting bio-based materials contribute to the market’s expansion, supporting the transition to more sustainable chemical solutions.
- Price volatility of soybeans and supply chain complexities can impact the cost-effectiveness of soy-based chemicals, posing a challenge for manufacturers.
- North America holds a significant share of the market, thanks to its established soybean cultivation infrastructure, while Asia-Pacific is seeing rapid market growth driven by industrial expansion.
- Major players like Dow, Cargill, ADM, Bunge, and Elevance Renewable Sciences lead the market, with increasing competition focused on innovation and meeting sustainability demands.
Market Drivers
Growing Demand for Sustainable and Renewable Alternatives
The increasing global emphasis on sustainability is a primary driver for the soy-based chemicals market. Consumers and industries are progressively seeking eco-friendly alternatives to traditional petroleum-based chemicals. Soy-based chemicals, derived from renewable and biodegradable soybeans, offer a sustainable solution that aligns with environmental goals. This shift is propelled by heightened awareness of environmental issues and the desire to reduce carbon footprints. As a result, soy-based chemicals are gaining traction across various sectors, including biodiesel, plastics, and personal care products, contributing to their growing market presence.
Technological Advancements Enhancing Production Efficiency
Advancements in biotechnology and chemical engineering have significantly improved the production processes of soy-based chemicals. Innovations in enzymatic and microbial conversion techniques have enhanced yield and purity, making soy chemicals more competitive with traditional petrochemicals. For instance, companies like Solvay have developed bio-based epichlorohydrin using advanced fermentation technologies, which improve efficiency and reduce environmental impact. These technological improvements not only increase production efficiency but also reduce costs, making soy-based chemicals a more attractive option for manufacturers. The continuous development in processing technologies is expected to further bolster the market growth of soy-based chemicals.
Supportive Government Policies and Regulations
Governments worldwide are implementing policies and providing incentives to promote the use of bio-based chemicals, thereby reducing reliance on fossil fuels and mitigating environmental pollution. For instance, the European Union's bioeconomy strategy has incentivized the adoption of bio-based alternatives, encouraging industries to transition towards sustainable practices. Such supportive measures are accelerating the growth of the soy-based chemicals market by creating a favorable environment for bio-based products.
Expanding Applications Across Diverse Industries
The versatility of soy-based chemicals is driving their adoption across a wide range of industries. From biodiesel and bioplastics to personal care products and paints, soy chemicals are increasingly replacing traditional petrochemical derivatives. This broad applicability is fueled by their renewable nature, biodegradability, and performance characteristics. As industries seek sustainable alternatives to meet consumer demand and regulatory requirements, the utilization of soy-based chemicals is expected to continue expanding, further propelling market growth.
Market Trends
Expansion of Applications in Bioplastics and Packaging
The soy-based chemicals market is increasingly focusing on the development of bioplastics and sustainable packaging solutions. Soy-derived polyols, such as soy-based polyols, are gaining traction in the production of biodegradable plastics, offering an eco-friendly alternative to conventional petroleum-based plastics. This shift is driven by growing environmental concerns and the need to reduce plastic waste. Companies are investing in research and development to enhance the performance and cost-effectiveness of soy-based bioplastics, aiming to meet the rising demand for sustainable packaging materials across various industries.
Regionalization of Production and Supply Chains
There is a noticeable trend towards regionalization in the production and supply chains of soy-based chemicals. This shift is driven by the need to reduce transportation costs, mitigate supply chain disruptions, and comply with local sustainability regulations. Companies are establishing production facilities closer to key markets and sourcing raw materials locally to enhance supply chain resilience. This approach not only supports local economies but also aligns with the increasing consumer demand for locally produced and sustainable product
Advancements in Soy-Based Surfactants and Personal Care Products
Innovations in soy-based surfactants are transforming the personal care and cosmetics industries. These bio-based surfactants, derived from soybeans, are being incorporated into shampoos, soaps, and lotions as sustainable alternatives to traditional petrochemical-based ingredients. For instance, Evonik has developed soy-based surfactants that enhance the sensory attributes of shampoos and lotions, meeting consumer demand for eco-friendly products. Research efforts are focused on improving the efficacy and sustainability of these surfactants, thereby expanding their application in high-performance personal care formulations.
Integration of Circular Economy Practices
The soy-based chemicals market is embracing circular economy principles by focusing on the reuse and recycling of soy-derived materials. This includes the development of soy-based adhesives and sealants that are biodegradable and can be recycled at the end of their life cycle. For instance, BASF has introduced soy-based adhesives designed for easy recycling, contributing to reduced environmental impact and promoting sustainability. The adoption of circular economy practices is becoming a key differentiator for companies aiming to align with global sustainability goals and meet regulatory requirements.
Market Challenges
Price Volatility and Supply Chain Complexity
A significant challenge in the global soy-based chemicals market is the inherent price volatility of soybeans, which can significantly impact production costs. Factors such as adverse weather conditions, fluctuating global demand, and geopolitical tensions contribute to unpredictable soybean prices. For instance, soybean prices experienced a 30% increase in 2024 due to drought conditions in major producing regions like Brazil and Argentina. This volatility affects the cost-effectiveness of producing soy-based chemicals, making it challenging for manufacturers to maintain stable pricing and profitability. Additionally, the complexity of the soy supply chain, involving multiple stages from cultivation to processing, further complicates cost management and forecasting. For instance, the United States Department of Agriculture (USDA) reported inefficiencies in soybean logistics, with transportation delays causing a 15% increase in operational costs for processors. Addressing these issues requires enhanced supply chain mapping, improved forecasting models, and strategic sourcing practices to mitigate the impact of price fluctuations and supply chain complexities.
Regulatory Compliance and Environmental Concerns
The soy-based chemicals industry faces increasing pressure to comply with stringent environmental regulations and sustainability standards. For instance, the European Union's Deforestation-Free Regulation (EUDR) mandates that imported soy must be traceable to ensure it is not linked to deforestation. This regulation imposes significant compliance costs and operational challenges for companies sourcing soy from regions where deforestation risks are high. Furthermore, the environmental impact of soy cultivation, including land-use changes and biodiversity concerns, necessitates responsible sourcing practices. Companies must invest in sustainable sourcing strategies, adopt traceability technologies, and collaborate with stakeholders to ensure compliance and mitigate environmental risks. Failure to adhere to these regulations can result in market access restrictions and damage to brand reputation.
Market Opportunities
Expansion into High-Performance Bioplastics and Polymers
The global soy-based chemicals market presents significant opportunities in the development of high-performance bioplastics and polymers. Soy-derived polyols, such as those used in polyurethane foams, are gaining traction in automotive applications, including seat cushions, insulation, and upholstery. These soy-based alternatives offer advantages like reduced weight, cost-effectiveness, and enhanced sustainability compared to traditional synthetic materials. As industries increasingly prioritize eco-friendly solutions, the demand for soy-based bioplastics is expected to grow, positioning them as viable substitutes for petroleum-based plastics in various applications.
Integration into Circular Economy and Waste Valorization
Another promising avenue lies in the integration of soy-based chemicals within circular economy frameworks. By utilizing soy-based waste streams, such as soybean hulls and press cakes, manufacturers can produce value-added chemicals, thereby minimizing waste and enhancing sustainability. This approach not only reduces environmental impact but also offers cost-effective solutions by maximizing resource utilization. The adoption of circular economy principles is gaining momentum, and soy-based chemicals play a pivotal role in this transition, offering a renewable and biodegradable alternative to conventional petrochemicals.
Market Segmentation Analysis
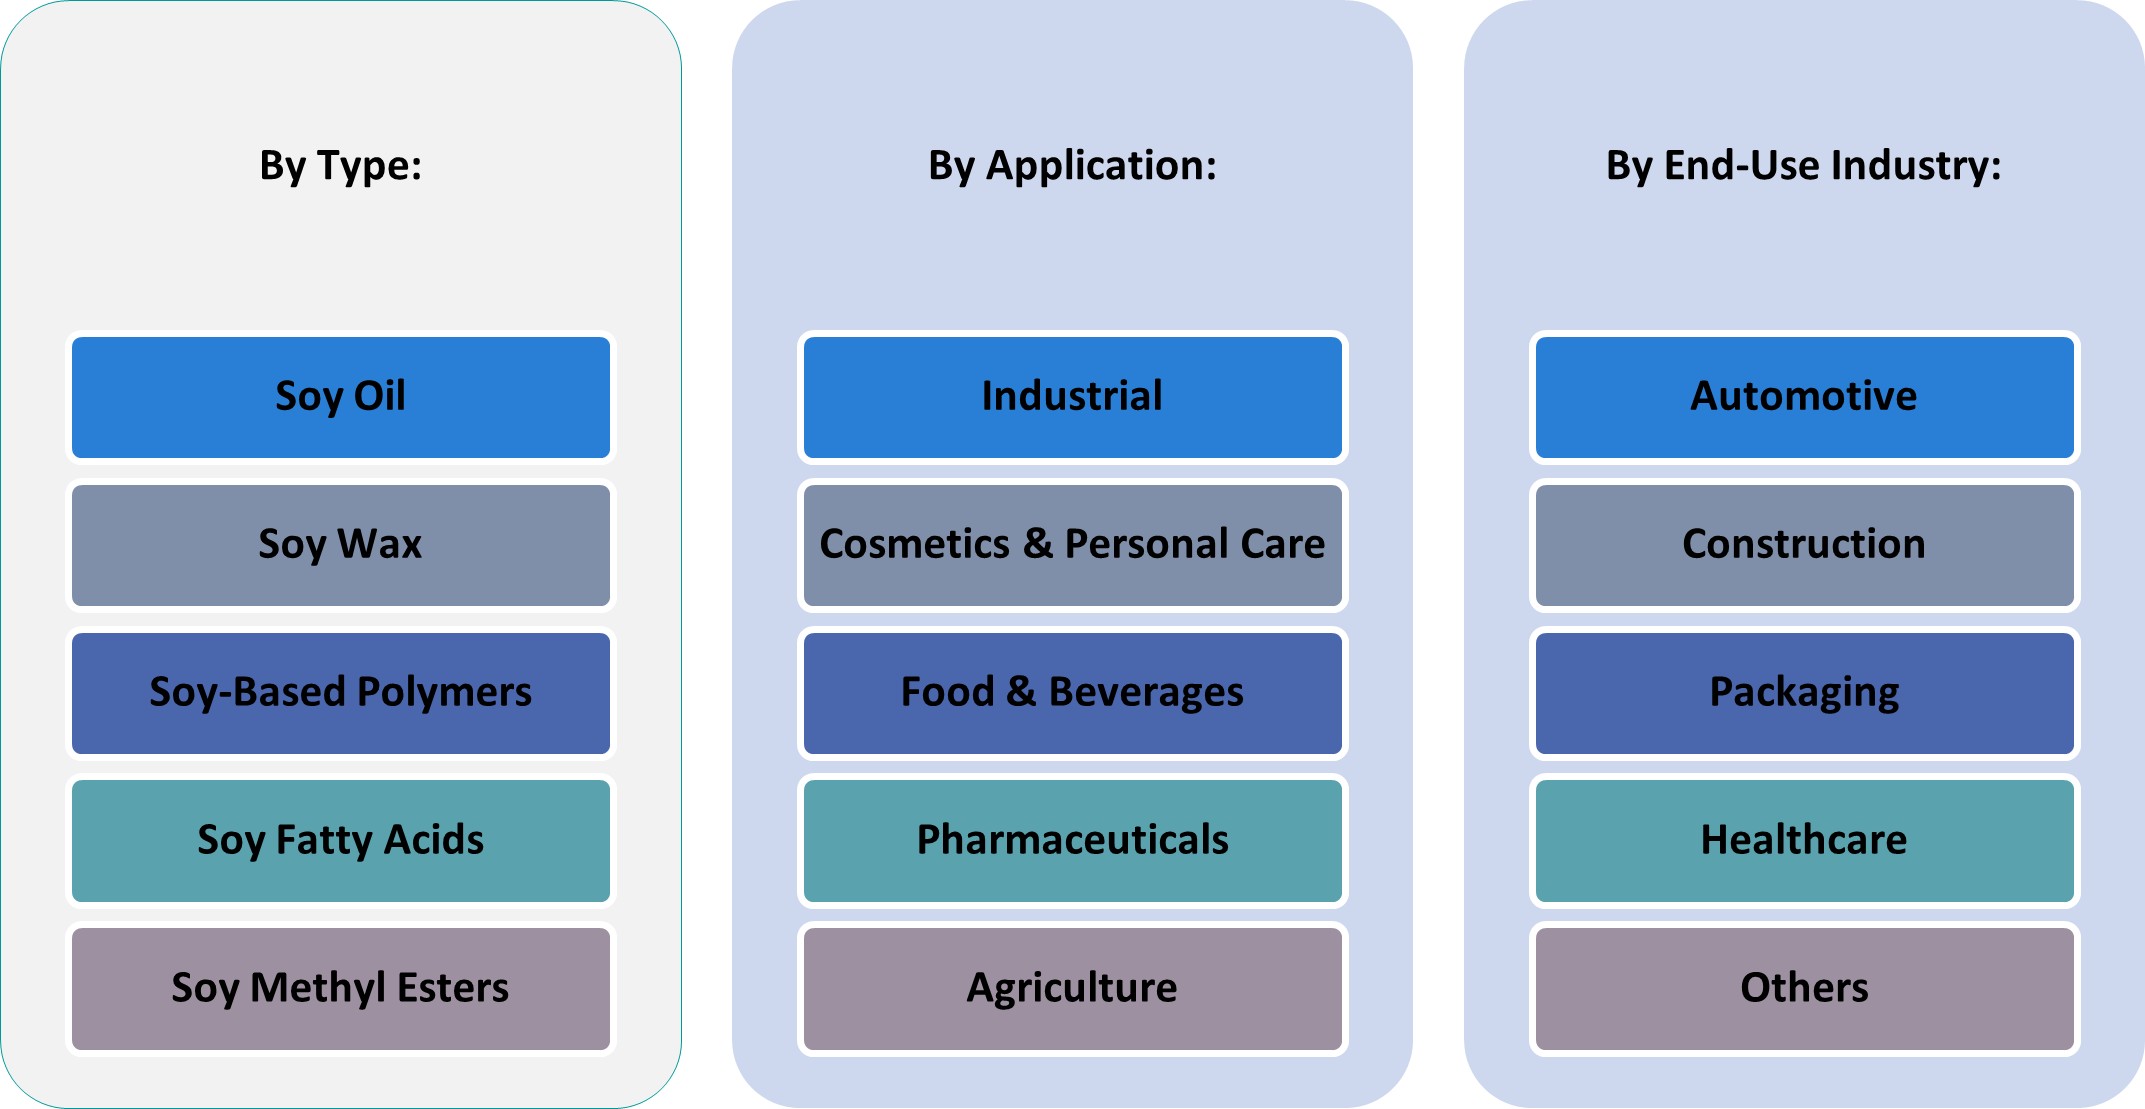
By Type:
Soy oil is a significant segment due to its extensive use in biodiesel production and as a key ingredient in the formulation of chemicals such as surfactants, lubricants, and solvents. Its abundance and renewable nature make it a valuable resource for sustainable chemical production. Soy wax is used primarily in the candle-making industry, offering a more sustainable alternative to paraffin wax. Its popularity is driven by its natural, biodegradable properties and the increasing consumer preference for eco-friendly products. Soy-based polymers are increasingly used in the automotive and packaging industries, providing a renewable alternative to petroleum-based plastics. These polymers help reduce the carbon footprint of manufacturing processes and align with global sustainability trends. Soy fatty acids are used in the production of lubricants, soaps, and cosmetics. These chemicals are derived from soybean oil and offer environmental advantages, including biodegradability and non-toxic properties. Soy methyl esters are mainly used as biodiesel and as a solvent in various industrial applications. Their increasing use in energy production is a key driver of the segment’s growth.
By Application:
Soy-based chemicals play a crucial role in industrial applications, such as the manufacturing of lubricants, coatings, and surfactants. Their use in these industries is driven by the increasing demand for sustainable, bio-based alternatives to conventional chemicals. The growing consumer preference for natural and eco-friendly personal care products has fueled the demand for soy-based ingredients in soaps, lotions, and shampoos. Soy-derived surfactants and oils are particularly popular due to their skin-friendly properties. Soy-based chemicals are widely used in food processing, as emulsifiers, stabilizers, and flavor enhancers. Their role in the food industry is expanding due to the rising demand for plant-based and organic food products. Soy-based chemicals are used in pharmaceutical formulations as excipients, helping in drug delivery and stabilization. Their role in developing bio-based medicines and supplements continues to grow. In agriculture, soy-based chemicals are used in fertilizers, pesticides, and herbicides. They provide an environmentally friendly alternative to synthetic chemicals, contributing to more sustainable farming practices.
Segments
Based on Type
- Soy Oil
- Soy Wax
- Soy-Based Polymers
- Soy Fatty Acids
- Soy Methyl Esters
Based on Application
- Industrial
- Cosmetics & Personal Care
- Food & Beverages
- Pharmaceuticals
- Agriculture
Based on End Use Industry
- Automotive
- Construction
- Packaging
- Healthcare
- Others
Based on Region
- North America
- S.
- Canada
- Mexico
- Europe
- Germany
- France
- K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America (40%)
North America holds the largest share of the global soy-based chemicals market, accounting for approximately 40% of the market. The region's dominance is primarily driven by the extensive availability of soybeans, particularly in the United States, which is one of the largest producers of soybeans globally. Additionally, North America's robust industrial infrastructure and increasing focus on sustainability in manufacturing and production processes further propel the growth of the soy-based chemicals market. Industries such as automotive, packaging, and construction are adopting soy-based chemicals to meet stringent environmental regulations and consumer demands for eco-friendly products. The U.S. Environmental Protection Agency (EPA) and various state-level initiatives promote the use of renewable and biodegradable materials, contributing to the region's market leadership.
Asia-Pacific (30%)
The Asia-Pacific region is experiencing rapid growth in the soy-based chemicals market, accounting for about 30% of the market share. This growth is largely driven by the expanding industrial base in countries like China, India, and Japan, where demand for bio-based chemicals is increasing across sectors such as food and beverages, cosmetics, and agriculture. The rise of the middle class, increased disposable incomes, and greater awareness of sustainable products are driving the adoption of soy-based chemicals. Additionally, government incentives promoting sustainable practices and bio-based alternatives further boost market growth. The region is also a significant consumer of soybeans, contributing to the availability of raw materials for chemical production.
Key players
- Cargill, Incorporated
- Dow Inc.
- BASF SE
- BioBased Technologies LLC
- VertecBio
- Soy Technologies LLC
- Solvay S.A.
- Elevance Renewable Sciences, Inc.
- Renewable Lubricants, Inc
Competitive Analysis
The global soy-based chemicals market is highly competitive, with major players focusing on sustainability, innovation, and technological advancements. Companies like Cargill and Dow Inc. lead the market due to their extensive research and development capabilities, vast distribution networks, and strong market presence across various industrial sectors. BASF SE and Solvay S.A. leverage their expertise in chemical production to enhance the performance of soy-based chemicals, catering to the growing demand for eco-friendly alternatives. Elevance Renewable Sciences differentiates itself through innovative bio-based solutions, particularly in the polymers sector. BioBased Technologies LLC and Soy Technologies LLC focus on specialized applications, offering tailored solutions for agricultural and industrial sectors. VertecBio™ and Renewable Lubricants, Inc. are niche players focusing on sustainable lubricants and bio-based additives, aligning with the increasing emphasis on green chemistry. As competition intensifies, these companies continue to innovate to capture market share in a rapidly evolving industry.
Recent Developments
- On October 7, 2024, Evonik and BASF agreed on the first delivery of biomass-balanced ammonia, achieving a product carbon footprint reduction of over 65%. This collaboration supports Evonik's sustainable product lines like VESTAMIN IPD eCO and VESTAMID eCO.
- On February 26, 2025, Arkema announced a 15% expansion of its polyvinylidene fluoride (PVDF) production capacity at its Calvert City, Kentucky plant. This $20 million investment aims to meet the growing demand for high-performance resins in electric vehicles and energy storage systems.
- On February 25, 2025, AkzoNobel offered to acquire powder coatings assets and the International Research Center from its subsidiary in India. This move is part of the company's strategy to focus more on liquid paints and coatings in the Indian market.
- In February 2025, Perstorp Holding AB began ester production at its Amsterdam plant, marking a significant step in expanding its product offerings in the sustainable chemicals sector.
Market Concentration and Characteristics
The global soy-based chemicals market exhibits a moderate level of concentration, with key players such as Cargill, Dow Inc., and BASF SE holding significant market shares due to their established production capabilities, extensive research and development resources, and broad distribution networks. While a few large multinational corporations dominate the market, there is also a growing presence of specialized companies like BioBased Technologies LLC and Renewable Lubricants, Inc., which focus on niche applications. The market is characterized by strong competition driven by technological innovation, sustainability goals, and increasing consumer demand for eco-friendly products. As the demand for bio-based chemicals continues to rise, companies are increasingly investing in research to enhance the performance and cost-effectiveness of soy-based alternatives, creating a dynamic and rapidly evolving market environment.
Report Coverage
The research report offers an in-depth analysis based on Type, Application, End Use Industry and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- As environmental concerns grow, the demand for soy-based chemicals will increase, driven by their renewable and biodegradable nature. Companies are investing in
- Ongoing advancements in biotechnology and chemical engineering will improve the efficiency and cost-effectiveness of soy-based chemicals. Innovations in production processes will drive market competitiveness.
- Soy-based chemicals will see expanded applications in industries such as automotive, packaging, and agriculture. The versatility of soy chemicals will continue to fuel their adoption across diverse sectors.
- The market for soy-based polymers and bioplastics will continue to grow as consumers and industries shift towards eco-friendly alternatives to petroleum-based plastics.
- Governments worldwide will increase support for bio-based products through subsidies, incentives, and favorable regulations, providing a conducive environment for the growth of soy-based chemicals.
- The demand for soy-based ingredients in cosmetics, personal care, and food products will rise, reflecting consumer preferences for natural and non-toxic alternatives.
- The Asia-Pacific region will play a crucial role in the market's growth, with rapidly industrializing nations like China and India adopting soy-based chemicals for various applications.
- Companies will enhance supply chain resilience by localizing production facilities, reducing transportation costs, and ensuring a steady supply of raw materials, supporting market growth.
- The shift towards a circular economy will promote the recycling and reuse of soy-based products, creating new opportunities for sustainable chemical production and reducing waste.
- The soy-based chemicals market will witness increased competition, with both large corporations and smaller, innovative firms striving to meet growing demand and differentiate themselves through technological advancements.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Demand for Sustainable and Renewable Alternatives
The shift towards sustainability is driving industries to adopt soy-based chemicals as eco-friendly alternatives to petroleum-based chemicals. Their renewable and biodegradable nature aligns with environmental goals and regulatory requirements, fueling adoption across sectors such as biodiesel, plastics, and personal care.
Technological Advancements in Soy Processing
Innovations in biotechnology and chemical engineering have improved the efficiency, yield, and purity of soy-based chemicals, making them more competitive with petrochemical counterparts. Enhanced production processes lower costs and expand the range of viable applications.
Supportive Government Policies and Incentives
Governments worldwide are implementing policies and offering incentives to promote bio-based chemicals, reducing reliance on fossil fuels and encouraging sustainable practices. These measures create a favorable regulatory environment and stimulate market growth.
Expanding Applications Across Diverse Industries
Soy-based chemicals are increasingly used in automotive, packaging, agriculture, and healthcare due to their versatility and performance. Their adoption is further propelled by consumer demand for natural, non-toxic, and biodegradable products.
Regionalization and Supply Chain Optimization
Companies are localizing production and sourcing to reduce transportation costs, mitigate supply chain disruptions, and comply with local sustainability regulations. This trend enhances supply chain resilience and supports market expansion, especially in rapidly growing regions like Asia-Pacific.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the global soy-based chemicals market in 2023 and 2032?
What are the key drivers of the global soy-based chemicals market?
What industries are adopting soy-based chemicals?
Who are the major players in the soy-based chemicals market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Soy Oil
- 1.2.2 Soy Wax
- 1.2.3 Soy-Based Polymers
- 1.2.4 Soy Fatty Acids
- 1.2.5 Soy Methyl Esters
- 1.3 By Application
- 1.3.1 Industrial
- 1.3.2 Cosmetics & Personal Care
- 1.3.3 Food & Beverages
- 1.3.4 Pharmaceuticals
- 1.3.5 Agriculture
- 1.4 By End Use Industry
- 1.4.1 Automotive
- 1.4.2 Construction
- 1.4.3 Packaging
- 1.4.4 Healthcare
- 1.4.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 28,996.80 million → 2032: USD 52,069.72 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Soy-Based Chemicals Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Soy-Based Chemicals Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Soy-Based Chemicals Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Soy-Based Chemicals Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Soy-Based Chemicals Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Soy-Based Chemicals Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Soy-Based Chemicals Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Soy-Based Chemicals Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 28,996.80 million → 2032: USD 52,069.72 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Soy-Based Chemicals Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Soy Oil
- 12.3.7.2 Soy Wax
- 12.3.7.3 Soy-Based Polymers
- 12.3.7.4 Soy Fatty Acids
- 12.3.7.5 Soy Methyl Esters
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Industrial
- 12.4.7.2 Cosmetics & Personal Care
- 12.4.7.3 Food & Beverages
- 12.4.7.4 Pharmaceuticals
- 12.4.7.5 Agriculture
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End Use Industry - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Automotive
- 12.5.7.2 Construction
- 12.5.7.3 Packaging
- 12.5.7.4 Healthcare
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Soy-Based Chemicals End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Soy-Based Chemicals Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Soy-Based Chemicals Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Soy-Based Chemicals Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Cargill, Incorporated
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Dow Inc.
- 18.4 BASF SE
- 18.5 BioBased Technologies LLC
- 18.6 VertecBio
- 18.7 Soy Technologies LLC
- 18.8 Solvay S.A.
- 18.9 Elevance Renewable Sciences, Inc.
- 18.10 Renewable Lubricants, Inc.
- 18.11 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

