
Market Overview
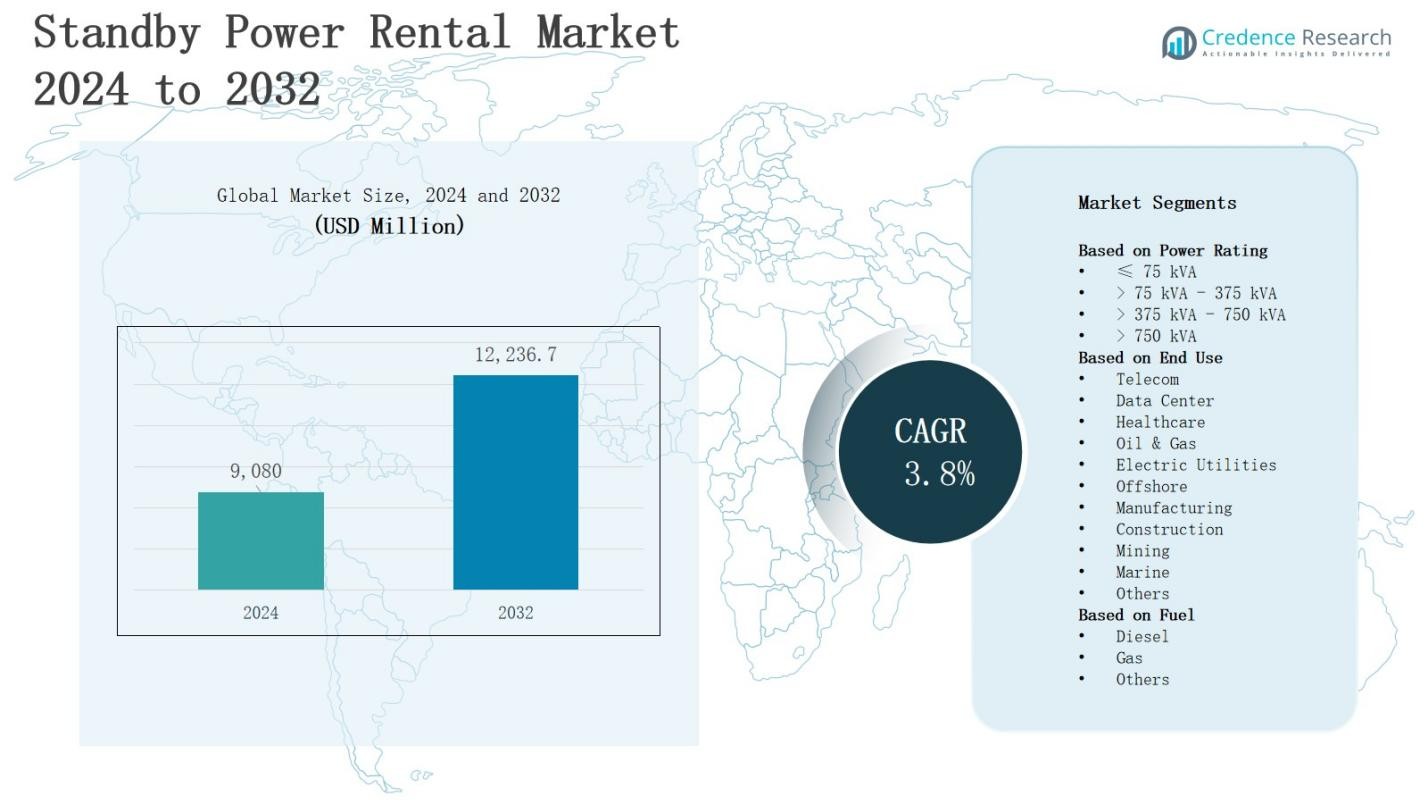
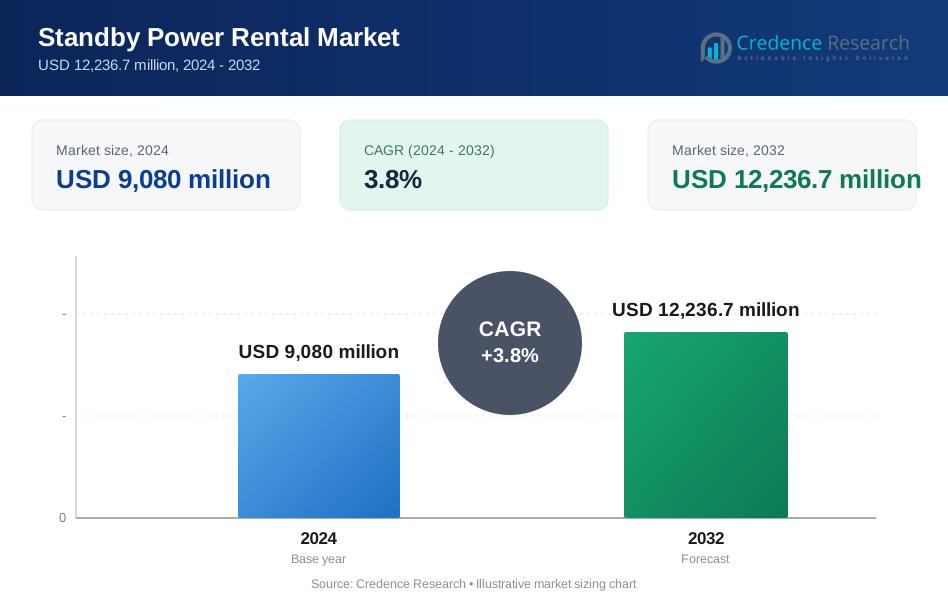
The standby power rental market is projected to grow from USD 9,080 million in 2024 to USD 12,236.7 million by 2032, registering a CAGR of 3.8% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Standby Power Rental Market Size 2024 | USD 9,080 Million |
| Standby Power Rental Market, CAGR | 3.8% |
| Standby Power Rental Market Size 2032 | USD 12,236.7 Million |
The standby power rental market grows with increasing demand for reliable backup power during grid outages, construction projects, and large-scale events. Stricter regulations on power reliability and rising frequency of natural disasters drive adoption across industries, while businesses seek flexible and cost-effective alternatives to permanent installations. The market benefits from growing industrialization in emerging economies, where infrastructure gaps boost rental demand. Key trends include the integration of hybrid and renewable-powered rental systems, adoption of digital monitoring for real-time efficiency, and a shift toward eco-friendly, fuel-efficient generators that align with sustainability goals and corporate carbon reduction strategies.
The standby power rental market shows diverse geographical presence across North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa, each contributing to overall growth with distinct demand drivers such as data centers, construction, mining, and oil and gas. North America and Asia Pacific lead with strong adoption, while Europe emphasizes sustainable solutions, and Latin America and the Middle East & Africa witness rising infrastructure demand. Key players include Aggreko, Atlas Copco, Caterpillar, Cummins, HIMOINSA, Finning International, Herc Rentals, Bredenoord, Al Faris, Rehlko, Modern Hiring Service, and BPC Power Rentals.
Market Insights
- The standby power rental market is projected to grow from USD 9,080 million in 2024 to USD 12,236.7 million by 2032, registering a CAGR of 3.8%.
- Rising demand for reliable backup power in healthcare, data centers, construction, and large-scale events drives consistent adoption.
- Cost-effectiveness and operational flexibility of rental systems attract businesses seeking short-term or scalable solutions without heavy capital investment.
- Rapid industrialization in Asia Pacific, Latin America, and Africa boosts demand where grid reliability remains limited.
- High operating costs and dependence on fuel prices pose challenges, while stricter emission regulations push providers toward eco-friendly alternatives.
- North America holds 32% share, Europe 24%, Asia Pacific 28%, Latin America 9%, and the Middle East & Africa 7%, each shaped by unique demand drivers.
- Key players include Aggreko, Atlas Copco, Caterpillar, Cummins, HIMOINSA, Finning International, Herc Rentals, Bredenoord, Al Faris, Rehlko, Modern Hiring Service, and BPC Power Rentals.
Market Drivers
Rising Need for Uninterrupted Power Supply in Critical Applications The standby power rental market expands with growing dependence on reliable electricity in healthcare, data centers, and commercial facilities. Hospitals require immediate backup to maintain life-support systems, while data centers depend on uninterrupted power to safeguard operations. It supports large-scale events, construction sites, and emergency response activities. Increasing power outages from natural disasters and grid instability encourage organizations to rent reliable systems. This demand creates consistent opportunities for rental providers across sectors.
- For instance, Aggreko deployed 292 diesel generators totaling 270 MW across Argentina, rapidly providing emergency power amid unstable grid conditions.
Cost-Effectiveness and Operational Flexibility of Rental Solutions Organizations adopt rental systems for short-term or seasonal power needs, reducing capital investment in permanent infrastructure. The standby power rental market benefits companies seeking operational flexibility to match varying demand. It provides a scalable solution where users pay only for duration of use, minimizing long-term maintenance costs. Businesses leverage rental services to respond quickly to unexpected outages. This cost advantage drives preference for rentals in both developed and emerging economies.
- For instances, Murari Power Solutions uses IoT monitoring to enhance generator uptime and reduce maintenance costs, speeding issue detection from 24 hours to 1 hour.
Industrialization and Infrastructure Development in Emerging Markets Rapid industrialization and urbanization in developing regions generate substantial demand for backup power. The standby power rental market supports construction projects, manufacturing plants, and expanding commercial spaces requiring reliable power during infrastructure growth. It serves as a bridge where local grids remain underdeveloped or unstable. Industrial expansion across Asia Pacific, Latin America, and Africa fuels steady growth. The presence of multinational rental companies accelerates adoption by offering standardized, high-capacity systems.
Technological Advancements and Sustainable Power Alternatives The market benefits from technological integration, including remote monitoring, load optimization, and hybrid systems that combine renewable and conventional energy sources. The standby power rental market aligns with corporate sustainability goals by promoting fuel-efficient, low-emission generators. It supports industries adapting to stricter environmental regulations. Rental providers enhance offerings with digital platforms for predictive maintenance and operational insights. This innovation attracts environmentally conscious clients, positioning rentals as sustainable, modern solutions for future power security.
Market Trends
Growing Integration of Hybrid and Renewable Energy Sources The standby power rental market evolves with a noticeable shift toward hybrid systems that combine diesel or gas generators with renewable energy solutions. Companies deploy solar and battery-backed systems to reduce fuel dependency and carbon emissions. It reflects global sustainability priorities and supports compliance with stricter emission regulations. Businesses prefer hybrid rentals for efficiency, reliability, and reduced operating costs. This transition reshapes the rental landscape, making clean energy integration a core trend.
- For instance, Tata Power has also expanded its hybrid portfolio by integrating solar and wind power with battery systems, improving both energy reliability and reducing costs.
Expansion of Digital Monitoring and Smart Control Systems The market witnesses rapid adoption of digital technologies that enable predictive maintenance and real-time performance monitoring. The standby power rental market benefits from IoT-enabled platforms, which improve load management and optimize fuel usage. It enhances reliability by providing operators with instant alerts on potential failures. Remote access to generator data increases operational transparency and client satisfaction. These smart solutions improve efficiency while strengthening trust between rental providers and customers.
Rising Demand from Large-Scale Infrastructure and Event Projects Infrastructure development, mining operations, and large-scale public events drive rising demand for temporary power solutions. The standby power rental market supports contractors and event organizers by delivering scalable and mobile units capable of meeting fluctuating load requirements. It plays a vital role in mega sporting events, concerts, and exhibitions. Growing government investments in infrastructure projects worldwide further accelerate adoption. The trend highlights the flexibility and resilience of rental systems in dynamic environments.
- For instance, during the construction of a large housing development, POWRBANK MAX battery energy storage systems provided quiet, off-grid power to site operations and homes awaiting grid connection, minimizing emissions and noise.
Shift Toward Eco-Friendly and Low-Emission Equipment Environmental concerns and regulatory frameworks push the market toward adopting fuel-efficient, low-emission rental equipment. The standby power rental market aligns with corporate green initiatives and global climate commitments. It introduces advanced generators with reduced noise and improved efficiency. Rental providers differentiate themselves by offering sustainable alternatives to conventional models. Clients increasingly prioritize eco-friendly equipment to enhance brand reputation while meeting compliance standards. This shift redefines competitive strategies and long-term growth opportunities.
Market Challenges Analysis
High Operating Costs and Dependency on Fuel Prices The standby power rental market faces pressure from rising fuel prices and high operating costs, which limit affordability for small and medium-scale users. It depends heavily on diesel and gas generators, making cost fluctuations a recurring challenge. Clients often face budgetary constraints when fuel expenses surge, reducing rental demand. Maintenance, logistics, and transportation of large equipment add to the cost burden. This issue forces providers to balance competitive pricing with profitability while managing client expectations.
Stringent Environmental Regulations and Emission Concerns Tightening global regulations on emissions create compliance challenges for rental providers. The standby power rental market relies on generators that produce greenhouse gases, which often conflict with sustainability goals and legal requirements. It compels companies to invest in advanced, eco-friendly systems, increasing initial costs and reducing short-term margins. Smaller providers struggle to keep pace with regulatory shifts. Growing environmental awareness among customers further intensifies the need for greener solutions, reshaping competition across the industry.
Market Opportunities
Rising Adoption of Sustainable and Hybrid Power Solutions The standby power rental market presents significant opportunities through the integration of renewable energy and hybrid solutions. It allows businesses to align with global sustainability targets while lowering operating costs. Hybrid systems that combine solar, battery storage, and fuel-efficient generators attract industries seeking greener alternatives. Governments encourage clean energy adoption with favorable policies, creating a supportive environment for innovation. Rental providers that invest in eco-friendly fleets gain a competitive advantage and strengthen customer loyalty.
Expanding Demand Across Emerging Economies and Infrastructure Projects Rapid industrialization and infrastructure development in emerging markets create strong opportunities for rental providers. The standby power rental market supports construction sites, mining projects, and expanding urban infrastructure where grid stability remains limited. It benefits from rising demand in Asia Pacific, Africa, and Latin America, where governments prioritize large-scale projects. Growth in data centers and telecom networks further fuels long-term opportunities. Providers offering scalable, reliable, and cost-effective rental solutions capture growing market share.
Market Segmentation Analysis:
By Power Rating
The standby power rental market segments by power rating into ≤75 kVA, >75 kVA–375 kVA, >375 kVA–750 kVA, and >750 kVA units. It serves diverse applications ranging from small-scale commercial needs to large industrial operations. Low-capacity units find use in telecom and small businesses, while medium ranges dominate construction and utilities. High-capacity systems above 750 kVA cater to data centers, oil and gas, and mining operations, supporting critical functions that demand continuous large-scale backup power.
- For instance, for high-capacity systems >750 kVA, Aggreko deployed multiple 2.5 MW diesel generators at a Silicon Valley data center, supporting critical IT infrastructure with continuous backup during grid outages.
By End Use
End-use segmentation highlights telecom, data centers, healthcare, oil and gas, electric utilities, offshore, manufacturing, construction, mining, marine, and others. The standby power rental market supports telecom and data centers with consistent demand for uninterrupted connectivity and operations. It addresses healthcare facilities where reliability ensures patient safety. Oil and gas, utilities, and offshore industries rely on high-power systems, while construction and mining require scalable solutions. Manufacturing and marine sectors further strengthen rental adoption for operational resilience.
- For instance, Caterpillar provided mobile power rental units for mining operations in Western Australia, enabling 24/7 operations in remote sites where no permanent grid exists.
By Fuel
Fuel-based segmentation includes diesel, gas, and others. Diesel dominates the standby power rental market due to reliability, availability, and suitability for high-load applications. It remains the primary choice for industries requiring instant and durable backup solutions. Gas-powered rentals grow with rising sustainability concerns and regulatory support for cleaner energy alternatives. Other fuels, including hybrid systems, attract interest as companies explore eco-friendly and cost-effective solutions to meet both environmental and operational requirements.
Segments:
Based on Power Rating
- ≤ 75 kVA
- > 75 kVA - 375 kVA
- > 375 kVA - 750 kVA
- > 750 kVA
Based on End Use
- Telecom
- Data Center
- Healthcare
- Oil & Gas
- Electric Utilities
- Offshore
- Manufacturing
- Construction
- Mining
- Marine
- Others
Based on Fuel
- Diesel
- Gas
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds 32% share of the standby power rental market, supported by strong demand from data centers, healthcare, and commercial sectors. It benefits from frequent weather-related outages and an aging grid that drives reliance on rental systems. Oil and gas operations in the United States also generate consistent demand. The region adopts advanced hybrid and low-emission generators in line with sustainability regulations. It remains a mature market where innovation and service quality drive competition.
Europe
Europe accounts for 24% share of the standby power rental market, influenced by strict environmental standards and a focus on green energy adoption. It benefits from demand across healthcare, utilities, and large-scale events requiring reliable backup power. Data center expansion across Germany, the UK, and Nordic countries strengthens the market. Rental providers invest in low-noise and fuel-efficient systems to meet local regulations. It positions itself as a sustainability-driven region with steady long-term growth.
Asia Pacific
Asia Pacific leads with 28% share of the standby power rental market, driven by rapid industrialization, urbanization, and infrastructure projects. It serves construction, telecom, and mining sectors where grid reliability remains limited. Countries like China, India, and Southeast Asian nations adopt rental solutions to manage peak demand and outages. Growth in manufacturing hubs and large commercial facilities accelerates adoption. It remains the fastest-growing region with strong opportunities for global and local rental providers.
Latin America
Latin America represents 9% share of the standby power rental market, supported by infrastructure development and expanding energy projects. It serves construction and mining sectors in Brazil, Chile, and Mexico where temporary power is vital. Frequent blackouts and regional grid instability also increase rental demand. The healthcare and telecom industries contribute to steady growth. It shows rising adoption of diesel and hybrid systems, positioning the region as a developing but promising market.
Middle East & Africa
The Middle East & Africa holds 7% share of the standby power rental market, supported by oil and gas, utilities, and construction industries. It addresses the need for reliable backup in areas with limited grid access. The UAE, Saudi Arabia, and South Africa emerge as key demand centers. Data center growth and large infrastructure projects strengthen adoption. It depends on diesel-based rentals but shows gradual interest in gas and hybrid solutions.
Key Player Analysis
- Rehlko
- BPC Power Rentals
- Aggreko
- Finning International
- Al Faris
- Modern Hiring Service
- HIMOINSA
- Caterpillar
- Herc Rentals
- Bredenoord
- Cummins
- Atlas Copco
Competitive Analysis
The standby power rental market demonstrates strong competition with global and regional players focusing on reliability, technological advancements, and service efficiency. It is characterized by the presence of established companies such as Aggreko, Atlas Copco, Caterpillar, Cummins, and HIMOINSA, which dominate through extensive fleets, global networks, and integrated digital solutions. Players like Finning International, Herc Rentals, and Bredenoord strengthen their positions by targeting diverse industries including construction, data centers, and oil and gas with scalable rental offerings. Regional companies such as Al Faris, Rehlko, and Modern Hiring Service enhance market diversity by providing localized expertise, competitive pricing, and customer-centric solutions. BPC Power Rentals builds market presence through tailored offerings across sectors requiring short-term and emergency backup power. Competition centers on expanding hybrid and sustainable rental solutions, integrating IoT-enabled monitoring, and offering flexible contracts to capture evolving customer preferences. It remains a fragmented but growth-driven sector where providers differentiate through innovation, energy efficiency, and customized services aligned with global sustainability and reliability demands.
Recent Developments
- On April 28, 2025, Worldwide Power Products launched an affiliate company called Worldwide Power Distribution (WPD). This expansion focuses on power distribution equipment rentals across the United States, offering equipment such as transformers, distribution panels, automatic transfer switches, and motor starters.
- In February 2025, Sandbrook Capital acquired Intellirent from Electro Rent. This acquisition focuses on electrical-test equipment rentals that support power grid modernization, aligning with growing infrastructure renewal needs.
- In August 2025, Aggreko launched a 400 kW Tier 4 Final Diesel Generator in North America, expanding its cleaner “Greener Upgrades” portfolio.
- In February 2025, Cummins acquired First Mode’s assets, advancing hybrid and hydrogen retrofit solutions for mining and rail, with pilot deployment planned in Chile.
Market Concentration & Characteristics
The standby power rental market displays a moderately fragmented structure with the presence of both global leaders and regional providers competing across diverse industries. It is defined by a balance between large multinational companies such as Aggreko, Caterpillar, Cummins, and Atlas Copco that leverage scale, advanced technology, and global networks, and smaller regional firms that compete through localized expertise, cost-effective offerings, and flexible contracts. The market emphasizes service quality, fuel efficiency, and rapid deployment capabilities as key differentiators. It evolves with growing emphasis on hybrid and renewable-powered systems, digital monitoring, and compliance with stricter emission standards. Competitive intensity remains high, driven by the need to provide scalable solutions for critical applications including data centers, healthcare, oil and gas, and construction. The standby power rental market demonstrates resilience through its ability to adapt to fluctuating fuel prices, regulatory pressures, and customer preferences while maintaining steady demand across mature and emerging economies.
Report Coverage
The research report offers an in-depth analysis based on Power Rating, End-Use, Fuel and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for standby power rentals will rise with increasing grid instability and frequent weather-related outages.
- Adoption of hybrid systems combining diesel, gas, and renewable energy will expand across industries.
- Digital monitoring and IoT-enabled platforms will become standard features for improving efficiency and reliability.
- Data centers and telecom networks will remain major growth drivers due to rising connectivity needs.
- Healthcare facilities will increasingly depend on rental systems to ensure uninterrupted patient care.
- Construction and mining projects in emerging economies will generate steady demand for scalable power solutions.
- Providers will focus on developing eco-friendly and fuel-efficient generators to meet environmental regulations.
- Regional players will strengthen market presence through competitive pricing and customized services.
- Strategic partnerships and fleet expansions will define competition among leading global companies.
- The market will evolve toward sustainability, flexibility, and advanced technology integration to meet diverse industry requirements.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for standby power rental market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the standby power rental market projected to grow between 2025 and 2032?
Which standby power rental market segment held the largest share in 2024?
What are the primary factors fueling the growth of the standby power rental market?
Who are the leading companies in the standby power rental market?
Which region commanded the largest share of the standby power rental market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Standby Power Rental Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Standby Power Rental Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 9,080 million → 2032: USD 12,236.7 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Standby Power Rental Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Standby Power Rental Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Standby Power Rental Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Standby Power Rental Market Drivers
- 3.3 Standby Power Rental Market Restraints & Challenges
- 3.4 Standby Power Rental Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Standby Power Rental Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Standby Power Rental Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Standby Power Rental category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Standby Power Rental Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Standby Power Rental Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Standby Power Rental market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Standby Power Rental Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Standby Power Rental Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Standby Power Rental Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Standby Power Rental (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Standby Power Rental Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Standby Power Rental Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Standby Power Rental Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Standby Power Rental Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Standby Power Rental Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Standby Power Rental Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Standby Power Rental Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Standby Power Rental Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Standby Power Rental Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
