
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Synthetic Lubricants Market Size 2024 | USD 32,324.9 Million |
| Synthetic Lubricants Market, CAGR | 3.19% |
| Synthetic Lubricants Market Size 2032 | USD 41,665.4 Million |
Market Overview:
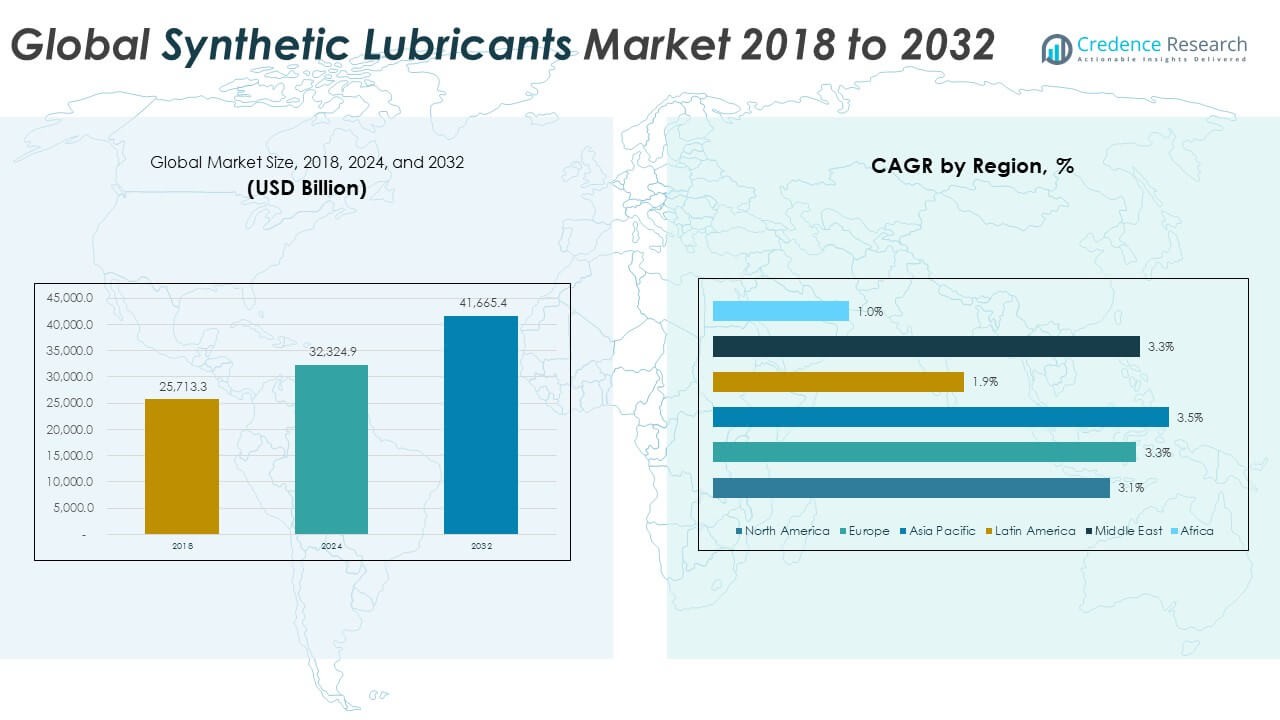
The Synthetic Lubricants Market size was valued at USD 25,713.3 million in 2018 to USD 32,324.9 million in 2024 and is anticipated to reach USD 41,665.4 million by 2032, at a CAGR of 3.19% during the forecast period.
The synthetic lubricants market is primarily driven by the growing demand for high-performance and long-lasting lubricants across automotive, industrial, and aerospace sectors. These lubricants offer superior thermal stability, oxidation resistance, and extended drain intervals, reducing maintenance costs and equipment downtime. The automotive industry's transition toward fuel-efficient engines and electric vehicles (EVs) is further accelerating market growth, as synthetic fluids play a vital role in managing high temperatures and ensuring energy efficiency. In addition, stringent environmental regulations regarding emissions and waste disposal are encouraging industries to shift from conventional to synthetic and bio-based lubricants. Rising awareness of sustainability and lifecycle cost savings continues to influence adoption trends across both developed and emerging economies.
Asia-Pacific dominates the global synthetic lubricants market, driven by rapid industrialization, rising vehicle ownership, and robust manufacturing activity in countries like China and India. North America is the fastest-growing region, supported by a strong automotive industry, advanced EV adoption, and stringent environmental policies. Europe holds a substantial share due to regulatory emphasis on cleaner technologies and high-performance automotive applications. Meanwhile, Latin America and the Middle East & Africa are gradually expanding their presence, with growing infrastructure projects and oil & gas activities contributing to demand. Technological advancements and investments in industrial automation are further boosting synthetic lubricant usage across developing nations. Additionally, rising demand for premium lubricants in commercial fleets and OEM recommendations for synthetic oils are shaping regional consumption patterns.
Market Insights:
- The Synthetic Lubricants Market reached USD 32,324.9 million in 2024 and is projected to grow to USD 41,665.4 million by 2032, registering a CAGR of 3.19%.
- The market is driven by increasing demand across automotive, aerospace, and industrial sectors due to the need for high-performance lubricants with superior thermal and oxidative stability.
- Rising electric vehicle adoption is creating demand for specialized synthetic fluids for battery cooling, e-axle lubrication, and thermal management systems.
- Regulatory pressure to reduce emissions is pushing industries to switch from mineral-based to synthetic and bio-based lubricants that support longer drain intervals and lower carbon footprints.
- Asia-Pacific holds the largest market share, led by industrial growth in China and India, while North America is the fastest-growing region due to its advanced EV and automotive landscape.
- Despite strong demand, high production costs and premium pricing remain key challenges, especially in cost-sensitive and emerging markets.
- Lack of product awareness and limited infrastructure in developing regions continues to hinder wider market penetration and adoption of synthetic lubricants.
Market Drivers:
Superior Performance Characteristics Fuel Market Preference
Synthetic lubricants are engineered to outperform conventional mineral-based oils across a wide range of operating conditions. Their enhanced thermal stability, oxidation resistance, and low-temperature fluidity allow for superior equipment protection and efficiency. These properties are essential in sectors such as automotive, manufacturing, and aerospace, where machinery operates under extreme pressures and temperatures. The Synthetic Lubricants Market benefits from the rising need for high-performance fluids that extend oil drain intervals and reduce overall maintenance costs. It is also gaining traction in sectors demanding low volatility and improved lubrication under harsh conditions. These technical advantages make synthetic lubricants the preferred choice for critical applications, contributing to their sustained demand.
- For example, Mobil SHC™ 524 synthetic hydraulic oil demonstrated a 700% increase in oil drain intervals extending from 4,000 hours to 32,000 hours in Italian steel mill bridge cranes operating at temperatures up to 120°C, drastically reducing unscheduled outages and maintenance costs.
Automotive Sector Modernization Drives Product Adoption
The automotive industry plays a pivotal role in expanding the market for synthetic lubricants, with the shift toward fuel-efficient and high-performance engines driving product adoption. OEMs increasingly recommend synthetic oils to comply with regulatory standards and achieve engine efficiency targets. The market is also influenced by the rising popularity of turbocharged engines, which require high-temperature stability that only synthetic lubricants can provide. The Synthetic Lubricants Market responds to these evolving requirements by offering formulations that reduce friction, enhance engine cleanliness, and support fuel economy. It aligns with the global trend of vehicle downsizing, where thermal stress and lubrication precision are critical. This alignment strengthens its position across both passenger and commercial vehicle segments.
Electric Vehicle Growth Encourages Specialized Lubricant Demand
The growing adoption of electric vehicles (EVs) introduces new demands for thermal management, gear lubrication, and dielectric fluid solutions. Synthetic lubricants meet these emerging challenges with tailored formulations that ensure durability and energy efficiency in EV components. These fluids help manage heat in battery systems, reduce wear in e-axles, and provide insulation in electric drivetrains. The Synthetic Lubricants Market is evolving to meet these needs, with manufacturers focusing on developing specialized products that suit next-generation mobility platforms. It benefits from increased R&D investments aimed at producing low-viscosity and environmentally safe lubricants for the EV sector. The rise in EV production worldwide directly supports the diversification and expansion of synthetic lubricant applications.
Environmental Regulations and Sustainability Accelerate Market Shift
Governments and regulatory bodies are enforcing stricter emission standards and sustainability mandates across industrial and transportation sectors. These policies are prompting a transition from traditional lubricants to synthetic alternatives with lower environmental impact. Synthetic lubricants contribute to reduced carbon emissions through improved engine efficiency and extended service intervals. The Synthetic Lubricants Market capitalizes on these trends by offering products that comply with global environmental standards such as Euro 6, API SN Plus, and ILSAC GF-6. It is also benefiting from growing awareness among end-users about lifecycle cost savings and ecological responsibility. Corporate sustainability goals across multiple industries are further reinforcing the shift toward synthetic formulations.
- For instance, Environmentally Acceptable Lubricants (EALs) now achieve biodegradation rates of 60–95%, significantly surpassing the 30–65% range typical of conventional mineral oils, and re-refining processes can reduce cradle-to-gate CO₂ equivalent emissions by 60–80% compared to crude-derived base oils.
Market Trends:
Expansion of Electric and Hybrid Vehicle Market Spurs Demand for Specialized Lubricants
The accelerating transition toward electric and hybrid vehicles is driving the need for advanced synthetic lubricants. These vehicles require specialized fluids for thermal management, drivetrain protection, and electrical insulation. Synthetic lubricants are tailored to address these performance demands, including low viscosity, oxidation stability, and high dielectric strength. The Synthetic Lubricants Market is aligning its innovation efforts with the evolving EV ecosystem, focusing on formulations for e-axles, battery cooling systems, and electric gearboxes. It is also seeing increased interest from OEMs that are integrating custom fluid specifications into vehicle designs. This trend is expected to grow in tandem with rising EV production and government policies promoting clean transportation.
- For example, Lubrizol’s EVOGEN™ TM1000 Series battery thermal management fluids are engineered specifically for EV immersion cooling, offering kinematic viscosities as low as 1.3 cSt at 40°C and dielectric strengths up to 80 kV, which are critical for preventing battery thermal runaway and enabling ultra-fast charging cycles.
Focus on Sustainability and Eco-Friendly Formulations Gains Momentum
Environmental awareness is prompting lubricant manufacturers to develop eco-compatible formulations with minimal ecological footprint. Bio-based synthetics, low-toxicity additives, and extended-life lubricants are gaining traction across end-use sectors. The market is witnessing a shift in consumer and industrial preferences toward products that support carbon reduction goals and comply with environmental certifications. The Synthetic Lubricants Market is responding with greener alternatives that offer both high performance and environmental compliance. It is also benefitting from corporate ESG initiatives and sustainability mandates that prioritize reduced emissions and waste. This green transformation is becoming a defining characteristic of future product development.
Adoption of Smart Maintenance Practices Enhances Lubricant Value Proposition
Industrial users are increasingly implementing predictive maintenance technologies to optimize equipment performance and reduce downtime. Smart monitoring systems and condition-based alerts rely on high-quality lubricants that remain stable over longer cycles. Synthetic lubricants support these initiatives with consistent performance across extended intervals and under variable load conditions. The Synthetic Lubricants Market is tapping into this trend by promoting lubricants compatible with digital diagnostics and IoT-enabled systems. It is also leveraging data-driven solutions to demonstrate cost savings and lifecycle advantages to industrial clients. The rise of Industry 4.0 is reinforcing this movement, making lubricant performance a strategic maintenance asset.
Rising Demand from High-Performance Industrial Applications Strengthens Market Base
Sectors such as aerospace, marine, energy, and heavy manufacturing continue to require lubricants that can withstand extreme pressures, high temperatures, and chemically aggressive environments. Synthetic lubricants offer the durability and reliability needed in these conditions, making them the preferred choice over conventional oils. The Synthetic Lubricants Market is benefiting from infrastructure expansion, aerospace advancements, and increased offshore drilling activity. It is also experiencing higher demand from precision equipment manufacturers that prioritize friction reduction and long-term operational stability. The need for lubricant solutions tailored to specialized equipment is driving product innovation and portfolio diversification. This trend underlines the market’s growing importance in mission-critical operations.
- Krytox perfluoropolyether (PFPE) lubricants, for instance, maintain performance at temperatures exceeding 400°C and under extreme pressures, as demonstrated by a British bottling plant extending gearbox change intervals from two weeks to two years, and a German EGR valve manufacturer saving nearly $90,000 annually by switching to PFPEs.
Market Challenges Analysis:
High Production Costs and Price Sensitivity Limit Widespread Adoption
The complex formulation and processing requirements of synthetic lubricants contribute to significantly higher production costs compared to conventional mineral oils. These elevated costs often translate into premium pricing, which can deter adoption in cost-sensitive markets and among price-conscious consumers. The automotive aftermarket, small-scale industrial users, and developing economies may prefer cheaper alternatives despite the long-term advantages of synthetics. The Synthetic Lubricants Market faces the challenge of balancing product quality with affordability to broaden its user base. It must also address market reluctance through targeted education on lifecycle savings and performance benefits. Competitive pricing from conventional lubricant producers continues to pressure synthetic lubricant manufacturers to justify higher upfront costs.
Limited Awareness and Technical Expertise Hinder Market Penetration in Emerging Regions
Many potential users, especially in emerging markets, lack awareness of the functional benefits and appropriate applications of synthetic lubricants. Misconceptions regarding compatibility, usage intervals, and switching procedures persist among end-users and distributors. The Synthetic Lubricants Market must overcome these barriers through training, technical support, and collaboration with OEMs and service providers. It also contends with the lack of infrastructure for proper distribution, handling, and storage in underdeveloped areas. Limited availability of specialized synthetic formulations further restricts penetration into remote or industrially immature regions. Addressing these knowledge and accessibility gaps remains a critical challenge for sustained market growth.
Market Opportunities:
Expansion in Electric Vehicles and Renewable Energy Applications Unlocks New Demand
The global shift toward electric mobility and renewable energy infrastructure offers significant growth avenues for synthetic lubricants. Electric vehicles require advanced fluids for battery cooling, gearbox lubrication, and thermal management-areas where synthetic formulations deliver optimal performance. Wind turbines, solar equipment, and hydroelectric systems also depend on high-performance lubricants to ensure long-term reliability under extreme conditions. The Synthetic Lubricants Market can capitalize on these evolving needs by offering customized products that meet the unique specifications of clean energy systems. It holds an opportunity to establish partnerships with EV manufacturers and renewable energy developers to secure long-term supply contracts. These high-growth sectors represent scalable, long-term demand for specialty lubricants.
Rising Focus on Industrial Automation and High-Precision Equipment Drives Product Innovation
As industries adopt automation and smart manufacturing systems, the need for reliable, low-maintenance lubricants becomes increasingly critical. Synthetic lubricants enable smoother operations in robotics, CNC machinery, and precision manufacturing tools due to their stability under high stress and extended usage. The Synthetic Lubricants Market stands to benefit by aligning its offerings with the requirements of digitally driven and high-performance production environments. It has an opportunity to lead innovation in smart lubricants compatible with predictive maintenance systems. This trend supports both market expansion and the development of value-added product lines for mission-critical industrial applications.
Market Segmentation Analysis:
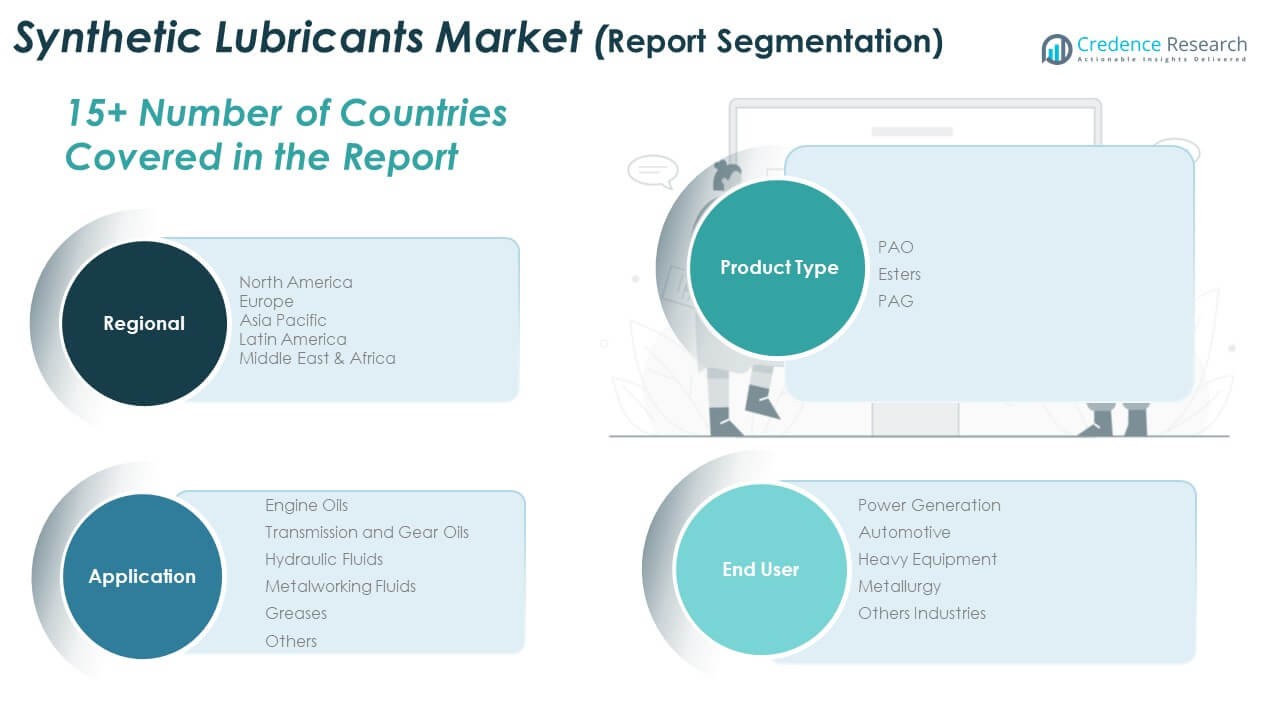
The Synthetic Lubricants Market is segmented by product type, application, and end-user, each playing a distinct role in shaping demand dynamics.
By product type, PAO (Polyalphaolefin) dominates the market due to its superior thermal stability, oxidation resistance, and compatibility with various engine systems. Esters offer excellent biodegradability and high lubricity, making them suitable for environmentally sensitive applications. PAG (Polyalkylene Glycol) is gaining traction in specialized uses like refrigeration and industrial gear oils due to its inherent water solubility and shear stability.
By application, engine oils represent the largest segment, driven by widespread use in passenger and commercial vehicles requiring high-performance lubricants. Transmission and gear oils follow, supported by demand in both automotive and heavy machinery. Hydraulic fluids and metalworking fluids serve critical roles in industrial manufacturing, while greases provide reliable protection in extreme conditions. The others category includes niche formulations for specialty equipment.
- For example, Mobil 1 and Castrol offer high-performance synthetic engine oils widely used in passenger and commercial vehicles, emphasizing durability and advanced engine protection.
By end-user, the automotive sector leads consumption, followed by heavy equipment and power generation, where synthetic lubricants enhance operational efficiency and extend maintenance cycles. Metallurgy and other industries contribute steadily, driven by process optimization and energy savings. The market reflects a balanced mix of mass-scale and precision applications.
- For example, ExxonMobil and Chevron offer synthetic lubricants for turbines and generators, focusing on high thermal stability and long service intervals.
Segmentation:
By Product Type
- PAO (Polyalphaolefin)
- Esters
- PAG (Polyalkylene Glycol)
By Application
- Engine Oils
- Transmission and Gear Oils
- Hydraulic Fluids
- Metalworking Fluids
- Greases
- Others
By End-User
- Power Generation
- Automotive
- Heavy Equipment
- Metallurgy
- Other Industries
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Southeast Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East
- GCC Countries
- Israel
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
Regional Analysis:
North America
The North America Synthetic Lubricants Market size was valued at USD 4,715.82 million in 2018 to USD 5,881.28 million in 2024 and is anticipated to reach USD 7,499.77 million by 2032, at a CAGR of 3.10% during the forecast period. North America holds a strong position in the market due to its established automotive and industrial sectors. It benefits from rising demand for high-performance lubricants in commercial transportation, aerospace, and heavy machinery applications. Stringent environmental regulations and a mature customer base support the growing shift from conventional to synthetic formulations. The market continues to expand with technological innovation and widespread use of advanced engines that require premium lubricants. The Synthetic Lubricants Market in this region also sees traction from the expanding electric vehicle segment and the adoption of energy-efficient lubricants. Strong OEM partnerships and high awareness contribute to its sustained market penetration.
Europe
The Europe Synthetic Lubricants Market size was valued at USD 6,371.75 million in 2018 to USD 8,040.59 million in 2024 and is anticipated to reach USD 10,416.35 million by 2032, at a CAGR of 3.30% during the forecast period. Europe maintains a significant share of the global market, driven by strict emissions regulations and advanced automotive technologies. It benefits from a strong industrial base and high consumer demand for premium-grade lubricants that offer extended drain intervals and superior performance. The region also leads in sustainability, encouraging the use of synthetic and bio-based alternatives. The Synthetic Lubricants Market is supported by major manufacturers located in Germany, France, and the UK, which contribute to product innovation. Growth is also driven by demand in wind energy, precision equipment, and industrial automation. Shifts in mobility trends and a push toward electrification strengthen the region's outlook.
Asia Pacific
The Asia Pacific Synthetic Lubricants Market size was valued at USD 10,372.74 million in 2018 to USD 13,286.46 million in 2024 and is anticipated to reach USD 17,549.47 million by 2032, at a CAGR of 3.50% during the forecast period. Asia Pacific holds the largest share of the global market, driven by rapid industrialization, expanding automotive production, and rising infrastructure investment. Countries like China, India, Japan, and South Korea play a central role in shaping demand across manufacturing, energy, and transportation sectors. The Synthetic Lubricants Market benefits from growing consumer awareness, increased vehicle ownership, and rising demand for cost-efficient maintenance solutions. It also gains momentum from growing electric vehicle production and ongoing industrial upgrades. Government initiatives promoting energy efficiency and environmental responsibility further accelerate the adoption of synthetic lubricants. The region remains a key focus area for global manufacturers expanding capacity and distribution networks.
Latin America
The Latin America Synthetic Lubricants Market size was valued at USD 1,517.08 million in 2018 to USD 1,782.49 million in 2024 and is anticipated to reach USD 2,083.27 million by 2032, at a CAGR of 1.90% during the forecast period. Latin America's market growth is moderate due to varying levels of industrial maturity and economic development across the region. Brazil and Mexico are the leading contributors, with demand concentrated in automotive, mining, and light manufacturing industries. The Synthetic Lubricants Market in this region faces challenges related to price sensitivity and lower awareness of product benefits. However, opportunities exist in expanding urban infrastructure and commercial vehicle fleets. As environmental regulations evolve, industries are gradually adopting synthetic solutions for performance and compliance. Market growth may accelerate with targeted awareness campaigns and investment in supply chain development.
Middle East
The Middle East Synthetic Lubricants Market size was valued at USD 1,828.21 million in 2018 to USD 2,310.77 million in 2024 and is anticipated to reach USD 2,999.91 million by 2032, at a CAGR of 3.30% during the forecast period. The market benefits from a strong oil and gas presence, along with a growing focus on non-oil industrial diversification. Demand is rising in sectors such as construction, power generation, and marine due to the region’s expanding infrastructure and logistics capabilities. The Synthetic Lubricants Market supports equipment that operates under extreme temperatures and harsh conditions, offering performance advantages over conventional oils. Regional governments are investing in economic diversification programs, which include modernizing industrial operations and adopting more sustainable practices. These shifts are supporting the growth of high-quality lubricants across the Gulf countries. Industrial modernization and growing awareness continue to open new market opportunities.
Africa
The Africa Synthetic Lubricants Market size was valued at USD 907.68 million in 2018 to USD 1,023.31 million in 2024 and is anticipated to reach USD 1,116.63 million by 2032, at a CAGR of 1.00% during the forecast period. Africa holds a relatively small share of the global market, constrained by limited industrial infrastructure and low product awareness. The market primarily serves mining, transportation, and basic manufacturing sectors in countries like South Africa, Nigeria, and Egypt. The Synthetic Lubricants Market in Africa faces price sensitivity and logistical challenges that restrict widespread adoption. However, it presents long-term potential as infrastructure development and industrial investments increase. Regional economic integration and foreign investments in manufacturing could gradually raise demand for high-performance lubricants. Building technical capacity and distributor networks remains key to unlocking market expansion.
Key Player Analysis:
- BP Lubricants Pvt. Ltd.
- Chevron Corporation
- LANXESS
- Valvoline
- FUCHS
- Pennzoil
- Phillips 66 Company
- Motul
- AMSOIL INC.
- Agip
- Other Key Players
Competitive Analysis:
The Synthetic Lubricants Market features strong competition among global players focused on technological innovation, brand differentiation, and strategic partnerships. Key companies such as ExxonMobil, Shell, Chevron, BP, and TotalEnergies dominate the market with extensive product portfolios and established distribution networks. It remains highly competitive due to the constant demand for performance-enhancing formulations across automotive, industrial, and energy sectors. Companies are investing in R&D to develop low-viscosity, fuel-efficient, and environmentally compliant lubricants. The market also sees rising activity from regional players targeting niche applications and emerging economies. Pricing strategies, OEM collaborations, and product customization play a critical role in capturing market share. The Synthetic Lubricants Market continues to evolve with increasing focus on sustainability and digital integration in lubrication solutions. Competitive dynamics are further shaped by advancements in EV fluids, smart maintenance compatibility, and expanding end-user education.
Recent Developments:
- In January 2025, Chevron U.S.A. Inc. announced a partnership with Engine No. 1 to develop scalable, reliable power solutions for U.S.-based data centers, leveraging U.S. natural gas. The joint development, in collaboration with GE Vernova, aims to establish multi-gigawatt co-located power plants and data centers, with initial projects targeting up to four gigawatts of capacity and the flexibility to integrate lower-carbon solutions.
- In February 2025, BP announced a strategic review of its global lubricants business, particularly focusing on its Castrol brand, with the intention to accelerate Castrol’s next phase of value delivery. This review is considering all options, including potential divestment, to strengthen BP’s balance sheet and enhance Castrol’s growth in core mobility, industrial lubricants, and new areas such as data center fluids
- In June 2023, Shell, a leading player in the synthetic lubricants market, introduced two new synthetic engine oils-Shell Helix HX6 5W-30 and Shell Helix SUV 5W-30-in India. These products are specifically designed to meet BS-VI emission standards and aim to deliver enhanced engine protection, improved fuel efficiency, and longer engine life for the passenger car motor oil (PCMO) segment.
- In October 2023, Chevron Corporation made a significant move in the industry by entering into a definitive agreement to acquire Hess Corporation in an all-stock transaction valued at USD 53 billion. The acquisition is intended to increase Chevron’s production capabilities and accelerate free cash flow. Earlier, in August 2023, Chevron completed its acquisition of PDC Energy, Inc., which added substantial oil and gas reserves and production acreage to its portfolio.
Market Concentration & Characteristics:
The Synthetic Lubricants Market exhibits moderate to high market concentration, with a few multinational corporations holding a significant share. It is characterized by strong brand loyalty, technical product differentiation, and high entry barriers due to the capital-intensive nature of production and R&D. Major players dominate through global distribution networks, long-term OEM partnerships, and advanced formulation capabilities. The market favors innovation, with consistent demand for lubricants that enhance fuel efficiency, extend equipment life, and meet regulatory standards. It also reflects a growing shift toward sustainability, pushing suppliers to develop environmentally responsible products. Regional players compete in cost-sensitive segments but face challenges in scaling operations and achieving product quality parity. The Synthetic Lubricants Market continues to consolidate around firms that can deliver performance, compliance, and cost-effectiveness in dynamic industrial environments.
Report Coverage:
The research report offers an in-depth analysis based on Product Type, Application and End-User. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising adoption of electric vehicles will create strong demand for advanced thermal and drivetrain fluids.
- Expanding industrial automation will increase reliance on high-performance lubricants for precision equipment.
- Stricter global emission norms will accelerate the shift toward synthetic and eco-friendly formulations.
- Technological advancements will lead to the development of longer-lasting and low-viscosity lubricants.
- Increasing awareness of lifecycle cost savings will boost synthetic lubricant adoption in cost-sensitive markets.
- Growth in renewable energy infrastructure will generate new opportunities in wind, solar, and hydro applications.
- Emerging markets in Asia Pacific, Middle East, and Latin America will drive volume expansion through industrialization.
- OEM endorsements and product-specific approvals will strengthen brand positioning and customer loyalty.
- Digital integration and smart maintenance systems will favor synthetic lubricants with predictive compatibility.
- Ongoing R&D investment will support innovation in bio-based and hybrid synthetic lubricant technologies

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Synthetic Lubricants Market?
What factors are driving the growth of the Synthetic Lubricants Market?
What are the key segments within the Synthetic Lubricants Market?
What are some challenges faced by the Synthetic Lubricants Market?
Who are the major players in the Synthetic Lubricants Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Synthetic Lubricants Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2018; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Synthetic Lubricants Market Snapshot
- 2.1.1 Market Size – Historical (2018) & Forecast (2018-2032) (2018: USD 25,713.3 million → 2032: USD 41,665.4 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Synthetic Lubricants Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2018 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2018
- 2.3.2 Top 10 Players by Volume Share – 2018 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Synthetic Lubricants Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Synthetic Lubricants Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Synthetic Lubricants Market Drivers
- 3.3 Synthetic Lubricants Market Restraints & Challenges
- 3.4 Synthetic Lubricants Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Synthetic Lubricants Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Synthetic Lubricants Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Synthetic Lubricants category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Synthetic Lubricants Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Synthetic Lubricants Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2018)
- 5.1.2 Global Export Volume by Country (2018) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2018)
- 5.1.4 Global Import Volume by Country (2018) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2018)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2018)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Synthetic Lubricants. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Synthetic Lubricants Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2018
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Synthetic Lubricants Market Share Analysis – 2018
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2018)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Synthetic Lubricants Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Synthetic Lubricants (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Synthetic Lubricants
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Synthetic Lubricants Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2018 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2018-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Synthetic Lubricants Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Synthetic Lubricants Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Synthetic Lubricants Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Synthetic Lubricants Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Synthetic Lubricants Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Synthetic Lubricants Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Synthetic Lubricants Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
