
Market Overview:
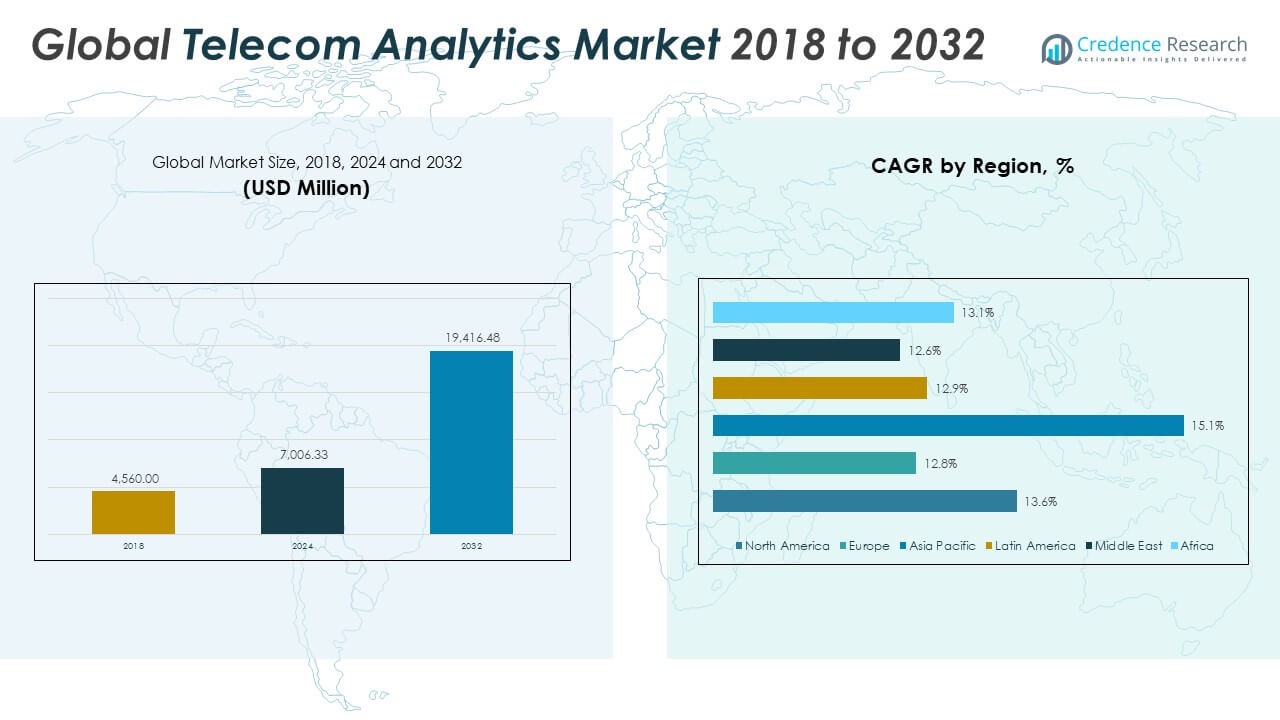
The Telecom Analytics Market size was valued at USD 4,560.00 million in 2018 to USD 7,006.33 million in 2024 and is anticipated to reach USD 19,416.48 million by 2032, at a CAGR of 13.66% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Telecom Analytics Market Size 2024 | USD 7,006.33 million |
| Telecom Analytics Market, CAGR | 13.66% |
| Telecom Analytics Market Size 2032 | USD 19,416.48 million |
The growth of the telecom analytics market is being driven by increasing data volumes, the adoption of advanced technologies like AI and machine learning, and the rising need for customer experience optimization. Telecom operators are leveraging analytics to improve network performance, detect fraud, and personalize services. As customer expectations evolve and competition intensifies, analytics solutions are becoming essential for strategic decision-making, revenue assurance, and operational efficiency across the telecom sector.
Regionally, North America leads the telecom analytics market due to the presence of established telecom infrastructure and early adoption of digital technologies. Europe follows closely with its strong regulatory framework encouraging data transparency and network optimization. The Asia Pacific region is emerging as the fastest-growing market, fueled by the rapid expansion of mobile and internet services, especially in countries like India and China. Meanwhile, Latin America and the Middle East & Africa are showing steady progress due to increasing investments in telecom modernization.
Market Insights:
- The Telecom Analytics Market was valued at USD 4,560.00 million in 2018 and reached USD 7,006.33 million in 2024; it is projected to hit USD 19,416.48 million by 2032, growing at a CAGR of 13.66%.
- Rising demand for real-time insights and operational efficiency is driving telecom operators to adopt advanced analytics solutions.
- Integration of AI and machine learning into analytics platforms enhances predictive accuracy and network optimization.
- Strict data privacy regulations and complex compliance requirements continue to challenge analytics deployment.
- North America dominates the global market due to strong telecom infrastructure and early technology adoption.
- Asia Pacific emerges as the fastest-growing region, fueled by expanding mobile usage and 5G rollouts in countries like China and India.
- Limited internal expertise and integration barriers hinder small and mid-sized telecom firms from scaling analytics capabilities efficiently.
Market Drivers:
Rising Need for Real-Time Decision-Making in Telecom Operations
Telecom companies increasingly prioritize real-time insights to make operational decisions faster and with greater accuracy. The vast volume of customer and network data creates a demand for advanced analytics that can process information instantly. The Telecom Analytics Market supports this shift by delivering tools that help operators detect anomalies, optimize traffic flow, and prevent service disruptions. Real-time analytics reduces downtime and improves service reliability, which directly impacts customer satisfaction. Companies aim to reduce churn by acting on data insights without delay. Faster decision-making enhances operational agility, especially in competitive markets. It helps organizations identify performance issues before they escalate. The market aligns with telecom operators' demand for continuous optimization.
- For instance, Ericsson has deployed AI-based network management that has achieved 99.91% network availability for its clients through autonomous traffic optimization and incident reduction platforms.
Growing Demand for Personalized Customer Experience and Retention
Operators focus on customer-centric strategies to retain subscribers and drive loyalty. Personalized services and proactive engagement rely on in-depth behavioral analysis. The Telecom Analytics Market offers solutions that segment audiences, track usage patterns, and predict churn risks. It enables telecom providers to create customized plans and targeted promotions. This approach helps companies boost retention rates and enhance brand perception. Customer experience has become a key differentiator in saturated markets. Analytics empowers firms to identify dissatisfaction signals and intervene early. This driver propels long-term strategic investments in customer intelligence systems.
Expansion of Network Infrastructure and Complexity of Data Traffic
Telecom networks continue to grow in scale and complexity due to rising device usage and 5G rollouts. This expansion increases the demand for analytics platforms capable of managing diverse data streams. The Telecom Analytics Market addresses this challenge with solutions that analyze data from multiple layers-voice, video, and internet. Operators rely on analytics to maintain quality of service across these expanding networks. It helps in bandwidth allocation, congestion control, and resource planning. The ability to monitor and optimize infrastructure in real time is essential. The market supports telecom companies in navigating growing user bases and evolving traffic behavior. Strategic planning now depends on continuous visibility into network performance.
- For example, Cisco’s 5G cloud-to-client unified architecture, for example, simplifies multivendor management and enables seamless open vRAN deployment, delivering up to 3x faster onboarding of network assets and immediate performance telemetry updates.
Fraud Detection and Revenue Assurance Across Global Telecom Chains
Revenue leakage and telecom fraud represent major concerns in the sector. Telecom operators experience frequent losses due to subscription fraud, identity spoofing, and billing errors. The Telecom Analytics Market plays a central role in identifying suspicious activity and enforcing compliance protocols. It helps providers detect anomalies across call records, billing cycles, and user authentication. Advanced pattern recognition aids in reducing false positives and strengthens fraud prevention. Organizations use analytics to reconcile discrepancies and ensure data integrity. The technology provides transparency into revenue streams and enhances financial accuracy. It also assists in audit trails, internal controls, and policy enforcement.
Market Trends:
Integration of Artificial Intelligence and Machine Learning Capabilities
Telecom firms increasingly deploy AI and ML to automate data analysis processes. These technologies add predictive capabilities and enhance anomaly detection. The Telecom Analytics Market incorporates AI to support use cases like churn forecasting, demand prediction, and network optimization. It enables automated decision-making and accelerates performance evaluation. AI models continuously improve accuracy by learning from ongoing data input. Operators use these systems to personalize user experiences and optimize customer journeys. Advanced automation reduces manual intervention and minimizes operational errors. It transforms legacy reporting methods into dynamic, learning-based systems.
Emergence of Cloud-Based Analytics Platforms in Telecom Sector
Cloud-based deployment models are gaining prominence across telecom operations. Companies seek scalable, flexible, and cost-effective solutions to manage analytics workloads. The Telecom Analytics Market reflects this shift by offering cloud-native analytics tools tailored for distributed infrastructures. Cloud platforms enable centralized monitoring of regional telecom activities. They also allow integration across business units and reduce latency in data processing. Cloud adoption enhances collaboration across geographically dispersed teams. Operators benefit from easier system updates and reduced on-premise infrastructure costs. This trend supports agility and global expansion strategies.
- For example, TIBCO Spotfire, a leading enterprise analytics solution, enables telecoms to conduct in-database analysis of enormous data volumes, such as call detail records and IoT logs, handling millions of entries simultaneously. Spotfire integrates AI-driven recommendation engines and predictive tools, with deployment scales reaching up to $10,000 per data scientist license for high-end users.
Use of Analytics to Optimize 5G Rollouts and Smart Infrastructure
Operators leverage analytics to streamline their 5G implementation and expansion plans. It helps assess demand hotspots, infrastructure readiness, and service quality in real time. The Telecom Analytics Market offers tools to plan spectrum allocation and site deployment strategies more efficiently. Insights support informed investment decisions and network optimization. Telecom firms use analytics to evaluate pilot programs and user experience metrics. It enables better coordination between field operations and planning units. Smart cities and connected environments further increase the relevance of such analytics. Providers integrate performance feedback into ongoing 5G strategy refinement.
Shift Toward Open Data Models and Interoperability Standards
Telecom operators demand systems that can exchange information seamlessly across platforms. The push for open data models increases the adoption of standardized analytics solutions. The Telecom Analytics Market aligns with this trend by supporting interoperability with multiple vendor systems. Companies aim to reduce dependence on proprietary platforms and improve vendor flexibility. Open models facilitate multi-source integration and richer data analysis. It enables cross-functional insights across customer service, engineering, and finance units. Adoption of common APIs enhances collaboration across ecosystem partners. Regulatory pressure for data transparency also supports this trend.
- For instance, Google Cloud’s Telecom Data Fabric, for example, provides unified reusable data models and pre-built adapters for seamless data aggregation across multi-vendor environments, supporting API-driven analytics and enabling cross-system data governance.
Market Challenges Analysis:
Data Privacy Regulations and Compliance Requirements Create Barriers
Strict data protection laws create operational hurdles for telecom analytics implementation. Companies must comply with GDPR, CCPA, and similar regulations across regions. The Telecom Analytics Market faces challenges in balancing compliance with deep behavioral analysis. Encryption, anonymization, and consent mechanisms increase the complexity of system design. Non-compliance risks significant legal penalties and reputational damage. Cross-border data transfers require legal scrutiny and localized storage practices. It limits the use of certain advanced profiling techniques. Operators must invest heavily in data governance frameworks and audit trails.
Limited In-House Expertise and Integration Complexity Among Telecom Firms
Deploying analytics solutions requires advanced technical expertise, which many telecom firms lack internally. The skills gap hampers implementation timelines and limits full-scale adoption. The Telecom Analytics Market often depends on third-party providers for deployment and maintenance. Integrating analytics with legacy infrastructure presents further difficulty. Compatibility issues, data silos, and organizational resistance slow transformation efforts. Small and mid-size operators face higher adoption barriers due to budget and workforce constraints. This challenge delays return on investment and restricts innovation pace in less mature markets.
Market Opportunities:
Expansion of IoT Ecosystems and Smart Services in Telecom Networks
The growing use of connected devices across homes, cities, and industries generates vast telemetry data. The Telecom Analytics Market finds new opportunities in managing and interpreting this machine-driven data. It enables predictive maintenance, device optimization, and service customization. IoT expansion demands real-time analytics for both operational and customer-facing outcomes. Telecom providers can tap into new revenue streams by offering analytics-driven value-added services. This opportunity opens the market to ecosystem partnerships.
Rising Adoption of Self-Service Analytics Tools by Telecom Operators
Telecom companies are increasingly embracing self-service analytics platforms that empower business users. These tools reduce reliance on IT departments and accelerate insight generation. The Telecom Analytics Market benefits from this shift toward democratized data access. It creates opportunities to design intuitive, user-friendly dashboards and visual analytics interfaces. Self-service platforms also drive data-driven culture across departments. Operators achieve faster time-to-insight and improve decision quality at all organizational levels.
Market Segmentation Analysis:
The Telecom Analytics Market is segmented by component, application, deployment model, and organization size.
By component, the market includes solutions and services. Among solutions, network analytics leads due to its role in monitoring and improving service quality. Customer analytics and subscriber analytics follow, supporting churn prediction and behavior insights. Location, price, and service analytics also contribute to performance optimization and revenue enhancement. Services complement solution deployment and customization across enterprises.
- For example, Vodafone partnered with Google Cloud and Quantexa to build a unified analytics platform that provides a 360-degree view of customers. This system aggregates and analyzes interactions and service usage in real time. The solution integrates Quantexa’s AI-based decision-intelligence tools on Google Cloud infrastructure, enabling real-time churn prediction and proactive customer intervention via personalized offers
By application, the Telecom Analytics Market spans customer management, network management, risk and compliance management, workforce management, sales and marketing management, and others. Customer and network management represent the dominant segments, reflecting the industry's focus on user retention and infrastructure performance. Risk and compliance analytics gain relevance amid growing regulatory complexity.
- For example, AT&Tapplies AI-powered tools to real-time traffic forecasting, spectrum allocation, and equipment configuration. This enables efficient resource use and optimal cell site deployment, boosting network performance and service reliability.
By Deployment model segmentation includes cloud and on-premise. Cloud deployment holds a growing share due to its scalability and reduced infrastructure costs. On-premise models remain relevant for data-sensitive operations.
By organization size, large enterprises lead adoption due to greater budgets and operational scale. Small and mid-sized enterprises are showing increased interest as cloud-based models lower entry barriers.
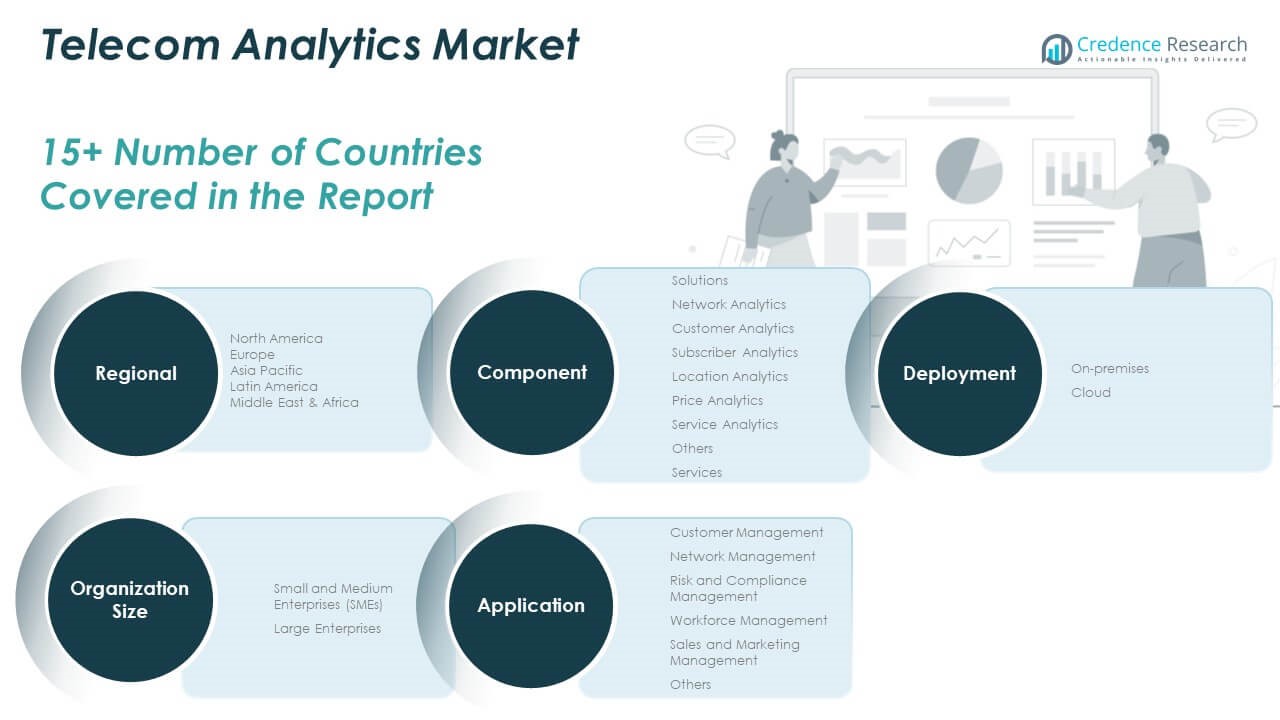
Segmentation:
By Component
- Solutions
- Network Analytics
- Customer Analytics
- Subscriber Analytics
- Location Analytics
- Price Analytics
- Service Analytics
- Others
- Services
By Application
- Customer Management
- Network Management
- Risk and Compliance Management
- Workforce Management
- Sales and Marketing Management
- Others
By Deployment Model
- Cloud
- On-Premise
By Organization Size
- Small and Mid-Sized Enterprises
- Large Enterprises
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America Telecom Analytics Market size was valued at USD 1,798.92 million in 2018 to USD 2,733.13 million in 2024 and is anticipated to reach USD 7,550.88 million by 2032, at a CAGR of 13.6% during the forecast period. North America holds the largest market share of 39.01% in the global landscape due to the early adoption of digital transformation initiatives. Telecom operators in the U.S. and Canada continue to invest in advanced analytics to enhance customer experience, optimize network efficiency, and prevent fraud. The region’s mature telecom infrastructure supports real-time data processing and AI deployment. Strategic partnerships between telecom firms and analytics vendors drive innovation. It benefits from strong regulatory support for data security and transparency.
Europe
The Europe Telecom Analytics Market size was valued at USD 1,071.60 million in 2018 to USD 1,574.83 million in 2024 and is anticipated to reach USD 4,092.08 million by 2032, at a CAGR of 12.8% during the forecast period. Europe accounts for 22.48% of the global market, driven by increasing telecom regulations and a strong emphasis on data governance. Telecom operators focus on using analytics for network optimization, customer segmentation, and churn management. The General Data Protection Regulation (GDPR) shapes the way companies collect and analyze customer data. It helps promote secure and ethical use of telecom analytics. Countries such as Germany, France, and the UK lead the adoption of predictive analytics and AI-powered telecom platforms. European telecom firms prioritize multi-channel customer engagement through analytics.
Asia Pacific
The Asia Pacific Telecom Analytics Market size was valued at USD 971.28 million in 2018 to USD 1,568.34 million in 2024 and is anticipated to reach USD 4,813.71 million by 2032, at a CAGR of 15.1% during the forecast period. Asia Pacific holds a 24.79% share of the global market and represents the fastest-growing regional segment. Rapid urbanization, rising smartphone penetration, and the expansion of 5G networks drive the demand for telecom analytics. It supports telecom operators in handling the surge in data traffic and improving operational efficiency. Countries like China, India, South Korea, and Japan are investing heavily in AI-driven platforms and cloud-based analytics solutions. Local operators seek cost-effective tools to reduce churn and increase ARPU. Government-led digital transformation programs accelerate analytics adoption across telecom sectors.
Latin America
The Latin America Telecom Analytics Market size was valued at USD 369.36 million in 2018 to USD 563.24 million in 2024 and is anticipated to reach USD 1,473.13 million by 2032, at a CAGR of 12.9% during the forecast period. Latin America contributes 7.59% of the global market share and is seeing gradual adoption of telecom analytics solutions. Operators in Brazil, Mexico, and Argentina are embracing analytics to enhance billing accuracy and improve service personalization. It supports fraud detection and usage forecasting in regional networks. Limited infrastructure and budget constraints slow down large-scale deployment. However, cloud-based models are helping overcome these limitations. Strategic alliances with international vendors expand the availability of advanced analytics platforms.
Middle East
The Middle East Telecom Analytics Market size was valued at USD 232.56 million in 2018 to USD 340.46 million in 2024 and is anticipated to reach USD 875.79 million by 2032, at a CAGR of 12.6% during the forecast period. The region holds a 4.51% share in the global market and reflects growing digital ambitions among Gulf countries. Governments in the UAE and Saudi Arabia prioritize digital infrastructure and smart city investments, which include telecom analytics integration. It helps operators manage high-value customer segments and optimize data-driven services. The demand for quality customer experience and fraud protection is increasing. Analytics is used to monitor real-time usage trends and improve network availability. firms adopt cloud-based and hybrid analytics platforms to align with their modernization goals.
Africa
The Africa Telecom Analytics Market size was valued at USD 116.28 million in 2018 to USD 226.33 million in 2024 and is anticipated to reach USD 610.90 million by 2032, at a CAGR of 13.1% during the forecast period. Africa contributes 3.15% to the global market and is at an early stage of telecom analytics adoption. Operators focus on expanding basic network services while gradually integrating analytics to enhance service delivery. It supports initiatives in prepaid customer management, fraud control, and network optimization. Countries such as South Africa, Nigeria, and Kenya are investing in cloud solutions to accelerate analytics deployment. Limited digital infrastructure and workforce skill gaps remain key challenges. International funding and collaborations are supporting market development. Analytics adoption grows alongside mobile penetration and regulatory improvements.
Key Player Analysis:
- Adobe Inc.
- Alteryx
- Cisco Systems, Inc.
- SAP SE
- Hewlett Packard Enterprise Development LP
- Huawei Technologies Co., Ltd.
- IBM
- Microsoft
- MicroStrategy Incorporated
- Oracle
Competitive Analysis:
The Telecom Analytics Market features strong competition among global players, including IBM, Oracle, SAS Institute, Ericsson, and Huawei. These companies offer end-to-end analytics solutions covering customer experience, network performance, and fraud detection. Vendors invest in artificial intelligence, machine learning, and cloud-based platforms to strengthen product portfolios. It attracts new entrants aiming to serve regional operators with tailored, cost-effective offerings. Leading players differentiate through advanced analytics capabilities, integration flexibility, and real-time processing. Strategic partnerships and acquisitions help expand geographical reach and accelerate innovation. Telecom providers prefer vendors with a proven track record, scalable platforms, and regulatory compliance features. Competitive intensity continues to rise with growing demand for data-driven decision-making tools.
Recent Developments
- In June 2025, Adobe Inc. launched its first dedicated artificial intelligence app for smartphones, named Firefly, which integrates its proprietary AI with models from leading partners. While this new offering is focused on generative AI for image creation, Adobe continues to be active in the telecom analytics space through its Adobe Analytics platform.
- In July 2025, HPE completed the $14 billion acquisition of Juniper Networks. This transaction doubles HPE’s networking business, with a strong focus on AI-driven and hybrid cloud networking for data centers, enterprises, and telecom environments. The merger accelerates HPE’s ability to provide modern network architectures suited to next-generation telecom analytics driven by artificial intelligence
- In November 2024, Cisco Systems expanded its partnership with NTT DATA to offer enhanced secure and cost-effective mobile connectivity. This collaboration leverages Cisco’s eSIM technology within telecom infrastructures, streamlining global connectivity and network management for enterprise customers.
- In March 2024, Alteryx, a leader in enterprise analytics and AI, was acquired by Clearlake Capital Group and Insight Partners. This acquisition aims to accelerate Alteryx’s product innovation in AI and cloud analytics, providing enhanced analytics solutions for industries including telecommunications.
Market Concentration & Characteristics
The Telecom Analytics Market is moderately consolidated, with a mix of global technology providers and specialized regional firms. It features high entry barriers due to technical complexity, data compliance requirements, and infrastructure integration challenges. Leading players dominate large-scale deployments across mature markets, while smaller firms address niche demands in developing regions. It supports both cloud-based and on-premise models, catering to varied telecom needs. The market favors vendors that offer scalable, interoperable, and AI-enhanced platforms. Innovation cycles are short, driven by evolving network architectures and customer expectations. Buyers prioritize end-to-end capabilities and proven deployment success.
Report Coverage:
The research report offers an in-depth analysis based on component, application, deployment model, and organization size. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- AI and machine learning integration will become standard in analytics solutions across all telecom operators.
- Cloud-based platforms will drive faster deployment and enhance scalability in both developed and emerging markets.
- Telecom firms will increase investments in real-time customer insights to reduce churn and improve loyalty.
- Advanced analytics will support dynamic 5G infrastructure planning and performance optimization.
- Demand for fraud detection and revenue assurance tools will rise with growing data complexity.
- Regulatory compliance and data privacy concerns will shape analytics deployment strategies.
- Cross-functional integration of analytics across sales, operations, and finance will expand.
- The adoption of self-service analytics tools will empower non-technical users within telecom organizations.
- Partnerships between telecom providers and tech vendors will accelerate solution innovation.
- Edge analytics adoption will grow to support low-latency applications and network intelligence.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Real-Time Decision-Making in Telecom Operations
Telecom operators require advanced analytics to process vast volumes of customer and network data instantly, enabling faster and more accurate operational decisions. Real-time analytics tools help detect anomalies, optimize traffic flow, and prevent service disruptions, directly improving customer satisfaction and reducing churn.
Personalized Customer Experience and Retention
The need to retain subscribers and drive loyalty is pushing telecom companies to adopt analytics solutions that segment audiences, track usage patterns, and predict churn risks. These insights enable the creation of customized plans and targeted promotions, enhancing retention rates and brand perception.
Expansion of Network Infrastructure and Data Complexity
The rapid growth of telecom networks and the rollout of 5G have increased the complexity and volume of data traffic. Analytics platforms are essential for managing diverse data streams, maintaining quality of service, and supporting bandwidth allocation and resource planning across expanding infrastructures.
Fraud Detection and Revenue Assurance
Telecom analytics play a critical role in identifying suspicious activities such as subscription fraud, identity spoofing, and billing errors. Advanced pattern recognition and anomaly detection help operators reduce revenue leakage, enforce compliance, and ensure financial accuracy.
Integration of AI and Machine Learning
The adoption of AI and machine learning in analytics platforms enhances predictive accuracy and automates anomaly detection, supporting use cases like churn forecasting, demand prediction, and network optimization. These technologies enable telecom operators to make data-driven decisions more efficiently and with greater precision.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Telecom Analytics Market?
What factors are driving the growth of the Telecom Analytics Market?
What are the key segments within the Telecom Analytics Market?
What are some challenges faced by the Telecom Analytics Market?
Who are the major players in the Telecom Analytics Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Component
- 1.2.1 Solutions
- 1.2.2 Network Analytics
- 1.2.3 Customer Analytics
- 1.2.4 Subscriber Analytics
- 1.2.5 Location Analytics
- 1.2.6 Price Analytics
- 1.2.7 Service Analytics
- 1.2.8 Services
- 1.3 By Application
- 1.3.1 Customer Management
- 1.3.2 Network Management
- 1.3.3 Risk and Compliance Management
- 1.3.4 Workforce Management
- 1.3.5 Sales and Marketing Management
- 1.3.6 Others
- 1.4 By Deployment Model
- 1.4.1 Cloud
- 1.4.2 On-Premise
- 1.5 By Organization Size
- 1.5.1 Small and Mid-Sized Enterprises
- 1.5.2 Large Enterprises
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2018: USD 4,560.00 million → 2032: USD 19,416.48 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2018
- 2.6.2 Forecast Period: 2018-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2018
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Telecom Analytics Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Telecom Analytics Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2018-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Telecom Analytics Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2018-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Telecom Analytics Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Telecom Analytics Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Telecom Analytics Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Telecom Analytics Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Telecom Analytics Market Outlook, 2018-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2018: USD 4,560.00 million → 2032: USD 19,416.48 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2018
- 11.2 Market Forecast, 2018-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Telecom Analytics Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2018
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Component - Market Size and Forecast, 2018-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2018-2032
- 12.3.4 Base-Year Market Share, 2018
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Solutions
- 12.3.6.2 Network Analytics
- 12.3.6.3 Customer Analytics
- 12.3.6.4 Subscriber Analytics
- 12.3.6.5 Location Analytics
- 12.3.6.6 Price Analytics
- 12.3.6.7 Service Analytics
- 12.3.6.8 Services
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2018-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2018-2032
- 12.4.4 Base-Year Market Share, 2018
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Customer Management
- 12.4.6.2 Network Management
- 12.4.6.3 Risk and Compliance Management
- 12.4.6.4 Workforce Management
- 12.4.6.5 Sales and Marketing Management
- 12.4.6.6 Others
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Deployment Model - Market Size and Forecast, 2018-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2018-2032
- 12.5.4 Base-Year Market Share, 2018
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Cloud
- 12.5.6.2 On-Premise
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 By Organization Size - Market Size and Forecast, 2018-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2018-2032
- 12.6.4 Base-Year Market Share, 2018
- 12.6.5 Segment CAGR and Growth Drivers
- 12.6.6 Subsegment Market Size and Forecast
- 12.6.6.1 Small and Mid-Sized Enterprises
- 12.6.6.2 Large Enterprises
- 12.6.7 Subsegment Pricing and Adoption Trends
- 12.6.8 Leading Suppliers and Competition
- 12.6.9 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Telecom Analytics End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Telecom Analytics Geographic Market Outlook, 2018-2032
- 14.1 Regional Market Size and Share, 2018
- 14.2 Regional Market Forecast, 2018-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Telecom Analytics Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2018-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Telecom Analytics Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2018
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2018-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Adobe Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 Alteryx
- 18.4 Cisco Systems, Inc.
- 18.5 SAP SE
- 18.6 Hewlett Packard Enterprise Development LP
- 18.7 Huawei Technologies Co., Ltd.
- 18.8 IBM
- 18.9 Microsoft
- 18.10 MicroStrategy Incorporated
- 18.11 Oracle
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

