
Market Overview:
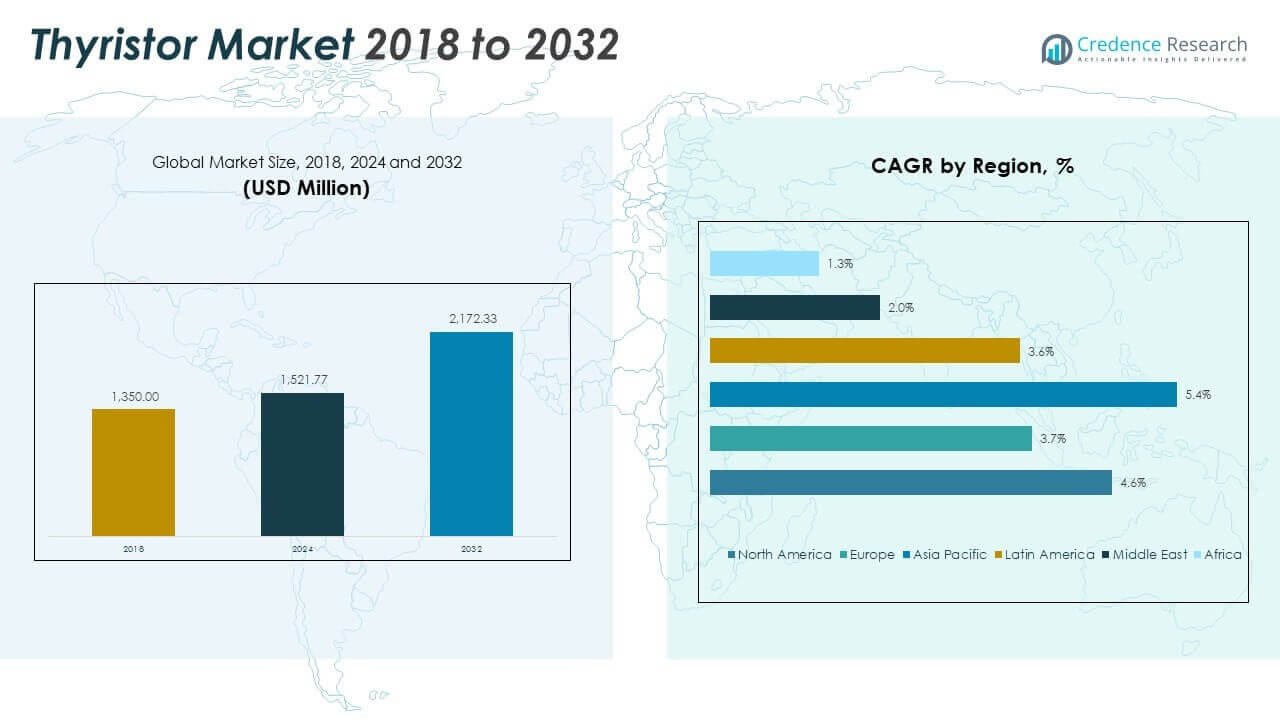
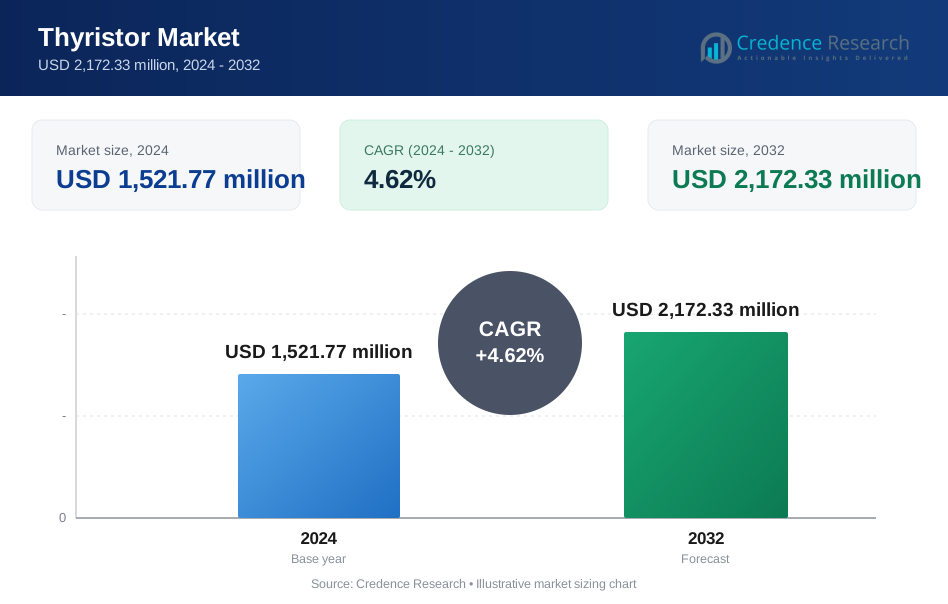
The Global Thyristor Market size was valued at USD 1,350.00 million in 2018 to USD 1,521.77 million in 2024 and is anticipated to reach USD 2,172.33 million by 2032, at a CAGR of 4.62% during the forecast period. The market shows steady expansion across power electronics uses. Growth reflects rising demand from industrial and utility sectors.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Thyristor Market Size 2024 | USD 1,521.77 million |
| Thyristor Market, CAGR | 4.62% |
| Thyristor Market Size 2032 | USD 2,172.33 million |
The Global Thyristor Market gains support from rising power control needs. Industrial automation increases use of controlled rectifiers. Power grids require reliable switching for voltage regulation. Electric rail systems depend on high current handling devices. Renewable energy inverters adopt thyristors for stable conversion. Heavy industries value durability under high load conditions. Manufacturing plants upgrade legacy power systems. Demand grows from motor drives and welding equipment. Long operating life supports repeat adoption across sectors.
Asia Pacific leads the Global Thyristor Market due to strong electronics manufacturing. China dominates through large-scale industrial and power projects. Japan and South Korea support demand with advanced semiconductor production. India emerges through grid expansion and rail electrification. Europe maintains stable demand from renewable energy integration. Germany and France focus on industrial automation upgrades. North America shows moderate growth from power utilities. Emerging regions adopt thyristors through infrastructure development.
Market Insights:
- The Global Thyristor Market size was USD 1,350.00 million in 2018, reached USD 1,521.77 million in 2024, and is projected to hit USD 2,172.33 million by 2032, growing at a CAGR of 4.62% during the forecast period.
- Asia Pacific leads with about 44% share due to large power infrastructure and manufacturing scale, followed by North America at nearly 26% driven by grid modernization, and Europe at around 20% supported by industrial automation and rail electrification.
- Asia Pacific is the fastest-growing region with a 5.4% CAGR, supported by strong demand from China and India, expanding rail networks, and continuous grid capacity additions.
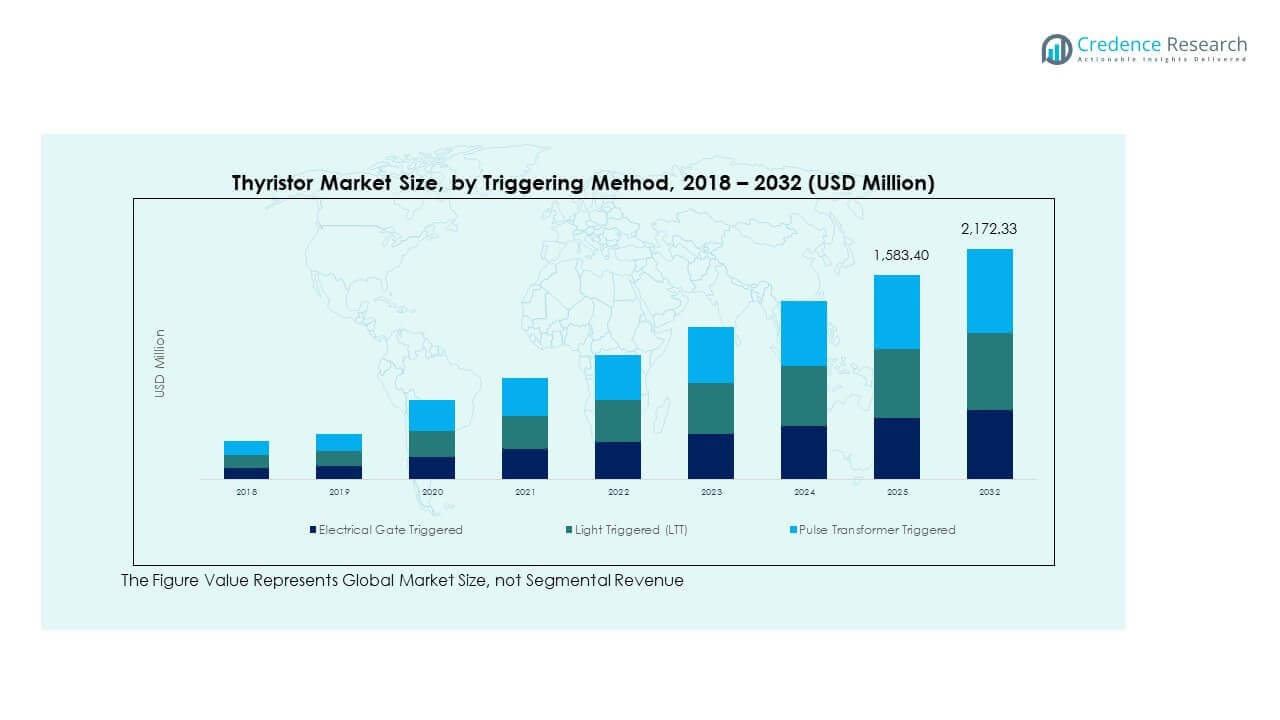
- Electrical gate triggered thyristors account for nearly 55% share, reflecting wide use in industrial power control, motor drives, and standard grid applications.
- Light triggered thyristors hold around 30% share, while pulse transformer triggered devices contribute close to 15%, supported by demand in high-voltage and noise-sensitive power systems.
Market Drivers:
Rising Demand For Reliable Power Control Across Industrial Systems
The Global Thyristor Market gains strength from rising industrial power control needs. Factories require stable current control for heavy equipment. Steel, cement, and mining plants depend on high load tolerance devices. Thyristors support consistent performance under harsh electrical conditions. Power stability improves production efficiency across industries. Equipment downtime reduction supports adoption decisions. Long service life reduces replacement frequency. Cost efficiency supports large scale deployment.
- For instance, ABB supplies phase control thyristors rated above 6 kA for steel rolling mills, enabling continuous furnace operation without unplanned shutdowns.
Expansion Of Electric Rail And Urban Transit Infrastructure
Electric rail networks rely on controlled power conversion systems. Thyristors manage traction power with high reliability. Metro projects expand across urban centers worldwide. Rail electrification programs increase component demand. Voltage control ensures safe train operations. High current capacity suits rail traction systems. Public transport investments support steady procurement. Infrastructure upgrades sustain long term demand.
- For instance, Siemens Mobility deploys IGBT and Silicon Carbide (SiC) based traction converters, such as the MoComp series, to handle multi-megawatt loads in metro systems across Europe and Asia, including major networks in London, Nuremberg, and Delhi.
Growing Deployment Of High Voltage Direct Current Transmission
HVDC systems require precise power switching components. Thyristors enable efficient long distance power transmission. Grid operators expand HVDC links for energy security. Cross border power trade increases system installations. Grid modernization projects adopt proven technologies. High voltage handling ensures operational safety. Utilities prefer mature and tested components. Reliability supports grid level adoption.
Increasing Use In Heavy Duty Motor Drives And Industrial Equipment
Motor drives require accurate speed and torque control. Thyristors support stable motor performance under load. Industrial automation increases controlled drive installations. Oil and gas facilities use robust power devices. Marine and offshore systems demand high durability. Equipment standardization favors known components. Maintenance simplicity supports operational continuity. Industrial growth sustains consistent demand.
Market Trends:
Shift Toward Compact And High Efficiency Power Semiconductor Designs
Manufacturers focus on compact thyristor module designs. Space constraints influence equipment architecture decisions. Smaller footprints support modern power cabinets. Thermal management improves through advanced packaging. Efficiency gains reduce energy losses. Design optimization supports higher power density. Equipment makers value flexible integration options. Innovation drives gradual product evolution.
- For instance, Infineon introduced press-pack thyristors with junction temperature limits reaching 135°C, improving reliability and power density in compact HVDC valve assemblies.
Integration Of Thyristors Within Hybrid Power Control Architectures
Power systems adopt hybrid semiconductor configurations. Thyristors combine with IGBTs for performance balance. Hybrid designs optimize switching and conduction roles. System designers improve efficiency through component pairing. Power electronics evolve toward modular layouts. Flexibility supports diverse voltage requirements. Engineering teams favor adaptable system designs. Architecture changes influence component selection.
- For instance, Mitsubishi Electric utilizes All-Silicon Carbide (SiC) power modules and High-Voltage IGBTs (HVIGBTs) in traction inverters to handle high-current loads while reducing energy consumption by up to 40%.
Growing Focus On Standardization And Certification Compliance
Global projects demand certified power components. Standards ensure safety and interoperability. Manufacturers align products with international norms. Certification reduces approval timelines for utilities. Compliance supports global market access. End users prefer standardized components. Quality assurance influences supplier selection. Regulatory alignment shapes procurement trends.
Gradual Adoption Of Digital Monitoring In Power Devices
Digital sensors enter power control systems. Condition monitoring improves predictive maintenance. Thyristor modules integrate basic diagnostics. Operators track thermal and electrical stress. Data visibility supports asset management. Digital features improve system reliability. Utilities value early fault detection. Monitoring adoption supports lifecycle optimization.
Market Challenges Analysis:
Rising Competition From Advanced Power Semiconductor Alternatives
The Global Thyristor Market faces pressure from newer devices. IGBTs and MOSFETs gain share in fast switching uses. These alternatives support higher switching frequencies. Compact designs attract modern equipment makers. Performance expectations continue to rise. Cost comparisons influence buyer decisions. Technology shifts affect traditional applications. Competitive pressure challenges long term positioning.
Complex Thermal Management And Design Constraints In High Power Uses
High power operation generates significant heat loads. Thermal control increases system design complexity. Cooling requirements raise installation costs. Improper heat control risks device failure. Engineering precision becomes critical. System integration requires skilled expertise. Design errors affect reliability outcomes. These constraints limit adoption in compact systems.
Market Opportunities:
Expansion Of Renewable Energy Grid Infrastructure Projects
Renewable grids require stable power conversion devices. Thyristors support voltage control in large systems. Solar and wind integration increases grid complexity. Utilities invest in proven power components. Long service life suits infrastructure assets. Grid balancing needs support adoption. Energy transition projects expand component demand. It benefits from large scale deployments.
Rising Electrification Across Emerging Industrial Economies
Emerging markets expand industrial power capacity. Manufacturing growth increases demand for control devices. Grid expansion supports reliable switching needs. Infrastructure projects adopt cost effective technologies. Local industries prefer durable components. Electrification programs drive equipment upgrades. Power stability supports economic development. It gains traction through long term investments.
Market Segmentation Analysis:
By Power Rating
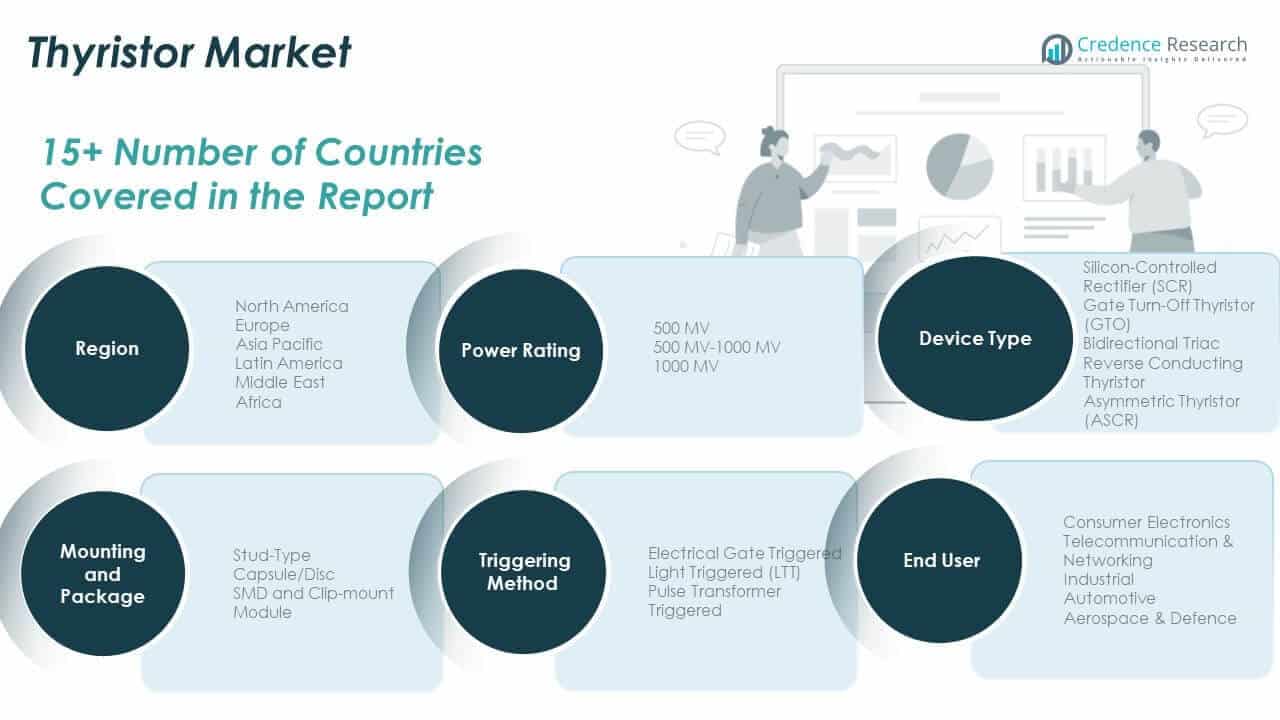
The Global Thyristor Market shows clear differentiation by power rating. The 500 MV segment supports consumer electronics and light industrial uses. This range suits compact systems with moderate load needs. The 500 MV–1000 MV segment serves rail traction and grid control equipment. High voltage tolerance supports stable power conversion. The 1000 MV segment addresses heavy industrial and HVDC applications. Utilities and large plants prefer this category. It supports long duty cycles under extreme conditions.
- For instance, Hitachi Energy deploys ultra-high power thyristors in HVDC systems designed for continuous operation under extreme electrical stress.
By Device Type
Silicon-Controlled Rectifiers hold wide adoption due to cost efficiency. SCRs support rectification and motor control uses. Gate Turn-Off Thyristors serve advanced traction and power systems. GTOs enable controlled turn-off under high power. Bidirectional Triacs support AC switching in appliances. Reverse Conducting Thyristors reduce circuit complexity. Asymmetric Thyristors support high voltage DC transmission. Device choice depends on control and load needs.
- For instance, STMicroelectronics supplies industrial-grade SCRs widely used in motor drives and controlled rectifiers across manufacturing plants worldwide.
By Mounting and Package
Stud-Type packages support mechanical stability and easy replacement. Capsule and Disc formats handle very high currents. SMD and Clip-mount designs suit compact electronics. Module packages support integrated thermal management. Packaging choice influences cooling and installation ease. Equipment design guides package selection.
By Triggering Method
Electrical gate triggered thyristors dominate standard systems. Light Triggered devices support high voltage isolation. Pulse transformer triggering supports noise sensitive systems. Triggering choice affects safety and control accuracy.
By End User
Industrial users lead demand due to heavy power needs. Automotive uses support power control modules. Telecommunication systems rely on stable switching. Consumer electronics favor compact designs. Aerospace and defence demand high reliability.
Segmentation:
By Power Rating
- 500 MV
- 500 MV–1000 MV
- 1000 MV
- Silicon-Controlled Rectifier (SCR)
- Gate Turn-Off Thyristor (GTO)
- Bidirectional Triac
- Reverse Conducting Thyristor
- Asymmetric Thyristor (ASCR)
- Stud-Type
- Capsule/Disc
- SMD and Clip-mount
- Module
- Electrical Gate Triggered
- Light Triggered (LTT)
- Pulse Transformer Triggered
- Consumer Electronics
- Telecommunication & Networking
- Industrial
- Automotive
- Aerospace & Defence
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America Global Thyristor Market size was valued at USD 358.83 million in 2018 to USD 397.78 million in 2024 and is anticipated to reach USD 566.77 million by 2032, at a CAGR of 4.6 during the forecast period. North America holds nearly 26% market share. The Global Thyristor Market in North America benefits from strong industrial automation demand. Power utilities invest in grid modernization projects. Rail and metro upgrades support traction system demand. Manufacturing plants rely on stable power control devices. Electric vehicle infrastructure supports power electronics use. Defence and aerospace sectors demand high reliability components. Mature semiconductor supply chains support steady production. It maintains stable demand across core applications.
Europe
The Europe Global Thyristor Market size was valued at USD 288.36 million in 2018 to USD 309.49 million in 2024 and is anticipated to reach USD 411.34 million by 2032, at a CAGR of 3.7 during the forecast period. Europe accounts for about 20% market share. The Global Thyristor Market in Europe reflects strong industrial standards. Germany and France lead through automation investments. Renewable energy integration drives grid upgrades. Rail electrification projects sustain component demand. Power quality regulations support controlled rectifier use. Industrial retrofitting supports replacement cycles. Local manufacturers focus on efficiency improvements. It shows balanced growth across sectors.
Asia Pacific
The Asia Pacific Global Thyristor Market size was valued at USD 577.80 million in 2018 to USD 667.82 million in 2024 and is anticipated to reach USD 1,010.79 million by 2032, at a CAGR of 5.4 during the forecast period. Asia Pacific holds nearly 44% market share. The Global Thyristor Market in Asia Pacific leads due to scale. China dominates through power infrastructure expansion. India supports demand via rail and grid projects. Japan and South Korea rely on advanced electronics manufacturing. Industrial capacity growth sustains volume demand. Urban transport investments support traction systems. Cost efficient production strengthens regional supply. It remains the fastest growing region.
Latin America
The Latin America Global Thyristor Market size was valued at USD 78.30 million in 2018 to USD 87.33 million in 2024 and is anticipated to reach USD 114.85 million by 2032, at a CAGR of 3.6 during the forecast period. Latin America holds about 6% market share. The Global Thyristor Market in Latin America grows with infrastructure development. Brazil leads through industrial modernization. Power grid stability remains a priority. Mining and metals drive high load equipment use. Rail upgrades support traction demand. Import dependence shapes supply dynamics. Government projects influence procurement cycles. It shows gradual and steady expansion.
Middle East
The Middle East Global Thyristor Market size was valued at USD 28.35 million in 2018 to USD 28.30 million in 2024 and is anticipated to reach USD 32.81 million by 2032, at a CAGR of 2.0 during the forecast period. The region holds nearly 2% market share. The Global Thyristor Market in the Middle East depends on utilities. Grid reliability projects support controlled power systems. Oil and gas facilities require robust electronics. Infrastructure investments remain selective. Import reliance affects pricing structures. Industrial diversification supports limited growth. Power quality remains a focus area. It shows cautious demand patterns.
Africa
The Africa Global Thyristor Market size was valued at USD 18.36 million in 2018 to USD 31.05 million in 2024 and is anticipated to reach USD 35.78 million by 2032, at a CAGR of 1.3 during the forecast period. Africa holds around 2% market share. The Global Thyristor Market in Africa reflects early stage adoption. Grid expansion projects drive basic demand. South Africa leads through industrial activity. Power reliability challenges support control system use. Import dependence shapes availability. Infrastructure funding limits rapid growth. Utility upgrades influence procurement decisions. It shows long term potential with gradual progress.
Key Player Analysis:
- ABB Ltd
- Siemens AG
- Schneider Electric SE
- Eaton Corporation Plc.
- Honeywell International Inc.
- Analog Devices, Inc.
- STMicroelectronics N.V.
- Infineon Technologies AG
- ON Semiconductor
- Fuji Electric Co., Ltd.
- Mitsubishi Electric
- Nihon Inter Electronics Corporation
Competitive Analysis:
The Global Thyristor Market shows a consolidated competitive structure with strong global players. Large manufacturers focus on power electronics portfolios and long term customer contracts. Companies invest in product reliability and thermal performance improvement. Portfolio depth across power ratings strengthens market position. Strategic focus remains on industrial, grid, and traction applications. Established brands benefit from strong certification records. Manufacturing scale supports cost efficiency. Regional presence improves customer proximity. It favors players with integrated semiconductor capabilities. Competition centers on durability, voltage handling, and system compatibility. Partnerships with utilities and OEMs support demand stability. Market leaders protect share through technology upgrades.
Recent Developments:
- In October 2025, Siemens launched the Sinamics S220, a new high-performance drive system designed to meet the demands of digital transformation in industrial automation. This system features a new control unit (CU320-3) and integrates seamlessly into the Siemens Xcelerator portfolio, offering enhanced simulation and analysis capabilities. The S220 system includes regenerative active infeeds and is built on a safety architecture that reduces cycle times from 12 ms to 4 ms, significantly improving productivity and safety for high-power industrial applications.
- In October 2025, Schneider Electric showcased its "2025 Offerings," which included the expansion of its medium voltage drive portfolio with the Altivar Process ATV6100. Designed for energy-intensive industries like mining, minerals, and metals, this drive system features a compact footprint and optimized design to improve asset management and energy efficiency. The system supports predictive maintenance through the new Altivar Predict sensor-less monitoring technology, which uses advanced algorithms to detect faults early and optimize the performance of power control applications.
- In October 2025, Eaton unveiled the 9395 XR Uninterruptible Power Supply (UPS) system at the Elecrama event, positioning it as a flagship solution for mission-critical infrastructure. This advanced power backup system is designed to maximize energy efficiency and reliability for data centers and industrial facilities, addressing the growing global demand for robust power management. The launch underscores Eaton's focus on high-power density solutions that support the transition to renewable energy and stable grid operations.
Report Coverage:
The research report offers an in-depth analysis based on By Power Rating, By Device Type, By Mounting and Package, By Triggering Method, By End User, and By Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Grid modernization initiatives will continue to drive steady demand for thyristor-based power control systems.
- Industrial automation expansion will increase the need for reliable high-current switching devices.
- Rail electrification programs will support long-term adoption of high power thyristors.
- Renewable energy integration will strengthen demand for stable grid-level power electronics.
- Manufacturers will focus on improving thermal performance and operational reliability.
- Asia Pacific will maintain leadership due to strong infrastructure and manufacturing activity.
- Modular and integrated packaging formats will see wider acceptance across industries.
- Compliance with global safety and performance standards will influence supplier selection.
- Hybrid power architectures will shape future system design and component integration.
- Long equipment lifecycles will support sustained replacement and retrofit demand.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Demand for Reliable Power Control Across Industrial Systems
Industrial sectors such as steel, cement, and mining require stable and robust power control for heavy equipment, driving adoption of thyristors due to their high load tolerance and long service life. This supports efficiency and reduces equipment downtime, making thyristors a preferred choice for industrial automation and modernization.
Expansion of Electric Rail and Urban Transit Infrastructure
The global push for urbanization and sustainable transport is fueling investments in electric rail and metro systems, which rely on thyristors for reliable traction power conversion and voltage control. Ongoing rail electrification projects in Asia Pacific and Europe are particularly boosting demand.
Growing Deployment of High Voltage Direct Current (HVDC) Transmission
Utilities and grid operators are expanding HVDC links to improve long-distance power transmission efficiency and grid stability. Thyristors are essential for precise power switching in these systems, supporting modernization and cross-border energy trade.
Increasing Use in Heavy Duty Motor Drives and Industrial Equipment
Industrial automation and the need for accurate speed and torque control in motor drives are increasing the use of thyristors. Their ability to handle high currents and provide stable performance under demanding conditions makes them vital for sectors like oil & gas, marine, and manufacturing.
Expansion of Renewable Energy Grid Infrastructure Projects
The integration of renewable energy sources such as wind and solar into power grids requires stable and durable power conversion devices. Thyristors are widely adopted for voltage control and grid balancing in large-scale renewable projects, supporting the global energy transition.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Global Thyristor Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Global Thyristor Market projected to grow between 2025 and 2032?
Which Global Thyristor Market market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Global Thyristor Market?
Who are the leading companies in the Global Thyristor Market?
Which region commanded the largest share of the Global Thyristor Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Industrial
- 1.2.2 Consumer Electronics
- 1.2.3 Telecommunication & Networking
- 1.2.4 Automotive
- 1.2.5 Aerospace & Defence
- 1.3 By Device Type
- 1.3.1 Silicon-Controlled Rectifier (SCR)
- 1.3.2 Gate Turn-Off Thyristor (GTO)
- 1.3.3 Bidirectional Triac
- 1.3.4 Reverse Conducting Thyristor
- 1.3.5 Asymmetric Thyristor (ASCR)
- 1.4 By Power Rating
- 1.4.1 500 MV
- 1.4.2 500 MV–1000 MV
- 1.4.3 1000 MV
- 1.5 By Triggering Method
- 1.5.1 Electrical Gate Triggered
- 1.5.2 Light Triggered (LTT)
- 1.5.3 Pulse Transformer Triggered
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,521.77 million → 2032: USD 2,172.33 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Thyristor Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Thyristor Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Thyristor Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Thyristor Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Thyristor Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Thyristor Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Thyristor Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Thyristor Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,521.77 million → 2032: USD 2,172.33 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Thyristor Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Industrial
- 12.3.7.2 Consumer Electronics
- 12.3.7.3 Telecommunication & Networking
- 12.3.7.4 Automotive
- 12.3.7.5 Aerospace & Defence
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Device Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Silicon-Controlled Rectifier (SCR)
- 12.4.7.2 Gate Turn-Off Thyristor (GTO)
- 12.4.7.3 Bidirectional Triac
- 12.4.7.4 Reverse Conducting Thyristor
- 12.4.7.5 Asymmetric Thyristor (ASCR)
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Power Rating - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 500 MV
- 12.5.7.2 500 MV–1000 MV
- 12.5.7.3 1000 MV
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Triggering Method - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Electrical Gate Triggered
- 12.6.7.2 Light Triggered (LTT)
- 12.6.7.3 Pulse Transformer Triggered
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Thyristor End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Thyristor Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Thyristor Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Thyristor Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 ABB Ltd
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Siemens AG
- 18.4 Schneider Electric SE
- 18.5 Eaton Corporation Plc.
- 18.6 Honeywell International Inc.
- 18.7 STMicroelectronics N.V.
- 18.8 Infineon Technologies AG
- 18.9 ON Semiconductor
- 18.10 Fuji Electric Co., Ltd.
- 18.11 Mitsubishi Electric
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

