
Market Overview:
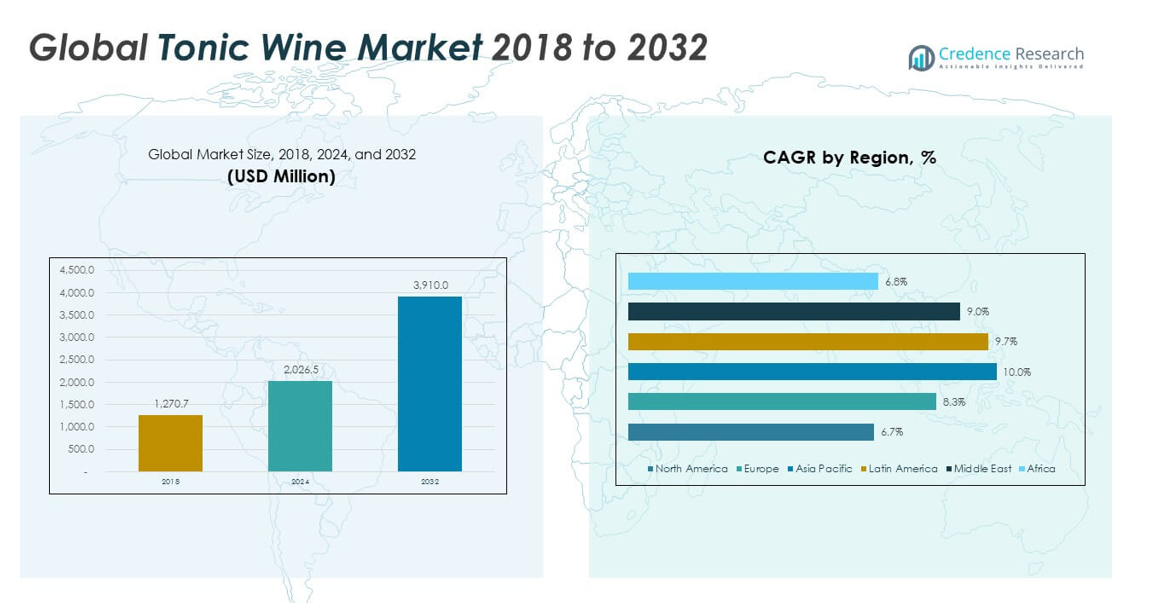
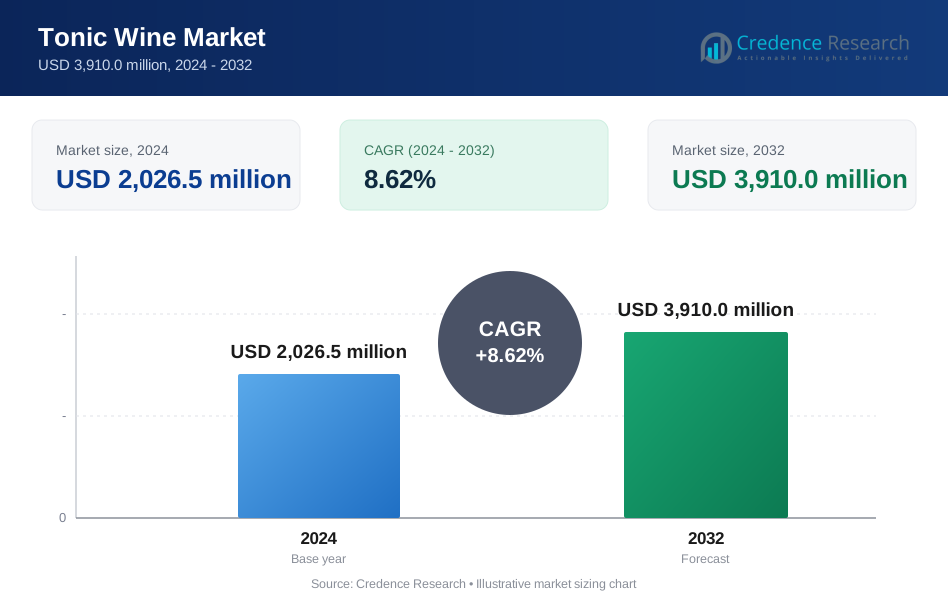
The Global Tonic Wine Market size was valued at USD 1,270.7 million in 2018 to USD 2,026.5 million in 2024 and is anticipated to reach USD 3,910.0 million by 2032, at a CAGR of 8.62% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Tonic Wine Market Size 2024 | USD 2,026.5 million |
| Tonic Wine Market, CAGR | 8.62% |
| Tonic Wine Market Size 2032 | USD 3,910.0 million |
The market is expanding due to rising consumer interest in functional alcoholic beverages that combine traditional wine appeal with added health-related benefits. Demand is driven by wellness-oriented formulations, herbal infusions, and fortified blends that attract both younger consumers and health-conscious buyers. Innovation in flavors, premium product lines, and attractive packaging enhance market presence. Strong marketing campaigns and brand positioning also contribute to sustained growth by appealing to modern lifestyle preferences.
Regionally, Europe leads the Global Tonic Wine Market due to its strong heritage of fortified and herbal wines and well-established distribution channels. North America follows with steady growth supported by premiumization and wellness-driven consumption patterns. Asia Pacific is emerging rapidly, driven by rising disposable income, urbanization, and increasing exposure to international beverage trends. Latin America and the Middle East show growing opportunities as consumer preferences shift toward diverse alcoholic options, while Africa demonstrates steady progress fueled by urban expansion and tourism.
Market Insights:
- The Global Tonic Wine Market size was USD 1,270.7 million in 2018, reached USD 2,026.5 million in 2024, and is projected at USD 3,910.0 million by 2032, growing at a CAGR of 8.62%.
- Europe leads with a 29.4% share, driven by cultural heritage and strong distribution, followed by Asia Pacific at 32.5% with expanding urbanization, and North America at 21.6% with premiumization trends.
- Asia Pacific is the fastest-growing region with 32.5% share, fueled by rising disposable incomes, demographic shifts, and increasing exposure to global beverage trends.
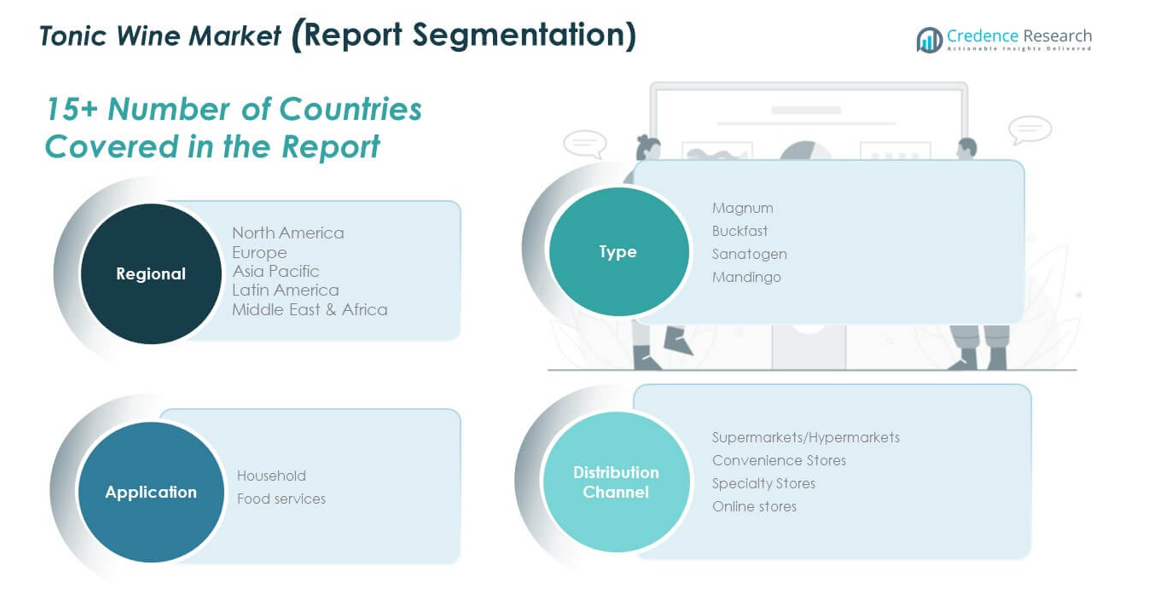
- Household applications contribute 56% of the Global Tonic Wine Market share in 2024, reflecting strong demand from individual consumers.
- Food services hold 44% share, supported by restaurants, pubs, and bars integrating tonic wines into menus to meet evolving consumer preferences.
Market Drivers
Rising Preference For Functional And Fortified Alcoholic Beverages
Consumers are increasingly drawn to alcoholic beverages that offer added health-related benefits. The Global Tonic Wine Market benefits from this shift, with products blending herbal infusions, vitamins, or energy-boosting elements gaining acceptance. It appeals to younger demographics who prefer novelty and wellness combined in alcoholic options. Premium fortified wines with natural extracts encourage higher spending among urban populations. Producers invest in unique formulations to differentiate from traditional wine segments. This consumer behavior directly supports product innovation and premiumization. New entrants focus on functional positioning to capture market share. The trend continues to influence product launches globally.
- For instance, in September 2025, Sunstone Winery launched SOLIS™, a sparkling non-alcoholic functional beverage developed with InfusedBySplash™, featuring Lion’s Mane, Cordyceps, Yerba Mate, L-Theanine, and Alpha GPC to support mental clarity and focus.
Expansion Of Distribution Networks Across On-Trade And Off-Trade Channels
The distribution landscape plays a critical role in market growth. Large retail chains, specialty liquor stores, and online platforms strengthen access to tonic wine. The Global Tonic Wine Market gains momentum with strategic placements in supermarkets and convenience outlets. It also thrives in restaurants, bars, and nightlife venues where experimentation drives trial. Expanding e-commerce penetration widens consumer reach, especially among younger buyers. Partnerships between manufacturers and retailers provide enhanced shelf visibility. Cross-promotions with lifestyle products raise consumer awareness further. Stronger distribution directly correlates with higher sales volumes and broader adoption across regions.
Influence Of Cultural Heritage And Traditional Consumption Practices
Tonic wines hold cultural significance in several regions where herbal-infused wines have long-standing traditions. The Global Tonic Wine Market benefits from this heritage as established consumption practices support sustained demand. It resonates particularly well in Europe and the Caribbean, where such beverages form part of social and cultural rituals. Local producers capitalize on these traditions while modernizing flavors for new audiences. Growing tourism exposes international consumers to tonic wines through authentic experiences. This cultural integration strengthens brand loyalty and repeat purchases. Producers highlight historical origins in their branding strategies. Heritage-driven identity acts as a unique competitive advantage.
- For instance, The Heritage Winery, an Ethiopian family-owned company based in the U.S., produces authentic Tej (Ethiopian honey wine) using ancestral recipes and natural methods without added sulfites or preservatives.
Growing Investment In Marketing And Brand Positioning Strategies
Aggressive marketing plays a major role in shaping consumer perception. The Global Tonic Wine Market expands through campaigns emphasizing vitality, energy, and wellness appeal. It benefits from celebrity endorsements, lifestyle collaborations, and social media-driven engagement. Creative advertising differentiates tonic wine from conventional alcoholic drinks. Companies invest in storytelling and visual branding to connect emotionally with consumers. Packaging innovations also reinforce premium positioning and product authenticity. Regional festivals and sponsorships provide platforms to showcase new variants. These initiatives strengthen recognition and boost brand equity over time.
Market Trends
Emergence Of Premium And Flavored Tonic Wine Variants Across Global Markets
Producers introduce premium and flavored offerings to capture consumer attention. The Global Tonic Wine Market adapts to evolving taste preferences with fruit, spice, and herbal-infused profiles. It reflects the willingness of buyers to experiment with bold flavors in alcohol. Premium versions attract higher-income segments who view these drinks as lifestyle symbols. Limited editions and seasonal launches create exclusivity and demand spikes. Flavor innovation also helps brands position themselves as contemporary and appealing to younger consumers. These variants are increasingly featured in both traditional retail and digital marketplaces. The trend continues to strengthen premium growth in the sector.
Adoption Of Sustainable Production And Eco-Friendly Packaging Initiatives
Sustainability becomes a defining trend across alcoholic beverage categories. The Global Tonic Wine Market aligns with this shift through eco-conscious sourcing and recyclable packaging. It reflects consumer expectations for ethical practices in product creation. Producers experiment with biodegradable materials and lightweight bottles to reduce environmental impact. Organic herbal infusions also gain traction as natural alternatives. Transparency in sourcing and sustainable claims enhance brand credibility. Regulatory pressures further accelerate adoption of green practices. Environmental stewardship strengthens appeal among eco-conscious millennials and Gen Z buyers.
- For instance, in April 2024, Clos du Val winery in California launched its Napa Valley Sauvignon Blanc and Rosé in bottles that are 30% lighter than the previous design, reducing carbon emissions from glass production by 34%, and eliminated foil capsules to minimize environmental impact.
Integration Of Tonic Wines Into Modern Lifestyle And Social Consumption Patterns
Changing lifestyles reshape drinking behaviors globally. The Global Tonic Wine Market responds to increasing demand for versatile beverages suited for social settings. It appeals to urban consumers who enjoy experimenting with wellness-inspired alcoholic options. Festivals, clubs, and themed events often showcase tonic wine as a distinctive choice. Ready-to-drink formats simplify consumption and expand usage occasions. Marketing links tonic wine to fitness, relaxation, and leisure lifestyles. Celebrity-driven campaigns reinforce aspirational value and trend adoption. This integration drives acceptance beyond traditional consumers into mainstream categories.
Influence Of Digital Platforms And Data-Driven Consumer Engagement Strategies
Technology plays a key role in shaping beverage markets. The Global Tonic Wine Market leverages digital platforms for promotion, distribution, and consumer interaction. It benefits from targeted campaigns using analytics and behavioral insights. Brands utilize e-commerce sites and social media channels for personalized engagement. Virtual tasting sessions and influencer marketing increase awareness. Digital tracking tools help producers identify emerging preferences quickly. Online feedback also informs flavor development and packaging changes. These practices allow companies to stay relevant in competitive markets. Digital-first strategies shape long-term positioning and revenue growth.
- For instance, Barrels Ahead highlighted in 2024 that wineries are adopting AI-powered recommendation engines to deliver personalized wine suggestions, while also using AI chatbots to provide 24/7 customer engagement and support.
Market Challenges Analysis
Regulatory Restrictions And Varying Legal Frameworks Across Markets
Regulatory hurdles present a major challenge for industry participants. The Global Tonic Wine Market faces restrictions on labeling, advertising, and permissible formulations. It must comply with varying alcohol laws across regions, which complicates product launches. Producers navigate stringent guidelines on herbal content and health claims. Governments often impose taxes and duties that reduce price competitiveness. Smaller manufacturers struggle with compliance costs, limiting their ability to scale. Constantly changing rules create uncertainty in long-term planning. This fragmented regulatory environment slows down consistent expansion strategies.
Shifting Consumer Perceptions And Rising Competition From Alternative Beverages
Consumer perception of tonic wine varies significantly across markets. The Global Tonic Wine Market competes with alternatives such as craft beers, energy drinks, and low-alcohol cocktails. It risks being seen as niche compared to mainstream options. Negative health perceptions tied to alcohol also influence buying decisions. Younger demographics often lean toward low-calorie or non-alcoholic choices. Strong competition from premium spirits further limits tonic wine’s appeal in certain regions. Marketing investments must address these perceptions to sustain demand. Without constant innovation, it risks losing relevance in a crowded beverage space.
Market Opportunities
Expansion Into Emerging Markets With Rising Middle-Class Consumers
Growth opportunities lie in developing regions where disposable income is rising. The Global Tonic Wine Market finds strong potential in Asia-Pacific, Africa, and Latin America. It benefits from young populations seeking novel drinking experiences. Urbanization exposes consumers to premium and international beverage options. Tourism-driven consumption also supports product entry in new markets. Partnerships with local distributors create efficient access points. E-commerce further accelerates penetration in previously untapped regions. These conditions create fertile ground for future growth.
Innovation Through Functional Ingredients And Cross-Category Collaborations
Brands have significant scope to innovate by integrating functional elements into tonic wines. The Global Tonic Wine Market can incorporate superfoods, botanicals, or adaptogens to appeal to wellness-driven buyers. It benefits from collaborations with health-focused brands to build credibility. Limited-edition launches combining herbal extracts with exotic flavors enhance differentiation. Cross-category partnerships with fitness, hospitality, or luxury sectors expand visibility. Experimentation with low-alcohol and zero-sugar versions attracts health-conscious audiences. This innovation-driven strategy positions tonic wine as both trendy and versatile.
Market Segmentation Analysis:
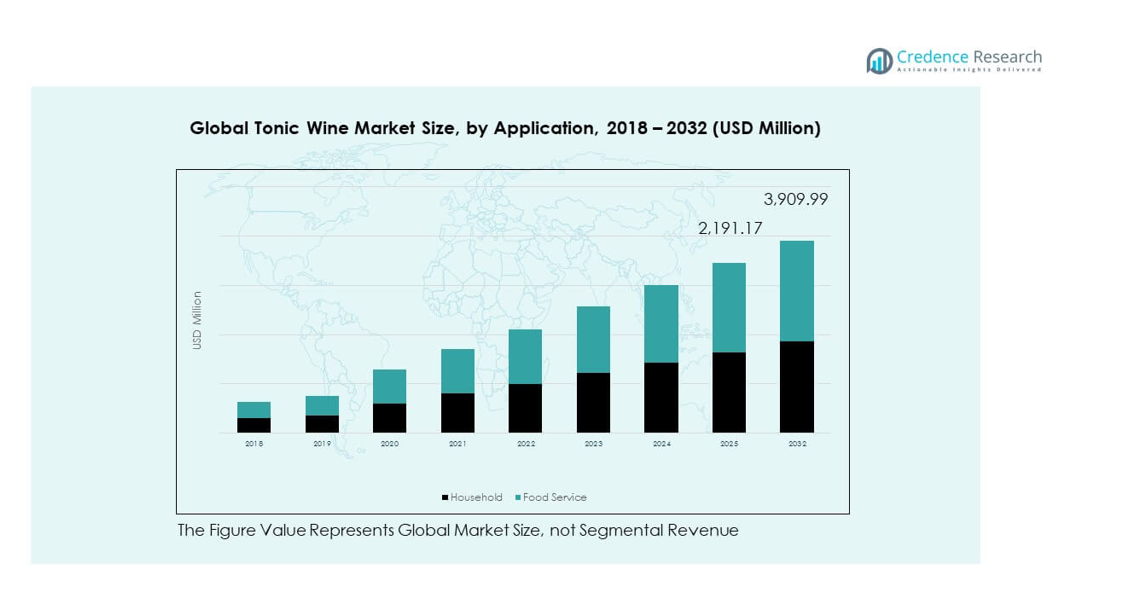
By type, the Global Tonic Wine Market is dominated by Magnum, supported by its strong consumer base and brand legacy. Buckfast holds significant traction in Europe, particularly within the UK and Ireland, due to its cultural recognition and loyal customer segment. Sanatogen appeals to consumers seeking fortified formulations positioned around wellness attributes, while Mandingo captures niche demand through unique branding and flavor positioning. It reflects how established names and specialized offerings together shape competitive dynamics across the type segment.
- For instance, in March 2025, Campari Group announced a unified packaging redesign for Magnum Tonic Wine across the UK and Jamaica, eliminating consumer confusion between the markets and ensuring consistent brand identity, with all production continuing in Jamaica, as reported by the brand’s official statement and major UK retailers.
By application, household consumption remains the leading segment, supported by rising awareness of functional and fortified beverages among individual buyers. Food services are expanding steadily, with restaurants, pubs, and bars incorporating tonic wines into menus to meet evolving consumer preferences. This diversification of demand highlights the market’s adaptability across both personal and commercial consumption.
- For example, Buckfast introduced ready-to-drink canned products in April 2024, offering Original (15% ABV) and Buckfast & Lemonade (5% ABV) in 250 ml formats. These launched through major Scottish wholesalers and convenience retailers, as confirmed by industry reports.
By distribution channel, supermarkets and hypermarkets retain the largest share due to their broad product visibility and consumer trust. Convenience stores contribute through accessible purchases in both urban and semi-urban areas. Specialty stores emphasize premium and flavored offerings that appeal to niche buyers. Online stores are expanding quickly, benefiting from digital marketing, younger demographics, and ease of direct-to-consumer delivery. It highlights how retail diversification continues to drive accessibility and market penetration.
Segmentation:
By Type
- Magnum
- Buckfast
- Sanatogen
- Mandingo
By Application
- Household
- Food Services
By Distribution Channel
- Supermarkets/Hypermarkets
- Convenience Stores
- Specialty Stores
- Online Stores
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis:
North America
The North America Global Tonic Wine Market size was valued at USD 302.16 million in 2018 to USD 437.52 million in 2024 and is anticipated to reach USD 730.00 million by 2032, at a CAGR of 6.7% during the forecast period. North America accounts for 21.6% of the Global Tonic Wine Market share. The region benefits from strong consumer awareness regarding premium alcoholic beverages. It emphasizes health-oriented wine variants blended with herbs and functional ingredients. Distribution through supermarkets and online platforms ensures wide accessibility. Younger demographics contribute to rising demand with interest in flavored and low-alcohol options. Innovation in packaging enhances brand visibility in competitive spaces. Manufacturers rely on marketing campaigns that link tonic wines to modern lifestyles. Regional growth remains stable due to the mature nature of alcohol markets in the U.S. and Canada.
Europe
The Europe Global Tonic Wine Market size was valued at USD 380.18 million in 2018 to USD 596.26 million in 2024 and is anticipated to reach USD 1,124.51 million by 2032, at a CAGR of 8.3% during the forecast period. Europe accounts for 29.4% of the Global Tonic Wine Market share. The region leads due to its heritage of fortified and herbal-infused wines. It benefits from strong cultural traditions, particularly in the UK, Germany, and France. Premiumization trends support robust demand for flavored and high-quality tonic wines. Distribution networks are well established, including on-trade channels like pubs and restaurants. Tourism boosts sales by introducing international visitors to authentic tonic wine experiences. Marketing strategies often highlight historical roots to reinforce authenticity. It remains the largest market, supported by both tradition and modern consumer preferences.
Asia Pacific
The Asia Pacific Global Tonic Wine Market size was valued at USD 381.20 million in 2018 to USD 659.20 million in 2024 and is anticipated to reach USD 1,403.69 million by 2032, at a CAGR of 10.0% during the forecast period. Asia Pacific accounts for 32.5% of the Global Tonic Wine Market share. The region shows strong growth driven by expanding middle-class populations. Urbanization exposes consumers to international beverage options. Rising disposable income fuels demand for premium alcoholic products. Younger populations experiment with flavored tonic wines that align with social drinking trends. Online platforms strengthen distribution and consumer access. Countries like China, Japan, and India emerge as key growth engines. It demonstrates the fastest growth trajectory globally, supported by demographic shifts and evolving lifestyles.
Latin America
The Latin America Global Tonic Wine Market size was valued at USD 87.68 million in 2018 to USD 149.38 million in 2024 and is anticipated to reach USD 312.80 million by 2032, at a CAGR of 9.7% during the forecast period. Latin America accounts for 7.3% of the Global Tonic Wine Market share. The region witnesses growing demand among urban consumers exploring new alcoholic experiences. Rising influence of international brands strengthens market penetration. Retail channels and e-commerce platforms support accessibility across Brazil, Argentina, and Mexico. Flavored and fortified wines resonate with younger audiences seeking novelty. Marketing campaigns often associate tonic wines with modern social gatherings. Strong tourism in Brazil further aids product awareness. It presents opportunities for both global and local producers to expand their presence.
Middle East
The Middle East Global Tonic Wine Market size was valued at USD 60.74 million in 2018 to USD 98.78 million in 2024 and is anticipated to reach USD 195.50 million by 2032, at a CAGR of 9.0% during the forecast period. The Middle East accounts for 4.9% of the Global Tonic Wine Market share. Growth is influenced by increasing demand in tourism-driven economies. Hospitality and luxury dining venues play a central role in introducing tonic wines. Premium positioning aligns well with affluent consumers. Strict alcohol regulations in some countries limit availability, yet GCC nations show steady progress. Marketing focuses on exclusivity and lifestyle appeal. Imports dominate the regional supply due to limited local production. It remains a niche but expanding market segment in the region.
Africa
The Africa Global Tonic Wine Market size was valued at USD 58.70 million in 2018 to USD 85.37 million in 2024 and is anticipated to reach USD 143.50 million by 2032, at a CAGR of 6.8% during the forecast period. Africa accounts for 4.2% of the Global Tonic Wine Market share. The region demonstrates potential through rising urbanization and disposable income growth. Younger populations show interest in experimenting with flavored alcoholic options. Distribution remains limited in rural areas but expands steadily in urban centers. South Africa leads due to an established wine industry and strong retail channels. Nigeria and Egypt also emerge as important contributors. International brands seek partnerships with local distributors to enhance penetration. It continues to grow steadily despite infrastructural and regulatory challenges.
Key Player Analysis:
- Bristol
- Mellasat Vineyard
- Rémy Cointreau SA
- The Carlyle Group
- Campari Group
- Frederiksda
- Constellation Brands, Inc.
- Portman Group
- Macleod Distillers
- Other Key Players
Competitive Analysis:
The Global Tonic Wine Market features a mix of established international brands and regional producers competing for consumer attention. It is characterized by strong brand recognition, heritage-based marketing, and product innovation. Leading players such as Bristol, Macleod Distillers, Rémy Cointreau SA, and Constellation Brands focus on premiumization, flavored variants, and distribution expansion. Regional firms emphasize cultural traditions and localized flavors to maintain loyalty. Competitive strategies include acquisitions, partnerships with retail chains, and investments in eco-friendly packaging. It relies on digital platforms and social media to strengthen consumer engagement. Market consolidation is evident, with global companies expanding into high-growth regions. The competitive landscape continues to evolve with emphasis on brand differentiation, functional ingredients, and positioning strategies that align with changing consumer preferences.
Recent Developments:
- In July 2025, Rémy Cointreau Corporate Ventures acquired a minority stake in JNPR, an innovative French company specializing in non-alcoholic spirits. This partnership intends to accelerate development in France and select international markets and supports emerging consumption trends focused on alcohol-free alternatives.
- In July 2025, the Aquila Collection completed the acquisition of Mellasat Vineyards, restoring the historic Dekkersvlei name to this renowned South African winery. The move reinforces Aquila's portfolio and celebrates Mellasat's legacy, particularly its innovative take on South Africa’s white pinotage offering.
Report Coverage:
The research report offers an in-depth analysis based on Type, Application and Distribution Channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising consumer demand for functional alcoholic beverages will continue to support tonic wine adoption.
- Product innovation with herbal infusions and premium blends will attract health-conscious consumers.
- Expansion of online retail platforms will improve accessibility and drive brand visibility.
- Packaging innovations will enhance product differentiation and reinforce premium positioning.
- Regional growth in Asia Pacific will accelerate with expanding middle-class consumers and urbanization.
- Tourism and hospitality industries will boost global awareness and trial of tonic wines.
- Regulatory adjustments will shape labeling practices and influence product positioning strategies.
- Strategic partnerships with retailers will strengthen distribution across on-trade and off-trade channels.
- Sustainability-driven initiatives will align with consumer expectations for eco-friendly products.
- Digital marketing and influencer collaborations will expand consumer reach and reinforce brand identity.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Global Tonic Wine Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Global Tonic Wine Market projected to grow between 2024 and 2032?
Which Global Tonic Wine Market market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Global Tonic Wine Market?
Who are the leading companies in the Global Tonic Wine Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Tonic Wine Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Tonic Wine Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 2,026.5 million → 2032: USD 3,910.0 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Tonic Wine Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Tonic Wine Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Tonic Wine Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Tonic Wine Market Drivers
- 3.3 Tonic Wine Market Restraints & Challenges
- 3.4 Tonic Wine Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Tonic Wine Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Tonic Wine Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Tonic Wine category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Tonic Wine Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Tonic Wine Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Tonic Wine market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Tonic Wine Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Tonic Wine Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Tonic Wine Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Tonic Wine (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Tonic Wine Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Tonic Wine Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Tonic Wine Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Tonic Wine Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Tonic Wine Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Tonic Wine Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Tonic Wine Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Tonic Wine Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Tonic Wine Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
