
Market Overview:
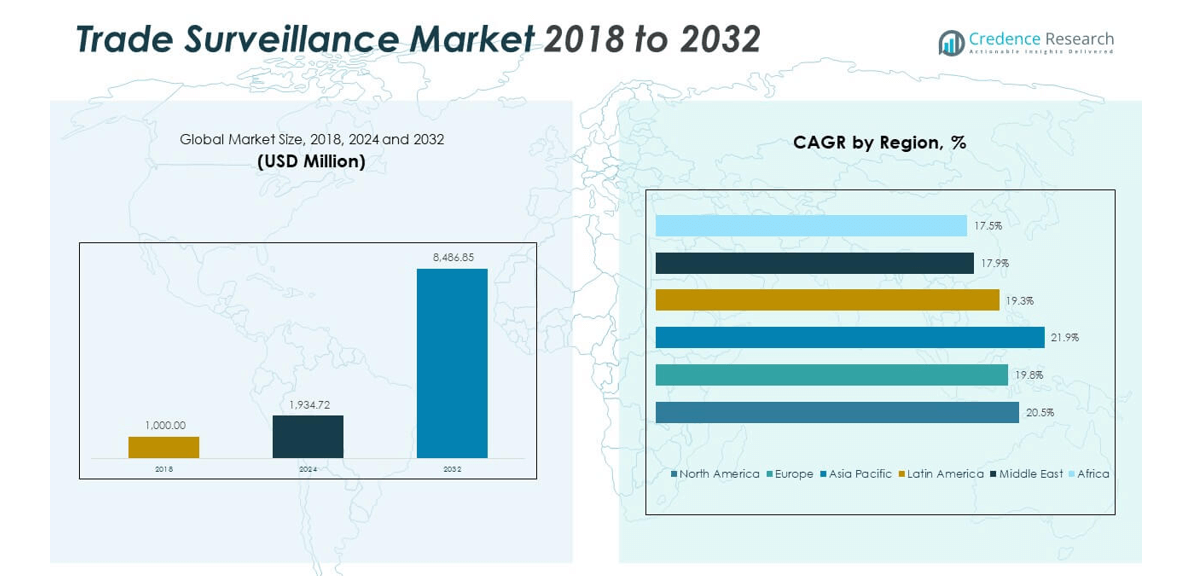
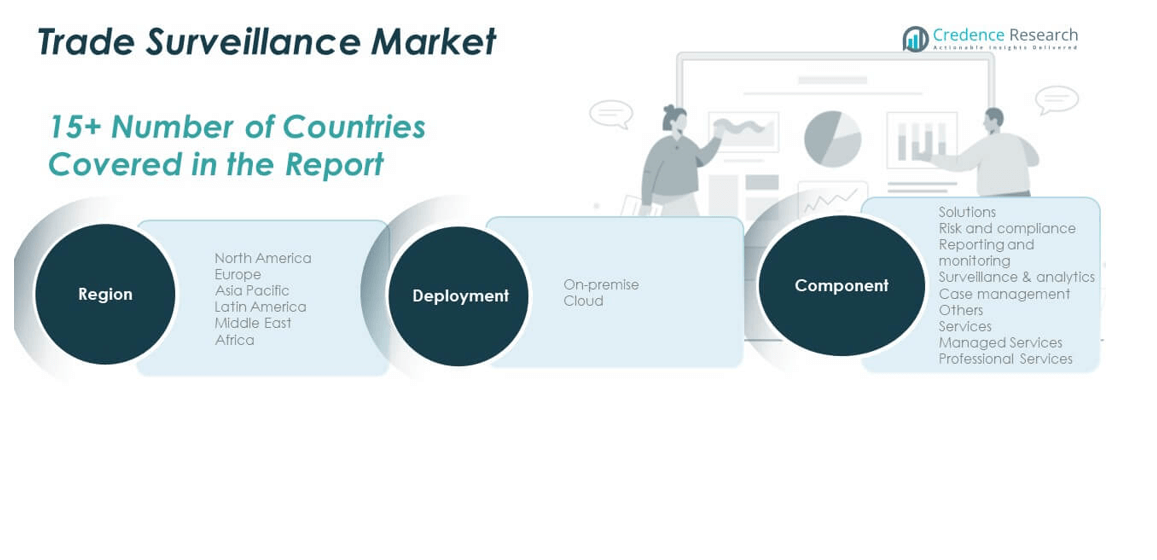
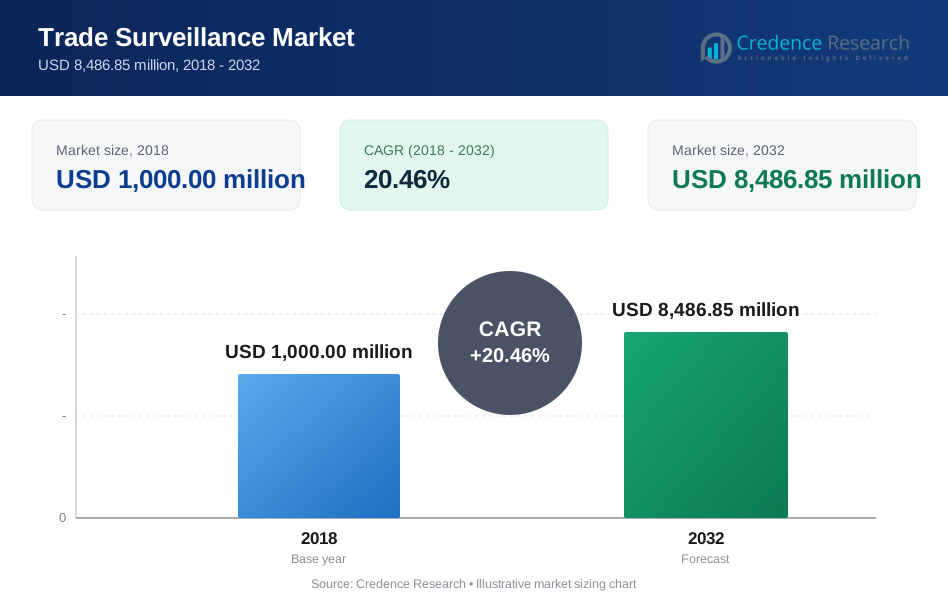
The Global Trade Surveillance Market size was valued at USD 1,000.00 million in 2018 to USD 1,934.72 million in 2024 and is anticipated to reach USD 8,486.85 million by 2032, at a CAGR of 20.46% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Trade Surveillance Market Size 2024 | USD 1,934.72 million |
| Trade Surveillance Market, CAGR | 20.46% |
| Trade Surveillance Market Size 2032 | USD 8,486.85 million |
Demand rises due to stricter market-abuse rules and the growing need for better oversight across trading environments. Financial firms adopt advanced tools that detect insider activity and suspicious patterns. Rising digital trades push firms toward automated checks that offer faster response. AI platforms help identify anomalies that standard methods fail to capture. Cloud systems support wider monitoring across global desks with ease. Firms also invest in tools that blend structured and unstructured data for deeper insight. Strong pressure from regulators keeps adoption stable across sectors.
North America leads the Global Trade Surveillance Market due to strong regulatory frameworks and high investment by major financial institutions. Europe follows due to strict market-abuse directives that require wide monitoring across exchanges. Asia Pacific emerges quickly with rising electronic trading and expanding fintech ecosystems. The Middle East shows progress with modern trading infrastructure and stronger compliance needs. Latin America gains momentum through digital upgrades in major economies. Global momentum stays strong due to fast adoption of automated surveillance tools across cross-border markets.
Market Insights:
- The Global Trade Surveillance Market was USD 1,000.00 million in 2018, reached USD 1,934.72 million in 2024, and is projected to hit USD 8,486.85 million by 2032 at a CAGR of 20.46%, driven by rising digital trades, stricter market-abuse rules, and strong adoption of AI-enabled oversight tools.
- Europe leads with 46% share due to strict directives, followed by North America at 28.03% supported by strong compliance rules, and Asia Pacific at 26.49% driven by heavy digital trading growth; these regions dominate because they hold mature regulatory systems and advanced financial infrastructure.
- Asia Pacific is the fastest-growing region with a 49% share, supported by expanding fintech ecosystems, rising electronic trading, and rapid cloud adoption across major markets.
- Cloud deployment holds the larger share at about 64%, driven by scalable infrastructure and demand for flexible real-time monitoring across global trading desks.
- On-premise deployment represents about 36%, supported by institutions that prioritise strict data control and operate in high-security environments where internal infrastructure remains essential.
Market Drivers:
Growing Regulatory Pressure Across Trading Environments
The Global Trade Surveillance Market grows due to strict rules that demand high transparency. Firms deploy advanced systems to detect unfair trades before risks spread. It supports compliance teams that face rising scrutiny from global regulators. AI models scan large data sets to flag unusual activity with high accuracy. Cloud platforms give faster access to monitoring tools across global desks. Many banks upgrade legacy tools to match new rule changes. Increased digital trades push firms toward automated checks. Strong pressure from oversight bodies keeps adoption steady across sectors.
- For instance, Nasdaq SMARTS is used by more than 47 exchanges and regulators worldwide to detect manipulation across large trade volumes.
Rising Need For Real-Time Risk Detection
Financial institutions seek real-time insight to stop harmful trades before markets shift. It drives fast uptake of systems that analyze orders within seconds. Firms use behavioral maps to detect insider moves earlier. Real-time alerts help teams respond before misconduct grows. Many trading desks rely on automated tools to manage large volumes. Cross-asset monitoring improves risk checks across complex portfolios. High-speed analytics support compliance groups with stronger control. The Global Trade Surveillance Market gains momentum from this rapid shift.
- For instance, NICE Actimize SURVEIL-X processes hundreds of millions of trade and communication events per day to support real-time detection workflows. Real-time alerts help teams respond before misconduct grows.
Expansion Of Digital Trading And Complex Instruments
Digital platforms create higher demand for tools that track complex trade patterns. Firms monitor new asset classes that shift fast across global markets. AI engines handle diverse data and track hidden trends. It improves detection across derivatives, crypto, and structured products. Many firms upgrade tools to manage multi-venue trading. Cross-border flows push firms toward unified oversight. Strong interest in automated checks supports safer digital growth. The Global Trade Surveillance Market sees wide adoption due to this shift.
Growing Focus On Data Integration And Unified Oversight
Trading institutions seek platforms that merge structured and unstructured data. It helps teams track communication trails with trading patterns. Unified dashboards support faster decisions for compliance groups. Machine learning scans voice logs, chat records, and order books. Firms invest in deeper analytics to match rising market complexity. Integrated systems help reduce blind spots across global desks. Automation reduces manual checks and strengthens audit readiness. The Global Trade Surveillance Market gains traction due to this focus.
Market Trends:
Adoption Of AI-Native Surveillance Platforms
AI-native systems become central across trading environments. These tools deliver strong accuracy in detecting hidden patterns. It helps compliance groups track new forms of misconduct. Many desks shift from rule-based engines to learning-based platforms. AI supports deep insight into trader behavior. Automated scoring tools highlight risky conduct with precision. Cloud-native AI improves scale and processing speed. The Global Trade Surveillance Market benefits from this rapid evolution.
- For instance, TradingHub’s TCA analytics platform supports over 100 global financial institutions by running high-speed models that detect anomalous trading behaviors. AI supports deep insight into trader behavior. Automated scoring tools highlight risky conduct with precision.
Wider Use Of NLP For Communication Monitoring
Firms adopt NLP tools to track voice calls, emails, and chat records. NLP engines translate speech patterns into actionable alerts. It helps detect code words and attempts to mask intent. Many desks rely on NLP to link messages with trades. Automated review reduces long manual audits. Cross-language support increases global effectiveness. NLP tools also adapt to new communication channels. The Global Trade Surveillance Market moves toward stronger communication oversight.
- For instance, Bloomberg Vault has archived communications across emails, chats, and voice logs, enabling NLP tools to detect high-risk phrases. Many desks rely on NLP to link messages with trades. Automated review reduces long manual audits.
Shift Toward Cloud-First Deployment Models
Trading firms prefer cloud platforms to support scale and faster updates. It reduces heavy hardware needs across global offices. Cloud systems improve access to surveillance engines during peak loads. Many institutions adopt hybrid models to balance control and flexibility. Secure cloud zones support safe data handling. Faster deployment improves compliance readiness. Upgrades roll out quicker through a centralized setup. The Global Trade Surveillance Market shifts toward cloud adoption at a fast pace.
Integration Of Surveillance With Trade Lifecycle Platforms
Firms blend surveillance tools with order management systems for accuracy. It helps teams detect issues before orders reach execution. Many desks use unified systems to prevent trade mismatches. Lifecycle integration supports a full audit trail for oversight groups. Automation helps maintain clean data across platforms. Integrated workflows reduce process delays. It enhances transparency across pre-trade and post-trade layers. The Global Trade Surveillance Market advances through this tighter integration.
Market Challenges Analysis:
High Complexity In Monitoring Multi-Asset And Cross-Border Trades
The Global Trade Surveillance Market faces rising complexity across diverse asset classes. Firms struggle to track fast flows across global venues. It becomes harder to maintain accuracy when markets shift quickly. Many surveillance models need constant tuning to detect new risks. Cross-border trades introduce rule differences that increase strain. Fragmented data makes oversight difficult for compliance teams. Legacy systems slow down detection across heavy volumes. Many firms invest in upgrades but face long integration cycles.
Cost Pressure And Skill Gaps Across Compliance Teams
Firms face high costs while building advanced surveillance setups. Many teams lack skilled analysts who can manage AI-driven tools. It increases dependence on external partners for key tasks. Slow hiring cycles weaken internal capability. Many institutions struggle to maintain strong coverage across busy desks. It pushes firms to adopt automation but creates training challenges. Complex tools increase learning demands across teams. The Global Trade Surveillance Market experiences these hurdles across regions.
Market Opportunities:
Rising Scope For AI-Enriched Surveillance Across New Asset Classes
The Global Trade Surveillance Market gains new prospects as firms expand into digital assets. AI engines help detect patterns that legacy systems miss. It creates demand for fresh tools across fast-growing markets. Many regulators push firms to adopt stronger oversight. Digital platforms rely on wide monitoring to stay compliant. Firms tap cloud AI to handle global scale. Strong interest in hybrid models opens new growth paths. Wider datasets help improve detection accuracy.
Growth Potential In Emerging Regions With Expanding Trading Activity
Emerging markets show strong interest in modern oversight tools. It creates scope for new deployments across digital exchanges. Many regional desks shift toward automated checks. Local regulators strengthen rules to improve trust. Firms invest in platforms that support multi-language communication tracking. Demand grows for cloud systems with low setup needs. Many providers target these regions with modular offerings. This shift opens wider opportunities for rapid expansion.
Market Segmentation Analysis:
By Component
The Global Trade Surveillance Market expands through strong demand for advanced solutions that support strict oversight needs. Risk and compliance tools help institutions detect unfair practices with high accuracy. Reporting and monitoring platforms improve audit readiness for global regulators. Surveillance and analytics engines track large trade volumes and uncover hidden patterns. Case management systems streamline investigation cycles for compliance teams. Other niche tools support hybrid workflows across trading desks. Services play a key role in guiding firms through complex deployments. Managed services and professional services strengthen system performance across fast-moving environments.
- For instance, Nasdaq SMARTS analyzes billions of market messages per day across its client exchanges to flag anomalies in trading behavior. Case management systems streamline investigation cycles for compliance teams.
By Deployment
Deployment preferences shift toward cloud-based models that offer strong scale and quick updates. It supports firms that handle multi-venue trades and require faster access to analytics. Many institutions use cloud zones to cut hardware load and improve agility. On-premises setups remain important for teams that need full control of sensitive data. These systems support tight governance across high-security environments. Deployment choices vary by region based on regulatory expectations. Cloud adoption grows among firms seeking flexible operating models. Both approaches shape steady progress across the surveillance landscape.
- For instance, NICE Actimize’s cloud-native SURVEIL-X platform is deployed across major global banks and processes hundreds of millions of events daily through scalable cloud infrastructure. On-premises setups remain important for teams that need full control of sensitive data.
Segmentation:
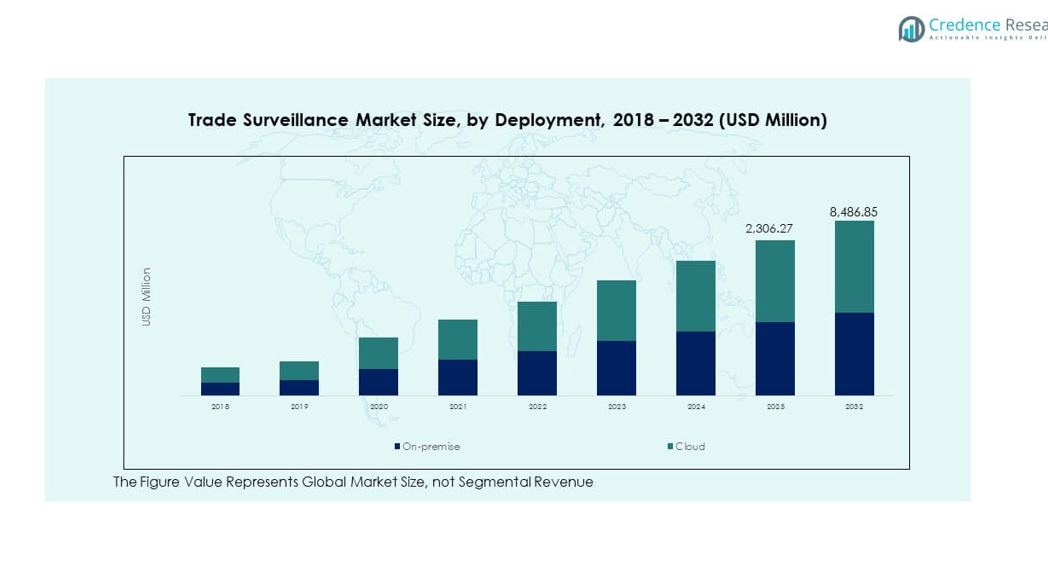
By Component
- Solutions
- Risk and Compliance
- Reporting and Monitoring
- Surveillance & Analytics
- Case Management
- Others
- Services
- Managed Services
- Professional Services
By Deployment
- Cloud Based
- On-Premises
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Southeast Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East
- GCC Countries
- Israel
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
Regional Analysis:
North America
The North America Global Trade Surveillance Market size was valued at USD 284.70 million in 2018 to USD 542.29 million in 2024 and is anticipated to reach USD 2,374.63 million by 2032, at a CAGR of 20.5% during the forecast period. North America holds a market share of 28.03%. The Global Trade Surveillance Market grows in this region due to strong regulatory systems across major exchanges. It benefits from strict laws that demand effective detection of market abuse. Firms enhance oversight tools to manage high electronic trading volumes. AI platforms support early signals that guide teams toward faster action. Cloud adoption rises to boost speed and scalability across trading desks. Many banks replace legacy systems to meet rising oversight pressure. Cross-asset monitoring strengthens detection across diverse instruments. It gains steady demand from firms that seek resilient compliance systems.
Europe
The Europe Global Trade Surveillance Market size was valued at USD 354.80 million in 2018 to USD 666.65 million in 2024 and is anticipated to reach USD 2,805.35 million by 2032, at a CAGR of 19.8% during the forecast period. Europe holds a market share of 34.46%. The Global Trade Surveillance Market expands in Europe due to strict market-abuse rules under regional directives. Firms deploy surveillance tools that help prevent misconduct across large exchanges. Automation improves detection quality during heavy trading cycles. Cloud systems support flexible oversight for multinational institutions. AI-driven systems track complex derivative trades with greater accuracy. Many brokers modernize checks to align with new reporting structures. Cross-border activity pushes demand for unified dashboards. It gains momentum from rising digital trade flows across major economies.
Asia Pacific
The Asia Pacific Global Trade Surveillance Market size was valued at USD 254.00 million in 2018 to USD 512.40 million in 2024 and is anticipated to reach USD 2,472.22 million by 2032, at a CAGR of 21.9% during the forecast period. Asia Pacific holds a market share of 26.49%. The Global Trade Surveillance Market advances in this region due to rapid expansion of digital trading. Growing fintech ecosystems support wider adoption of automated monitoring tools. Many exchanges modernize platforms to handle high-speed trades. AI engines track emerging threats across diverse asset classes. Cloud-first systems gain traction due to lower operating barriers. Regional regulators tighten rules to improve market integrity. Cross-market connectivity drives demand for integrated oversight. It gains strong momentum from rising investor participation across key markets.
Latin America
The Latin America Global Trade Surveillance Market size was valued at USD 62.30 million in 2018 to USD 119.35 million in 2024 and is anticipated to reach USD 485.19 million by 2032, at a CAGR of 19.3% during the forecast period. Latin America holds a market share of 6.17%. The Global Trade Surveillance Market sees gradual progress due to modernization across regional exchanges. Many institutions adopt tools that help detect potential manipulation. Cloud-based systems appeal to firms seeking low-cost upgrades. AI platforms improve visibility across fast-growing trading channels. Regulators strengthen guidelines to raise transparency across markets. Cross-border activities increase demand for structured oversight. Firms enhance reporting structures to improve compliance response. It gains traction as trading becomes more digital across the region.
Middle East
The Middle East Global Trade Surveillance Market size was valued at USD 24.50 million in 2018 to USD 42.74 million in 2024 and is anticipated to reach USD 157.90 million by 2032, at a CAGR of 17.9% during the forecast period. The Middle East holds a market share of 2.21%. The Global Trade Surveillance Market grows in this region due to upgrades in financial infrastructure. Many exchanges deploy stronger tools to align with global norms. AI models support early alerts during market fluctuations. Cloud platforms help institutions modernize oversight with less complexity. Regional regulators push stricter controls across trading venues. Financial hubs invest in integrated systems that improve accuracy. Firms explore analytics engines to handle rising volumes. It continues to expand as more markets digitize operations.
Africa
The Africa Global Trade Surveillance Market size was valued at USD 19.70 million in 2018 to USD 51.28 million in 2024 and is anticipated to reach USD 191.54 million by 2032, at a CAGR of 17.5% during the forecast period. Africa holds a market share of 2.65%. The Global Trade Surveillance Market develops slowly but steadily due to rising digital adoption. Regional exchanges upgrade monitoring systems to improve trust. Firms adopt AI-led tools to strengthen oversight quality. Cloud solutions help lower resource barriers for smaller institutions. Regulatory authorities work toward stronger reporting rules. Many markets seek support for integrated risk detection. Growing investor activity pushes firms to improve controls. It gains regional traction as financial systems modernize.
Key Player Analysis:
- Crisil Limited
- Software GmbH
- Aquis Exchange
- Nexi S.p.A.
- Nasdaq, Inc.
- Scila
- OneMarketData, LLC
- ACA Group
- IPC System, Inc.
- Wipro
- Red Deer
Competitive Analysis:
The Global Trade Surveillance Market features strong competition among technology providers that focus on advanced detection, analytics, and compliance automation. Leading firms integrate AI-driven models that track abnormal behavior across multi-asset environments. Many vendors expand cloud capabilities to support fast deployment across global trading desks. It benefits from rising demand for unified platforms that merge trade data with communication records. Firms compete on speed, accuracy, and workflow automation to serve stricter oversight needs. Providers enhance case management tools to reduce investigation time. Strategic partnerships strengthen integration across trading systems. Vendors maintain active development cycles to address evolving regulatory rules.
Recent Developments:
- In November 2025, TPG, a firm specializing in alternative asset management, made a binding offer of approximately €1 billion for the digital banking solutions unit of Nexi S.p.A., with the payments firm having until mid-December 2025 to decide whether to proceed with the transaction. This follows months of negotiations between the two companies.
- In September 2025, CRISIL announced the acquisition of McKinsey PriceMetrix Co. to strengthen its global benchmarking offerings in wealth management. This strategic acquisition is expected to expand CRISIL's capabilities in the wealth management segment, with the transaction set to be completed in the coming months. The company continues to maintain leadership in corporate bond ratings while focusing on domain-led AI solutions and talent development to drive sustainable growth.
- In July 2025, SIX Group, the Swiss and Spanish financial market infrastructure operator, completed its acquisition of Aquis Exchange. The deal, which was a recommended cash offer, was initially announced in November 2024 when agreed upon by the boards of both companies. While public reports referenced a deal value of approximately £207 million based on the treasury stock methodology, sources also noted a higher value of £225 million on a fully diluted basis.
Report Coverage:
The research report offers an in-depth analysis based on By Component and By Deployment. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- AI-native surveillance engines will drive stronger pattern detection across asset classes.
- Cloud platforms will support wider deployment across fast-growing digital exchanges.
- Real-time alerts will strengthen decision support for compliance teams.
- Communication monitoring will expand through advanced NLP and voice analytics.
- Multi-asset coverage will improve detection accuracy across global venues.
- Hybrid deployment models will help institutions balance security and scale.
- Case management automation will speed investigation cycles.
- Integrated platforms will unify trade data with behavioral insights.
- Regulatory tightening will push faster upgrades across financial institutions.
- Emerging markets will increase adoption as digital trading accelerates.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growing Regulatory Pressure Across Trading Environments
Stricter market-abuse rules and global regulatory scrutiny are compelling financial institutions to adopt advanced trade surveillance systems that ensure compliance and transparency, driving market growth.
Rising Need for Real-Time Risk Detection
The demand for real-time monitoring and rapid response to suspicious trading activities is pushing firms to implement automated, AI-powered surveillance tools that can analyze large volumes of trades and communications instantly.
Expansion of Digital Trading and Complex Instruments
The proliferation of digital trading platforms and the emergence of complex asset classes such as derivatives and cryptocurrencies require sophisticated surveillance solutions capable of tracking diverse and fast-moving market activities.
Shift Toward Cloud-Based and AI-Native Platforms
Financial institutions are increasingly migrating to cloud-based and AI-native surveillance systems for scalability, flexibility, and enhanced detection capabilities, accelerating adoption across global trading desks.
Integration of Structured and Unstructured Data for Unified Oversight
The need to correlate trade data with communication records and behavioral insights is driving investment in platforms that integrate structured and unstructured data, improving detection accuracy and audit readiness.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Trade Surveillance market?
At what Compound Annual Growth Rate is the Global Trade Surveillance Market projected to grow between 2025 and 2032?
What factors are driving the growth of the Trade Surveillance market?
What are some challenges faced by the Trade Surveillance market?
Who are the major players in the Trade Surveillance market?
Which segment is leading the market share?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Component
- 1.2.1 Solutions
- 1.2.2 Risk and Compliance
- 1.2.3 Reporting and Monitoring
- 1.2.4 Surveillance & Analytics
- 1.2.5 Case Management
- 1.2.6 Others
- 1.2.7 Services
- 1.2.8 Managed Services
- 1.2.9 Professional Services
- 1.3 By Deployment
- 1.3.1 Cloud Based
- 1.3.2 On-Premises
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2018: USD 1,000.00 million → 2032: USD 8,486.85 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2018
- 2.6.2 Forecast Period: 2018-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2018
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Trade Surveillance Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Trade Surveillance Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2018-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2018-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Trade Surveillance Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2018-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Trade Surveillance Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Trade Surveillance Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Trade Surveillance Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Trade Surveillance Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Trade Surveillance Market Outlook, 2018-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2018: USD 1,000.00 million → 2032: USD 8,486.85 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2018
- 11.2 Market Forecast, 2018-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Trade Surveillance Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2018
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Component - Market Size and Forecast, 2018-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2018-2032
- 12.3.4 Volume Forecast, 2018-2032
- 12.3.5 Base-Year Market Share, 2018
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Solutions
- 12.3.7.2 Risk and Compliance
- 12.3.7.3 Reporting and Monitoring
- 12.3.7.4 Surveillance & Analytics
- 12.3.7.5 Case Management
- 12.3.7.6 Others
- 12.3.7.7 Services
- 12.3.7.8 Managed Services
- 12.3.7.9 Professional Services
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Deployment - Market Size and Forecast, 2018-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2018-2032
- 12.4.4 Volume Forecast, 2018-2032
- 12.4.5 Base-Year Market Share, 2018
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Cloud Based
- 12.4.7.2 On-Premises
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Trade Surveillance Geographic Market Outlook, 2018-2032
- 13.1 Regional Market Size and Share, 2018
- 13.2 Regional Market Forecast, 2018-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Trade Surveillance Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2018-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Trade Surveillance Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2018
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2018-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Nasdaq, Inc.
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 NICE Actimize
- 17.4 ACA Group
- 17.5 Scila
- 17.6 Aquis Exchange
- 17.7 OneMarketData, LLC
- 17.8 Wipro
- 17.9 Red Deer
- 17.10 Crisil Limited
- 17.11 Software GmbH
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

